
Bottom line: Structured settlement buyer means a company or investor that purchases some or all future structured settlement payments for a discounted lump sum.
The sale usually requires court approval under state structured settlement protection laws. Sellers should compare offers, fees, discount rates, and tax or benefit effects before agreeing.
Structured Settlement Buyer is a company that purchases some or all future structured settlement payments for a discounted lump sum, subject to court approval under federal and state transfer rules.
The buyer’s offer reflects payment timing, total value, market rates, fees, and legal requirements.
Readers should compare quotes, review disclosures, and consult an independent attorney or financial adviser before selling, because a transfer can permanently reduce long-term income.
How structured settlement buyers work
Structured settlement buyers purchase some or all future annuity payments for a lump sum.
The process is regulated because most transfers require court approval under state Structured Settlement Protection Acts, and federal tax rules add penalties if a transfer does not meet legal standards.
In practice, the buyer reviews the payment stream, applies a discount rate, subtracts costs, and calculates a present-value offer.
The seller gets cash now, but usually receives less than the total of future payments because money paid today is valued more highly than money paid over time.
The key number is the discount rate.
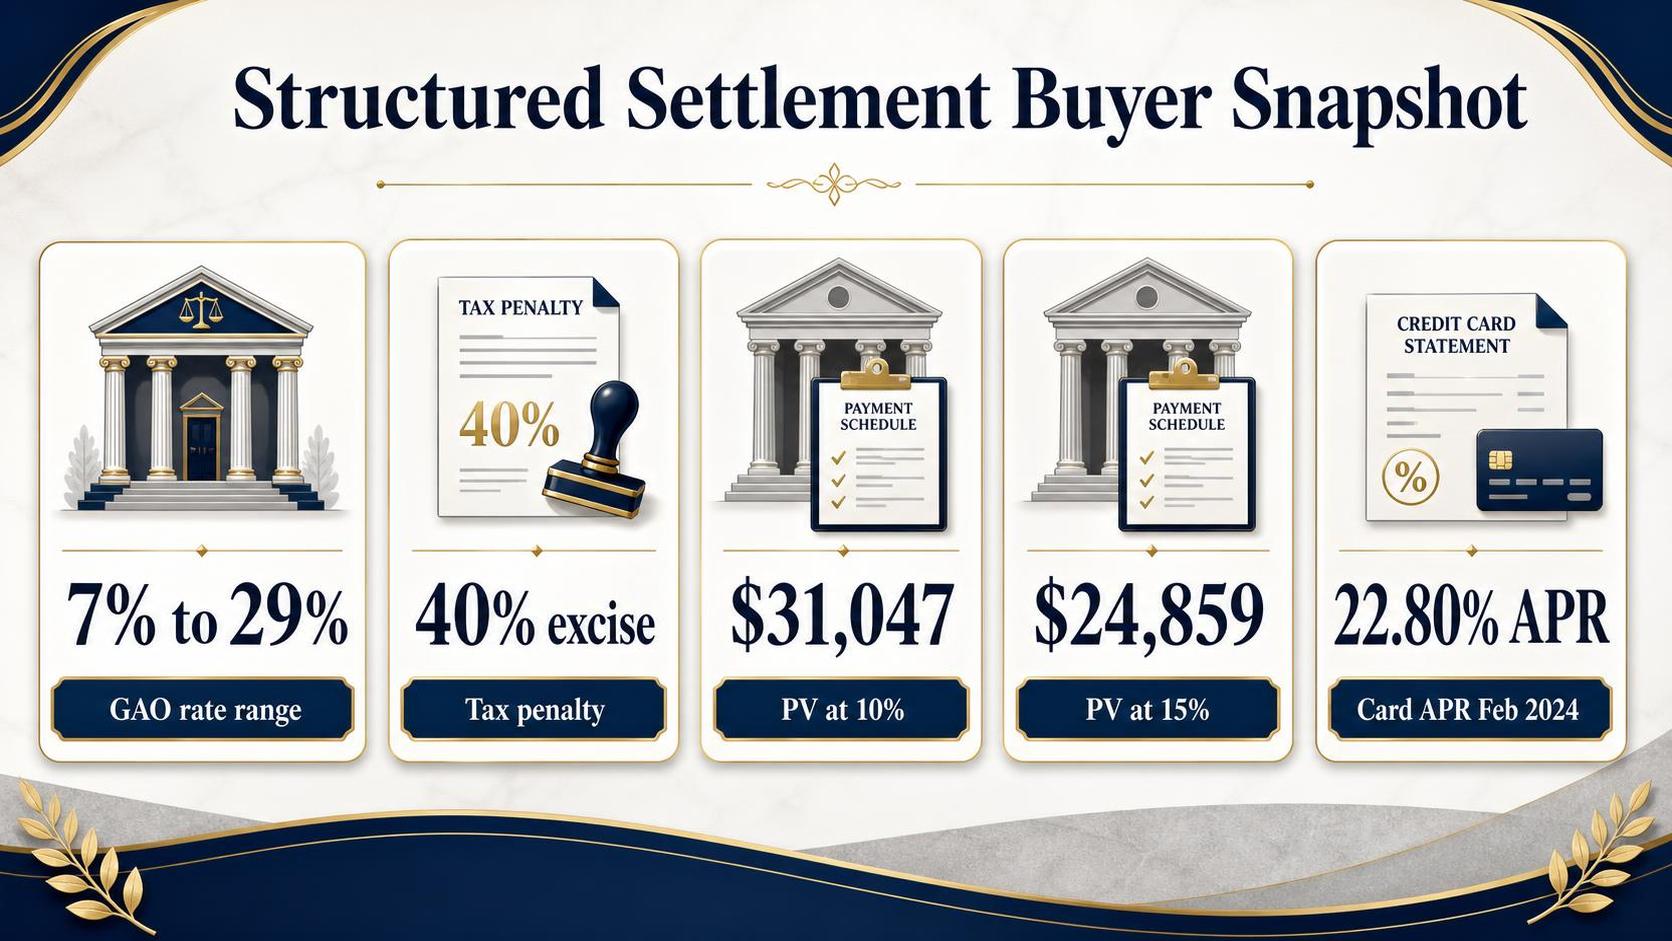
The U.S. Government Accountability Office said in a 2021 report that effective annual discount rates in structured settlement transfers it reviewed generally ranged from 7% to 29%, depending on the transaction and disclosures reviewed by GAO.
| Factor | How buyers use it | Why it changes the offer |
| Payment size | Larger payments usually increase present value | More cash is being assigned |
| Payment timing | Sooner payments are worth more than distant payments | Less time discounting future cash flows |
| Discount rate | Higher rate lowers the lump sum | Buyer prices risk, time, and profit |
| Court and legal costs | Fees can reduce net proceeds | Transfer approval requires filings and review |
A simplified example shows the mechanics. If a person assigns $50,000 due in five years, the present value at a 10% annual discount rate is about $31,047; at 15%, about $24,859.
Those figures come from standard present-value math, before legal fees or other deductions.
Most transactions follow the same steps:
- The seller requests quotes and provides annuity and settlement documents.
- The buyer estimates present value and issues a transfer agreement.
- Required disclosures are delivered. Federal law, 26 U.S. Code Section 5891, imposes a 40% excise tax on a factoring transaction that is not approved under a qualified court order.
- A court reviews whether the transfer is in the payee’s best interest under the applicable state protection act.
- If approved, the buyer pays the lump sum and receives the assigned payments from the annuity issuer.
Caution: a lower lump sum is not the only risk. Selling payments can reduce long-term income meant for medical care or living expenses.
Anyone considering a transfer should read the state statute, the disclosure statement, and the court papers before signing.
When selling payments may make sense
Selling structured settlement payments can make sense when a lump sum solves a costly problem that waiting would worsen.
The decision is usually strongest when the cash will reduce high-interest debt, prevent a housing crisis, pay for essential medical care, or fund a time-sensitive education or work expense.
It makes less sense when the money would go to routine spending, gifts, or speculative investing.
A buyer pays less than the total face value of future payments, and every sale must be reviewed under a state structured settlement protection law and approved by a court in most cases.
One common reason is expensive debt. The Federal Reserve reported the average annual percentage rate on credit card accounts assessed interest was 22.80% in February 2024. If a lump sum retires debt at that level, the savings can be material.
By contrast, the buyer’s discount reduces the value received upfront.
| Situation | Relevant figure | Source |
| Credit card payoff | 22.80% average APR on accounts assessed interest, February 2024 | Board of Governors of the Federal Reserve System, Consumer Credit G.19 |
| Emergency savings gap | Only 54% of U.S. adults had emergency savings to cover 3 months of expenses in 2024 | Bankrate, 2024 Annual Emergency Savings Report |
| Medical bill pressure | About 20 million adults, or nearly 1 in 12, owed medical debt in 2021 | KFF analysis of 2021 Survey of Income and Program Participation |
| Job training payoff | Median weekly earnings were $992 for high school graduates and $1,493 for bachelor’s degree holders in 2023 | U.S. Bureau of Labor Statistics, earnings by educational attainment |
That context helps identify situations where selling may be rational. A household without emergency reserves may use a partial sale to avoid eviction, repossession, or utility shutoff.
Bankrate’s 2024 survey shows many households do not have a three-month cushion, which is why immediate liquidity can matter.
- Paying off high-rate debt, especially credit cards, where interest compounds quickly.
- Covering essential medical treatment or medical debt. KFF found medical debt remains widespread.
- Funding education, licensing, or equipment tied to higher earnings. BLS wage data shows education can materially change pay.
- Preventing foreclosure, eviction, or loss of transportation needed to work.
- Using a partial sale instead of selling all payments, which may preserve future income.
Caution matters. A structured settlement often exists to provide long-term financial stability after an injury claim.
Before acting, review the discount rate, fees, tax questions, and court filings in writing, then compare a partial sale, a family loan, or nonprofit assistance. Check state law and the transfer agreement itself before signing.
How court approval protects sellers
Court approval is the main legal check before a structured settlement buyer can complete a transfer.
In most cases, the sale cannot close unless a judge reviews the deal under a state Structured Settlement Protection Act and the federal tax rules in 26 U.S. Code Section 5891.
That review matters because selling future payments can sharply reduce what the seller ultimately receives. A court process adds time, disclosure, and an independent decision-maker before an irreversible transaction is finalized.
The strongest federal backstop is tax-based.
Under 26 U.S. Code Section 5891(a), a transfer of structured settlement payment rights triggers a federal excise tax equal to 40% of the factoring discount unless the transfer has a “qualified order.” The source is the Internal Revenue Code,.
Enacted by Congress.
A qualified order is not automatic.
Under 26 U.S. Code Section 5891(b)(2), the order must find that the transfer does not contravene any statute or court order and is in the seller’s best interest, taking into account the welfare and support of the seller’s dependents.
That standard is a direct legal protection, not a marketing claim.
| Protection | Number or standard | Source |
| Federal excise tax without proper approval | 40% of the factoring discount | 26 U.S. Code Section 5891(a) |
| Cooling-off cancellation period in the model law | 3 business days after signing | National Conference of Insurance Legislators, Model State Structured Settlement Protection Act |
| Advance disclosure timing in the model law | Not less than 3 days before signing | National Conference of Insurance Legislators, Model Act |
State laws usually add procedure.
The National Conference of Insurance Legislators’ Model State Structured Settlement Protection Act requires a disclosure statement at least 3 days before the seller signs and gives the seller 3 business days to cancel after signing.
Many state statutes follow this framework, but wording differs by state.
Judges also review whether the paperwork is complete and whether the seller received required disclosures.
Those disclosures typically show the amounts being sold, the lump sum offered, fees, and the discounted present value, so the seller can compare what is being given up against what is being paid today.
There is a practical limit. Court approval does not guarantee that a deal is financially favorable. It means the transfer met the legal standard presented to the court.
Sellers should read the disclosure line by line and verify their state’s statute and local court procedure before signing anything.
- Check the exact state Structured Settlement Protection Act.
- Compare the gross payments being sold with the net cash to be received.
- Ask how fees, commissions, and the discount rate affect the payout.
- Get legal or financial advice if dependents or long-term income are involved.
Costs, discount rates, and cash offers
A structured settlement buyer usually prices a deal by discounting future payments into a present-day cash amount, then subtracting any disclosed fees. The discount rate matters most because a higher rate sharply lowers the offer.
The U.S. Government Accountability Office, in a 2012 report on structured settlement transfers, said contracts it reviewed used discount rates of about 9% to 18%.
That range is not a government cap. It is a reported market range from the GAO review.
A buyer may also deduct processing, legal, filing, or administrative charges if state law and the contract allow them, so the net cash can be lower than the headline offer.
The table below shows an illustration for one future payment of $100,000 due in 10 years. The 9% to 18% rates come from the GAO report. The cash values are mathematical present-value estimates before any fees.
| Assumption | Figure | Source |
| Future payment | $100,000 due in 10 years | Illustrative assumption for comparison |
| Offer at 9% discount rate | About $42,241 | Calculated present value using GAO-reported rate range |
| Offer at 12% discount rate | About $32,197 | Calculated present value using GAO-reported rate range |
| Offer at 15% discount rate | About $24,718 | Calculated present value using GAO-reported rate range |
| Offer at 18% discount rate | About $19,143 | Calculated present value using GAO-reported rate range |
| Observed contract discount rates | About 9% to 18% | U.S. Government Accountability Office, 2012 |
The pricing gap is large. In this illustration, moving from a 9% rate to an 18% rate reduces the pre-fee cash value by about $23,098. That difference shows why two buyers can quote very different amounts for the same payment stream.
- Ask for the gross advance amount, the discount rate, every fee, and the net amount to the seller.
- Ask whether the quote covers all payments or only selected payments. Selling fewer payments can preserve more long-term income.
- Compare multiple quotes on the same payments and same dates. Changing the payment mix can make a higher quote look better than it is.
Caution: do not judge an offer by speed alone. Structured settlement transfers usually require court approval under state structured settlement protection laws, and the judge may reject a deal that is not in the payee’s best interest.
Check the disclosure statement and court papers before signing.
How to compare structured settlement buyers
Compare buyers on net dollars, not marketing claims. The same payment stream can produce very different cash offers because the buyer chooses a discount rate, subtracts fees, and estimates how long court approval will take.
Ask each buyer for a written disclosure before signing anything. A transfer can trigger legal and tax consequences, and acting on a verbal quote alone can cause harm.
| Comparison point | What to ask | Why it matters |
| Net advance | What exact dollar amount will be paid after every deduction? | The gross purchase price can look high, but the net amount is what the seller actually receives. |
| Discount rate | What annual discount rate is being used? | A higher rate usually means less cash to the seller for the same future payments. |
| Fees and expenses | Which court, filing, processing, and legal costs are deducted, and which are not? | Fees can materially change the final proceeds even when two quotes start with similar headline numbers. |
| Timeline | How long does underwriting, filing, and court approval usually take in that state? | Funding is normally not immediate because structured settlement transfers usually require court approval. |
| Cancellation rights | Does state law or the contract provide a rescission period? | The right to cancel varies by state, so the buyer should identify the rule that applies. |
Start with the discount rate because it drives value. The Consumer Financial Protection Bureau has warned that consumers may receive far less than the present value of their payments when discount rates and fees are high.
A buyer that will not clearly state its rate is harder to compare.
Then verify the legal process. Under 26 U.S.C. Section 5891, a transfer that does not receive a qualified court order can trigger a 40% federal excise tax on the factoring transaction.
That rule makes court approval a core diligence item, not a formality.
Check the disclosure timing in the seller’s state. For example, New York General Obligations Law Section 5-1703 requires a separate disclosure statement at least 10 days before the payee signs a transfer agreement.
Other states use different deadlines, so the primary statute should be checked directly.
Ask for an itemized worksheet and compare offers side by side.
- Gross amount of payments being sold
- Present value, if disclosed
- Discount rate
- All deducted fees
- Net cash to seller
- Estimated court date and funding date
If a quote is urgent, incomplete, or hard to reproduce in writing, treat that as a warning sign. A structured settlement is often long-term income, so readers should consider legal or financial advice before signing.
What editors independently checked
Editors checked the legal, tax, and consumer-protection basics behind any company described as a structured settlement buyer.
The goal was simple: confirm what the company can legally buy, what approvals are required, and where a seller could face cost or risk.
Editors did not rely on marketing copy alone. They reviewed primary law, regulator material, and company disclosures where available, then matched claims against the source text.
| Check | What was verified | Primary source |
| Court approval | A transfer of structured-settlement payment rights can trigger a federal 40% excise tax if it is not a “qualified order” under state law. | Internal Revenue Code, 26 U.S.C. § 5891 |
| Disclosure timing | Federal tax law ties a qualified transfer to a state Structured Settlement Protection Act process, which generally requires advance written disclosure and court review. | Internal Revenue Code, 26 U.S.C. § 5891; applicable state Structured Settlement Protection Act |
| Who must get notice | State statutes commonly require notice to “interested parties,” such as the annuity issuer and structured-settlement obligor, before a judge can approve a sale. | Applicable state Structured Settlement Protection Act; model references often track definitions used in 26 U.S.C. § 5891 |
| Consumer warnings | The federal consumer watchdog has warned that selling future payments can leave people with less long-term income than expected and may affect public benefits planning. | Consumer Financial Protection Bureau consumer resources on structured settlements |
Editors also checked whether a buyer openly explains its pricing. A buyer usually pays less than the face value of future payments because it applies a discount rate and subtracts fees if allowed by state law.
No universal “good rate” exists. If a site quoted a percentage, editors looked for a dated disclosure, sample contract, or court filing support. If that support was missing, the rate was not treated as verified fact.
Editors verified the tax rule because it matters. The 40% federal excise tax in 26 U.S.C. § 5891 is aimed at noncompliant transfers, which is why legitimate buyers generally require a court-approved process rather than a private side deal.
Editors also checked whether a company distinguishes itself from a lender. A structured settlement buyer purchases payment rights; it is not the same product as a loan, cash advance, or line of credit.
Plain caution: state rules differ, and a sale can permanently reduce future income.
Before signing, compare the buyer’s disclosure with the exact statute in the payee’s state and consider independent legal or tax advice from a qualified professional.
Risks before signing a transfer agreement
Selling structured settlement payments can solve a cash shortfall, but the contract can be expensive and hard to reverse.
The largest risks usually come from the discount rate, added fees, tax misunderstandings, and signing before a court reviews the transfer.
Before signing, compare the cash offer with the present value of the payments being sold.
Read every fee line, ask how the buyer calculated the discount rate, and verify your state’s transfer rules with the court or the state’s Structured Settlement Protection Act.
The biggest financial risk is accepting far less than the payment stream’s estimated current value.
The U.S. Government Accountability Office reported in 2021 that transfer companies in sampled transactions applied discount rates from 4.4% to 29.9%, and one state judge told GAO that rates above 18% were common in that court’s cases.
| Risk point | Verified fact | Source |
| Discount rate range | 4.4% to 29.9% in sampled transfers | U.S. GAO, “Structured Settlements: Factors to Consider Before Selling Payments,” 2021 |
| High rates noted by court | One judge reported rates above 18% were common | U.S. GAO, 2021 |
| Federal tax on unapproved transfer factoring income | 40% excise tax can apply if the transfer does not meet federal requirements | Internal Revenue Code Section 5891 |
Fees are another risk because they reduce net cash even if the headline offer looks acceptable. Contracts may include underwriting, processing, closing, legal, or administrative charges.
If a fee is not listed in dollars, ask for a revised disclosure before signing. Do not rely on verbal explanations alone.
Tax errors can also hurt. Under Internal Revenue Code Section 5891, a factoring company faces a 40% excise tax on the “factoring discount” unless the transfer is approved in a qualified court order under applicable state law.
Readers should not assume a transfer is automatically tax-safe because a salesperson says so.
Timing matters. Consumer Financial Protection Bureau guidance on debt relief and cash-flow stress warns consumers to scrutinize lump-sum offers made during financial emergencies, because urgent need can weaken comparison shopping.
A rushed signature can lock in years of lost future income.
- Ask for the gross amount being sold, the net amount paid, every fee, and the annual discount rate in writing.
- Check whether the agreement allows cancellation, and confirm the exact deadline from the contract and state law.
- Bring the offer to a lawyer or financial adviser. Acting on marketing alone can cause permanent loss of protected income.
Alternatives to selling settlement payments
Selling future structured settlement payments is not the only way to raise cash. Other options may cost less, preserve guaranteed income, or avoid court approval, depending on credit, savings, and the size of the expense.
Start by comparing the full dollar cost, not only the monthly payment. For money decisions with legal and tax consequences, confirm terms with the lender, bank, benefit program, or settlement issuer before acting.
Use emergency savings first
If cash is needed for a short-term bill, existing savings may be the least risky option.
The Federal Reserve reported that 63% of U.S. adults said they could cover a $400 emergency expense with cash or its equivalent in 2023, while 13% would not be able to cover it by any means.
Using savings avoids interest, origination fees, and discount rates. The tradeoff is lower reserves for later emergencies, so rebuilding the fund should be part of the plan.
Consider a credit union, bank, or personal loan
Traditional borrowing can be cheaper than selling long-term settlement income, especially for borrowers with strong credit.
The National Credit Union Administration says federal credit unions may charge a maximum annual percentage rate of 18% on most loans, with a temporary Payday Alternative Loan II cap of 28% through March 10, 2025.
Rates at banks and online lenders vary by credit profile and state law. Check the APR, total finance charge, late fees, and whether the loan is secured before signing.
Ask providers about hardship plans
Hospitals, utilities, and mortgage servicers sometimes offer payment plans or relief.
For example, the Consumer Financial Protection Bureau states that mortgage servicers can offer loss-mitigation options such as repayment plans, forbearance, or loan modifications for struggling borrowers.
These arrangements may reduce immediate pressure without giving up future settlement checks. Missed deadlines can still trigger fees or collections, so get all terms in writing.
Review public and nonprofit assistance
Some needs can be met through aid rather than financing. The U.S. Department of Health and Human Services said the Low Income Home Energy Assistance Program helped about 5.9 million households in fiscal year 2023.
Eligibility depends on income, household size, and state rules. Check official program websites or local agencies because benefits, deadlines, and available funding can change.
| Alternative | Potential cost | Source |
| Use savings | No interest; loss of liquidity | Federal Reserve, Economic Well-Being of U.S. Households in 2023 |
| Credit union loan | Up to 18% APR for most federal credit union loans | NCUA lending regulation |
| Payday Alternative Loan II | Up to 28% APR | NCUA, temporary authority through March 10, 2025 |
| Hardship plan | Varies; may reduce or defer payments | CFPB mortgage relief guidance |
| Energy assistance | Grant aid, not repaid if eligible | HHS LIHEAP fiscal year 2023 data |
If a company promises fast cash against settlement payments, compare that option against these alternatives line by line.
A structured settlement often exists to provide long-term stability, so replacing guaranteed future income should be a last resort, not a first step.
Frequently Asked Questions
What is a structured settlement buyer?
A structured settlement buyer is a company that purchases some or all future structured settlement payment rights in exchange for a lump sum.
These transactions are regulated because federal law in 26 U.S. Code Section 5891 imposes a 40% excise tax unless the transfer is approved under a qualified state structured settlement protection act, so a court process is usually required.
How does a structured settlement buyer make money?
The buyer pays less today than the total future payments it expects to receive, and the difference reflects discounting, risk, legal costs, and profit.
The National Association of Settlement Purchasers states that transfer prices are based in part on the time value of money, while the Consumer Financial Protection Bureau has warned consumers to review the effective cost carefully before selling payments.
Do structured settlement buyers need court approval?
In most cases, yes. The transfer generally must be approved under the seller’s state structured settlement transfer law to avoid the federal 40% excise tax in 26 U.S. Code Section 5891, but readers should check the exact statute and local court rules in their state because procedures and required disclosures vary.
How are discount rates for structured settlement sales determined?
There is no single nationwide rate set by law.
Pricing depends on the payment schedule, amount being sold, insurer strength, case complexity, and state approval costs; because rates change and may not be published uniformly.
Readers should ask the buyer for a written disclosure and compare it with the state-required transfer documents before signing.
Can a person sell only part of a structured settlement?
Yes, many transfers involve selling only selected payments rather than the full stream.
That can reduce the cash raised today and preserve later income, but the long-term tradeoff still matters, so the seller should review the payment schedule, net advance, and any fees in the court disclosure package before acting.
What documents does a structured settlement buyer usually request?
Common documents include the original settlement or annuity paperwork, payment schedule, identification, and information about the issuing insurance company and any prior transfers.
Some states also require independent professional advice disclosures or specific notices under state structured settlement protection acts, so the seller should verify requirements with the court forms or statute.
What are the main risks of using a structured settlement buyer?
The main risk is giving up future guaranteed income for less cash today, which can create problems later if the lump sum is spent quickly.
The Federal Trade Commission advises consumers to be cautious with settlement-related financial offers, and anyone considering a sale should review the court papers, confirm the buyer’s terms in writing.
And get legal or financial advice before making an irreversible decision.
Related Reading
- Buy Structured Settlement – What You Need to Know?
- Structured Settlement Broker
- AIG Structured Settlements – The Truth You Didn't Know
- Structured Settlement Interest Rates
- JG Wentworth Structured Settlement
- American General Structured Settlements
- Vanguard Immediate Annuity Rates
- Structured Settlement Quotes
- Structured Settlement Funding
- All Blog Guides