
Bottom line: Top 10 Brilliant Money Saving Tips: automate savings, track spending, build a realistic budget, cancel unused subscriptions, cook at home, compare insurance and utility costs, use cashback strategically, avoid high-interest debt,.
Set a 24-hour rule for purchases, and build an emergency fund.
Caution: compare terms before changing financial products.
Top 10 Brilliant Money Saving Tips are practical habits for closing the gap between rising costs and limited cash flow: the U.S. personal saving rate was 3.7% in December 2024, according to the Bureau of Economic Analysis.
These tips matter because pressure is measurable: the Federal Reserve’s 2023 Survey of Household Economics found 37% of adults could not cover a $400 emergency entirely with cash, savings, or a credit card paid off at the next statement.
The trade-off is time, convenience, and sometimes quality of life. Cutting subscriptions, refinancing debt, or changing insurance can help, but fees, lost benefits, or coverage gaps can erase savings.
Check account terms, tax rules, and policy documents before acting.
Start with expenses the BLS tracks
The fastest way to cut spending is to start where households already spend the most. The U.S. Bureau of Labor Statistics tracks these categories in its Consumer Expenditures Survey, and the biggest line items usually offer the biggest savings opportunities.
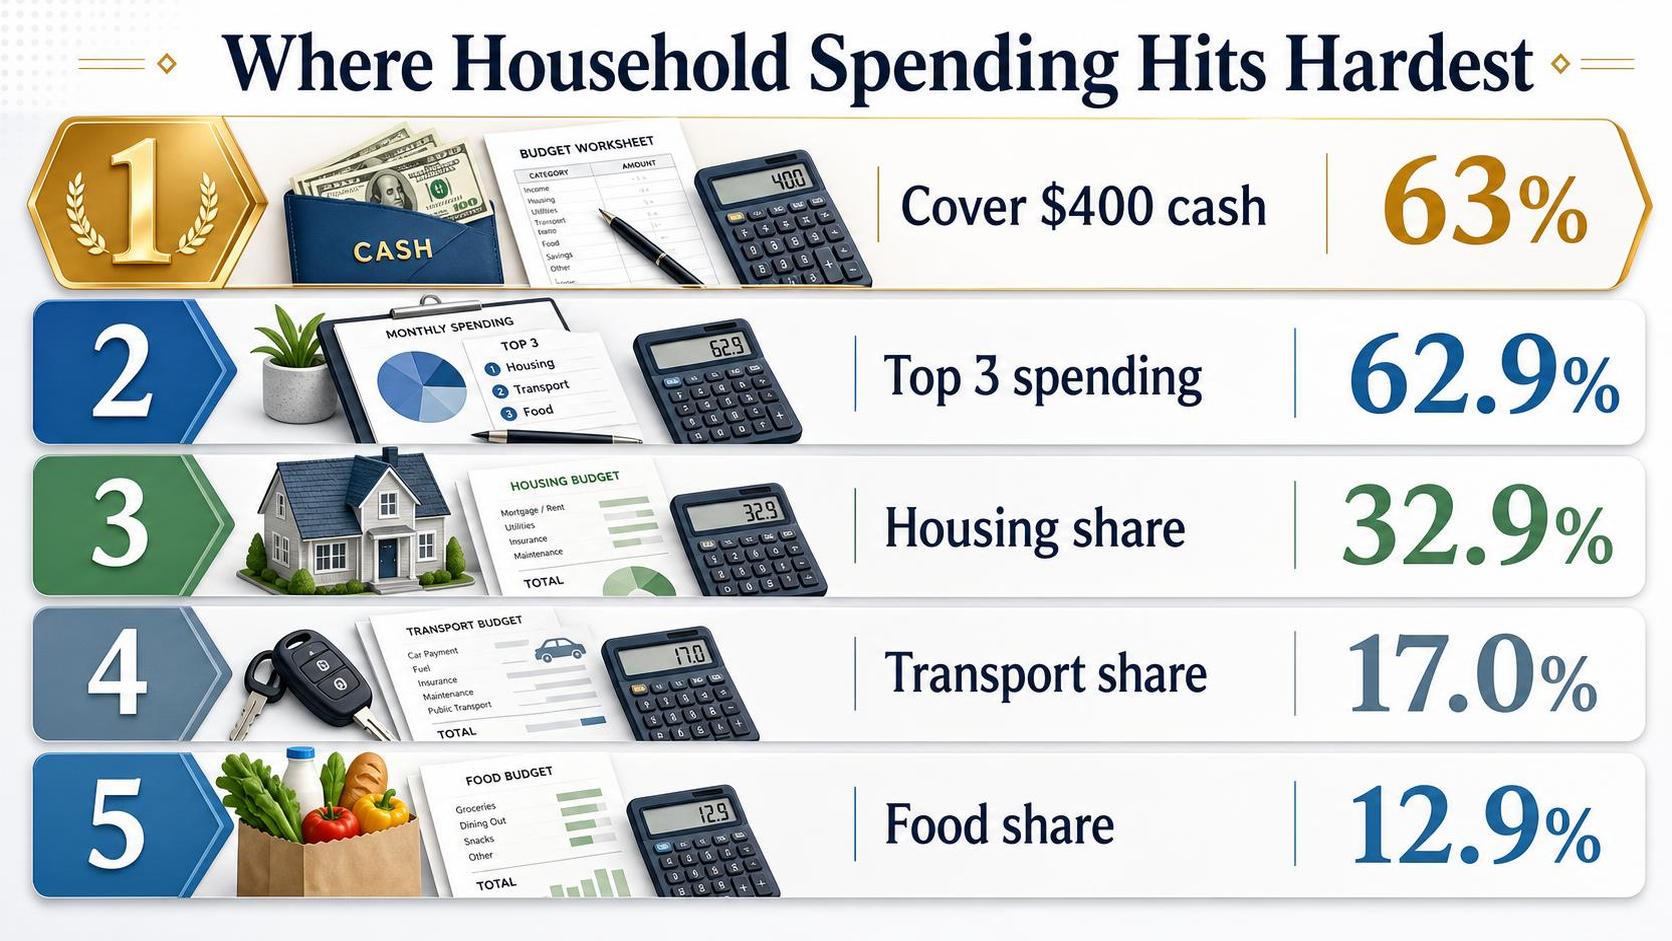
In 2023, the average U.S. consumer unit spent $77,280, according to the BLS. Housing alone was $25,436, or 32.9% of total spending, making it the first place to review before chasing small coupon wins.
| BLS category, 2023 | Average annual spending | Share of total |
| Housing | $25,436 | 32.9% |
| Transportation | $13,174 | 17.0% |
| Food | $9,985 | 12.9% |
| Personal insurance and pensions | $9,582 | 12.4% |
| Healthcare | $6,159 | 8.0% |
| Entertainment | $4,280 | 5.5% |
Source: U.S. Bureau of Labor Statistics, Consumer Expenditures Survey, 2023.
That table gives a practical order. Review housing, transportation, and food first. Together, those three categories totaled $48,595 in 2023, or 62.9% of average spending, based on BLS data.
Housing cuts can matter most, but the trade-off can be severe. Moving to a cheaper apartment may lower rent, yet raise commuting costs, reduce school options, or trigger lease-break fees. Check the full monthly impact, not rent alone.
Transportation is another high-leverage category. A cheaper vehicle, fewer financed upgrades, or lower insurance coverage limits can reduce costs. The downside is reliability risk, higher repair bills, or being underinsured after a crash.
Read policy terms before changing coverage.
Food is easier to trim without major disruption, but savings can be overstated. Cooking at home usually costs less than frequent restaurant meals, yet bulk buying can backfire if food is wasted.
The U.S. Department of Agriculture estimates 30% to 40% of the food supply is wasted, and the U.S. Environmental Protection Agency says food is the most common material landfilled and incinerated in the United States.
- Use BLS categories to find the biggest target, not the easiest target.
- Compare any cut against new costs, fees, time, and risk.
- Do not cancel insurance, retirement contributions, or healthcare blindly. A short-term saving can create a larger long-term loss.
Caution: BLS averages are benchmarks, not personal advice. Actual costs vary by income, family size, health, debt, and location, so confirm numbers against current bills and primary provider disclosures before acting.
Build a budget from Federal Reserve data
A budget works better when it starts with real household stress data, not wishful percentages.
The Federal Reserve’s 2023 Survey of Household Economics and Decisionmaking, or SHED, shows where many U.S. households break down first: cash flow, emergency savings, and debt pressure.
Use that evidence to set priorities. Fund essentials first, build a small cash buffer second, and treat discretionary spending as the final category, not the first.
The clearest benchmark is emergency resilience.
In the Fed’s 2023 SHED report, 63% of adults said they would cover a $400 emergency expense using cash or its equivalent, which means 37% would borrow, sell something, or miss payment obligations.
Source: Board of Governors of the Federal Reserve System, Economic Well-Being of U.S. Households in 2023.
| Federal Reserve figure | What it means for a budget |
| 63% could cover a $400 emergency with cash or equivalent | Set a first savings target of at least $400 before increasing nonessential spending |
| 37% could not cover that expense with cash or equivalent | Assume irregular bills are budget items, not surprises |
| 13% said they were not able to pay all bills in full in the month before the survey | Prioritize minimum debt payments, housing, utilities, food, and insurance before extras |
| 72% said they were doing okay financially or living comfortably | 28% were struggling at least somewhat, so a budget needs margin, not perfection |
That suggests a practical sequence. First, list fixed essentials: housing, utilities, insurance, minimum debt payments, groceries, and transport to work.
Second, add a line for “known irregulars” such as car repairs, annual fees, school costs, and medical bills.
Third, create a buffer line. If the first target is $400, a person saving $34 a month reaches about $408 in 12 months. That number is arithmetic, but the target comes from the Federal Reserve emergency-expense benchmark.
The downside case matters. Cutting too aggressively can backfire if it pushes medical care, insurance, or car maintenance out of the budget. Missing those categories can create larger future costs or lost income from missed work.
There is also an income problem some budgets cannot solve. If essentials exceed take-home pay even after cuts, the safer move is to seek housing, utility, food, or credit-counseling assistance and verify options with primary sources.
A budget is a tool, not a substitute for income.
Plain caution: Federal Reserve data are national snapshots, not personal advice. Before changing debt payments, insurance coverage, or tax withholding, check statements, plan documents, and current terms from the original provider.
Cut food costs without nutritional trade-offs
Food savings work best when the target is cost per serving, not simply buying less.
The U.S. Department of Agriculture says a nutritious diet can be built around vegetables, fruits, grains, dairy, and protein foods in lower-cost forms, but cutting too hard can reduce diet quality if purchases shift toward ultra-processed convenience foods.
A practical benchmark is the USDA Cost of Food at Home report.
For a family of four on the Thrifty Food Plan in June 2024, the weekly cost was $225.10, while the Liberal plan was $358.90, according to the USDA Center for Nutrition Policy and Promotion.
That gap shows how much food spending can move without changing the goal of meeting nutritional needs.
| USDA food plan | Weekly cost, family of 4, June 2024 |
| Thrifty | $225.10 |
| Low | $243.00 |
| Moderate | $301.20 |
| Liberal | $358.90 |
Start with protein swaps that preserve nutrition. The U.S. Bureau of Labor Statistics reported an average price of $4.917 per pound for 100% ground beef in June 2024.
The USDA reported a national average retail price of about $1.70 per pound for dry pinto beans in 2024 market data. Beans cost less and add fiber, but they do not fully replace meat’s vitamin B12, so a total switch requires planning.
Frozen and canned produce can also cut waste without major nutrient loss.
The USDA and Academy of Nutrition and Dietetics note that frozen fruits and vegetables are nutritionally comparable to fresh in many cases because they are processed soon after harvest.
The trade-off is sodium or added sugar in some canned products, so compare labels and choose “no salt added” or fruit packed in juice.
- Plan meals around ingredients used more than once. The USDA says food waste raises household costs; using the same spinach, rice, or chicken across several meals reduces spoilage risk.
- Buy store brands where quality is regulated. The FDA requires the same ingredient labeling rules for national and private-label foods.
- Use unit prices. The Federal Trade Commission says unit pricing helps compare value across package sizes, but larger packages save money only if the food is actually used.
Avoid false economies. Warehouse sizes, coupon deals, and “healthy” snack packs can raise total spending if they increase waste or impulse buying.
Readers should check current local prices, nutrition labels, and any dietary needs before changing a household food plan.
Lower housing and utility bills safely
Housing and utilities are large household costs, so small efficiency gains can matter.
The safest cuts usually come from reducing waste, using assistance programs, and avoiding repairs deferred too long, because cheap fixes can become expensive damage later.
Start with the measures that have published savings estimates from federal sources. They are not guaranteed for every home, but they are more reliable than broad promises from contractors or social media.
| Action | Typical impact | Source | Trade-off or caution |
| Seal air leaks and add insulation | Average savings of 15% on heating and cooling costs, or 11% on total energy costs | U.S. EPA, ENERGY STAR | Upfront cost can be meaningful. Poor ventilation work can worsen moisture or indoor air problems. |
| Set back the thermostat 7°-10°F for 8 hours a day | Up to 10% a year on heating and cooling | U.S. Department of Energy, Energy Saver | Comfort may drop. In very cold weather, unsafe indoor temperatures can be risky for children, older adults, and some medical conditions. |
| Fix household water leaks | About 10% savings on water bills | U.S. EPA, WaterSense | Hidden leaks can indicate plumbing damage. Delaying repair can raise both water and repair bills. |
| Switch to LED lighting | At least 75% less energy use and lasts up to 25 times longer than incandescent lighting | U.S. Department of Energy | Savings depend on how often lights are used. Cheap bulbs may have poor color quality or shorter life. |
For renters, the safest housing savings often come from asking about lease renewal terms before the deadline, checking for utility-included units, and documenting maintenance issues early.
The U.S. Census Bureau reported the median asking rent was $1,470 in the first quarter of 2024, so even a modest concession can matter.
Do not cut costs by ignoring roof leaks, mold, electrical issues, or heating failures. A lower bill is not worth a habitability or safety problem.
If a landlord will not address dangerous conditions, check state or local housing agency guidance before withholding rent.
Households with low incomes should also check utility assistance.
The federal Low Income Home Energy Assistance Program, or LIHEAP, is designed to help with home energy costs, but eligibility and benefit amounts vary by state, according to the U.S. Department of Health and Human Services.
Before paying for upgrades, compare the project cost with the expected annual savings and ask for product documentation. If a contractor claims guaranteed savings, verify the numbers against DOE, EPA, or the local utility program rules.
Compare debt payoff against emergency savings
Sending every extra dollar to debt can save more interest than a savings account earns. But a zero-dollar cash cushion can force a household to borrow again when a car repair or medical bill hits.
The trade-off is mathematical and behavioral. High-interest debt usually costs far more than cash savings pay, yet an emergency fund reduces the risk of new borrowing, late fees, and missed payments.
The Federal Reserve’s 2024 report on the economic well-being of U.S. households said 63% of adults would cover a $400 emergency expense using cash or its equivalent, while 13% would not be able to cover it by any means.
That gap explains why many planners favor a small starter emergency fund before aggressive debt payoff.
For expensive revolving debt, the math is severe. The Federal Reserve’s G.19 consumer credit release reported that the average annual percentage rate on credit card accounts assessed interest was 22.80% in November 2023.
By contrast, the FDIC reported the national average savings deposit rate was 0.45% APY on August 18, 2025.
| Choice for $1,000 | Rate used | One-year effect | Source |
| Pay down credit card balance | 22.80% APR | About $228 in interest avoided if that balance would otherwise remain for a year | Federal Reserve G.19, November 2023 |
| Put money in average savings account | 0.45% APY | About $4.50 in interest earned over a year before tax | FDIC national deposit rates, August 18, 2025 |
That spread suggests high-rate credit card debt often deserves priority. A small emergency reserve can still make sense first.
Consumer.gov, a U.S. government consumer education site, recommends starting with a goal of $500 for emergencies, then building more over time.
A common middle path is to build a starter fund, then attack the highest-rate debt. After the costliest balance is under control, increase savings toward a larger reserve, often measured in months of essential expenses.
- Prioritize savings first if income is irregular, housing is unstable, or a major bill is likely soon.
- Prioritize debt first if the balance carries double-digit interest and there is no 0% promotional period.
- Recheck the numbers if a loan has a lower fixed rate than a savings account or money market fund.
Caution: rates, fees, taxes, and promotional terms change. Before moving cash, verify the loan APR, the account APY, and any penalties in the lender’s and bank’s current disclosures.
Automate savings while avoiding overdraft fees
Automatic transfers can build savings without relying on willpower. The risk is timing: a transfer that leaves checking too low can trigger overdraft or non-sufficient funds fees, which can erase the benefit of a small weekly savings plan.
The Consumer Financial Protection Bureau said large banks reported about $5.8 billion in overdraft and non-sufficient funds revenue in 2023, down from roughly $12.6 billion in 2019.
That drop shows fees are becoming less common, but they still matter for households living paycheck to paycheck.
Start by matching the transfer date to income, not to the calendar. A transfer scheduled for the day after payroll posts is usually safer than one set for the first of the month, because deposit timing can shift around weekends and federal holidays.
Keep the first transfer small.
The Federal Reserve reported that 37% of U.S. adults would cover a $400 emergency expense using cash or its equivalent in 2023, while 63% said they would cover it fully with cash, savings, or a credit card paid off at the next statement.
That gap suggests many households need liquidity more than an aggressive savings target. A modest recurring transfer can still work if it does not force card balances, late bills, or repeated fee risk.
| Figure | Amount | Source |
| Large-bank overdraft and NSF revenue, 2019 | $12.6 billion | Consumer Financial Protection Bureau, 2024 data spotlight |
| Large-bank overdraft and NSF revenue, 2023 | $5.8 billion | Consumer Financial Protection Bureau, 2024 data spotlight |
| Adults who would use cash or its equivalent for a $400 emergency, 2023 | 37% | Federal Reserve, Report on the Economic Well-Being of U.S. Households |
| Adults who would fully cover a $400 emergency with cash, savings, or a paid-off credit card, 2023 | 63% | Federal Reserve, Report on the Economic Well-Being of U.S. Households |
Use bank tools before turning automation on. Many banks now offer low-balance alerts, balance buffers, and overdraft settings.
The CFPB has also documented that some institutions reduced or eliminated overdraft and NSF fees, so checking the current account terms can save money.
- Set alerts for a balance floor that covers bills plus the transfer.
- Move savings the day after payday, not before autopay bills clear.
- Review one full month of cash flow before increasing the amount.
- Pause transfers during irregular-income months or known large expenses.
The downside case is simple: if a $25 transfer causes a $35 fee, the system is working against the saver.
Fee schedules and overdraft rules vary by institution, so verify current terms directly with the bank or credit union before relying on any automated plan.
What Coin Abul independently reviewed
Coin Abul reviewed current U.S. household cost data, savings yields, credit pricing, and consumer spending figures from federal agencies and large market trackers.
The goal was simple: identify money-saving ideas supported by current numbers, not slogans.
The review focused on actions that can affect a typical budget quickly, including earning more on cash, reducing interest costs, and trimming large recurring expenses.
Readers should still verify rates, fees, and eligibility with the primary provider before acting.
Several findings stood out. Cash sitting in a low-yield account can lose purchasing power when inflation stays elevated.
The U.S. Bureau of Labor Statistics said the Consumer Price Index rose 3.3% over the 12 months ending May 2024, while many traditional savings accounts paid far less, according to the FDIC.
| Measure reviewed | Latest figure | Source | Why it matters |
| Average savings account rate | 0.45% APY as of June 17, 2024 | FDIC National Rates and Rate Caps | Idle cash may earn very little |
| Top-end high-yield savings rates | Above 4% APY in mid-2024 | Bankrate market tracking | Rate shopping can materially lift interest earned |
| Inflation | 3.3% over 12 months ending May 2024 | U.S. Bureau of Labor Statistics | Low-yield cash can lose real value |
| Average credit card APR for assessed interest accounts | 22.76% in February 2024 | Federal Reserve G.19 | Paying down revolving debt can beat most safe returns |
The debt finding matters because a guaranteed 22.76% interest cost is usually more damaging than a small monthly spending leak. The trade-off is liquidity.
Using spare cash to pay debt can leave a thinner emergency buffer, which may force new borrowing if an unexpected bill arrives.
Food spending also showed a clear pattern. The U.S. Department of Agriculture reported food-away-from-home prices rose 4.0% over the year ending May 2024, while food-at-home prices rose 1.0%.
Cooking more often can save money, but only if the household actually uses what it buys.
| Spending category reviewed | Price change | Source | Downside case |
| Food at home | +1.0% year over year, May 2024 | USDA using BLS CPI data | Waste can erase savings |
| Food away from home | +4.0% year over year, May 2024 | USDA using BLS CPI data | Convenience may justify the extra cost for some workers |
| Average annual auto insurance premium | $2,543 for full coverage in 2024 | Bankrate | Shopping quotes can help, but lower premiums may mean higher deductibles |
The insurance review supports another common tip: re-shop recurring bills. Bankrate estimated the average full-coverage auto premium at $2,543 in 2024. That creates room to compare quotes, but readers should check coverage limits carefully.
A cheaper policy can expose a household to larger out-of-pocket losses after a claim.
Frequently Asked Questions
What is the fastest money saving tip most people can start today?
Tracking spending is usually the fastest starting point because it shows where cash is going before new rules are added.
The U.S. Bureau of Labor Statistics Consumer Expenditure Survey shows housing, transportation, and food are major household expense categories, so reviewing those first can reveal the biggest savings opportunities.
How much should go into savings each month?
There is no single correct number because income, debt, rent, and family costs differ.
A practical approach is to save a fixed percentage or fixed dollar amount from each paycheck, then verify affordability against a written budget; the Consumer Financial Protection Bureau recommends building an emergency cushion.
But readers should not copy a target blindly if it causes missed bills or high-interest borrowing.
Do automatic transfers actually help people save money?
Automatic transfers can help because they move money before it is spent elsewhere, reducing reliance on willpower.
The Federal Reserve has reported that many U.S. adults would struggle with an unexpected expense, which is one reason automatic savings is commonly recommended, but the transfer amount should be small enough to avoid overdraft fees.
Related Reading
- How Much Does It Cost To Open A Coffee Shop?
- Why Personal Finance Is Important?
- How Much Does A Warehouse Cost?
- How Much Is The Apartment? What You Need to Know
- How Much Home Appraisal Cost?
- When Does Apartment Prices Go Down?
- When Do Kitchen Appliances Go On Sale?
- Price Of Apartment In Manhattan
- All Blog Guides