
Key takeaway: Oasis Loan Number usually means the account or case number assigned by Oasis Financial for a pre-settlement funding or legal funding transaction. It may appear on funding documents, emails, or account communications.
Because Coin Abul is not Oasis, borrowers should verify the number directly with Oasis Financial or their attorney before sharing payment or case information.
Oasis Loan Number is commonly used to mean the customer-service phone line for Oasis Financial, a legal funding company, not a traditional loan servicer.
Readers usually search it to verify an account, ask about pre-settlement funding, or confirm payoff details. Because legal funding terms can affect case proceeds, use only official Oasis Financial contact information.
This article explains how to find the correct Oasis phone number, what information to have ready, and what to avoid sharing with unverified callers.
Plain caution: do not rely on a search-result snippet or third-party directory before discussing money, settlement proceeds, Social Security numbers, or attorney information; confirm details through the company’s official website or written contract.
How to find the Oasis loan number
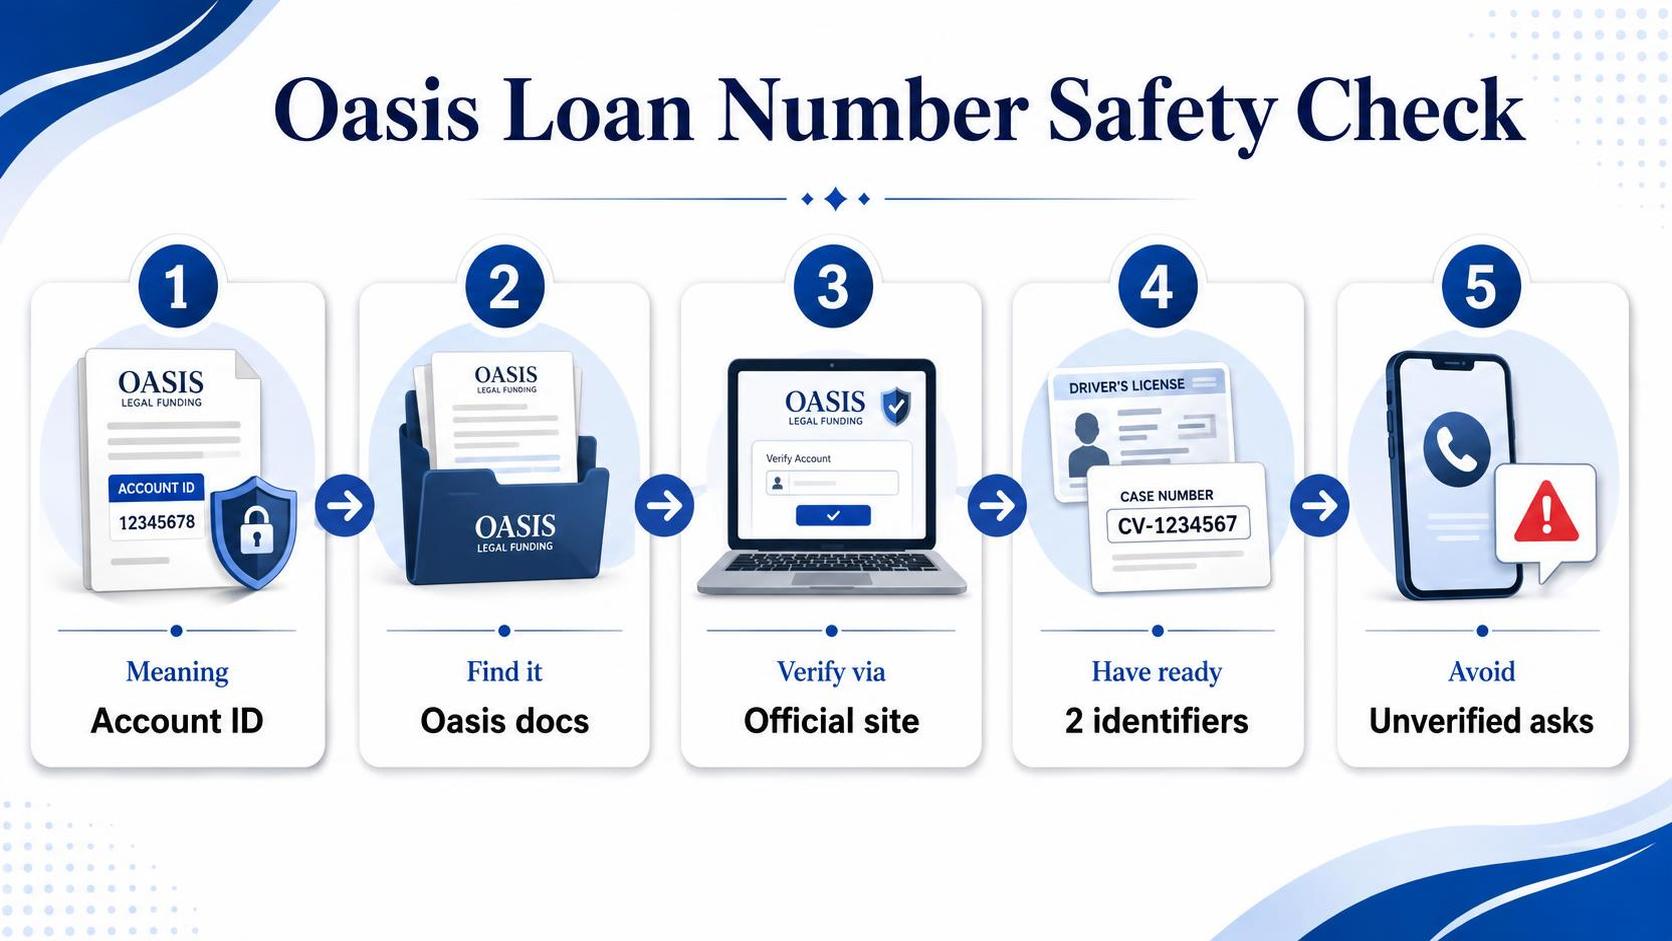
The Oasis loan number is usually the account or reference number tied to a signed funding agreement, payoff letter, or account statement.
The safest method is to pull it from an original Oasis document, then match it against a second record before using it.
If no document is available, use Oasis’s official customer-service channel listed on the company’s own website or in the signed contract. Do not rely on a number sent in an unsolicited text, email, or social media message.
Start with the paperwork created when the advance was approved. For legal funding, the most reliable records are the executed agreement, any disbursement confirmation, and later payoff or balance notices.
| Where to look first | What label may appear | Why it helps |
| Signed funding agreement | Account number, reference number, client number, or agreement number | This is the original source issued when the transaction was opened |
| Funding confirmation or wire/ACH notice | Reference number or transaction ID | This can help Oasis match the file if the account number is missing |
| Payoff statement or balance letter | Account number or payoff reference | This is often the fastest document for identity verification |
| Email from the company domain | Case reference or account reference | Useful if paper records were lost, but verify the sender before replying |
If the number is not obvious.
Search the document for terms such as “account,” “reference,” “agreement,” “client,” or “payoff.” Many finance companies place the identifier near the top of page 1 or in the subject.
Line of emailed notices.
Before calling, gather 2 matching identifiers from your records, such as your full name and the date the funds were sent. Using two records reduces the risk of quoting the wrong file number if you have had more than one case.
Use caution with personal data.
The Federal Trade Commission says identity thieves can misuse account numbers and other financial details, so avoid sending a full Social Security number or full bank details by unsecured email or text; use the company’s verified process instead.
Source: Federal Trade Commission consumer identity-theft guidance.
If documents conflict, stop and verify through Oasis directly using the contact details on the signed agreement or the official company website. For legal or payoff decisions, rely on the latest written statement, not memory alone.
Oasis Financial phone numbers and contact options
If a reader needs to reach Oasis Financial, the safest starting point is the company’s official contact page and loan paperwork. Phone numbers, departments, and even brand names can change after acquisitions or corporate updates.
As of commonly cited company listings, Oasis Financial has used a toll-free customer number, a direct corporate line, and a fax number.
Readers should confirm each number on Oasis Financial’s current website or signed agreement before sending personal or legal documents.
| Contact option | Number or channel | Source named |
| Customer service / general toll-free line | (866) 353-6680 | Oasis Financial contact listings commonly published by the company and mirrored in business directories |
| Corporate / local office line | (847) 281-8200 | Corporate listings associated with Oasis Financial |
| Fax | (847) 281-8545 | Corporate contact listings associated with Oasis Financial |
| Website contact form | Online form on the official Oasis Financial website | Oasis Financial official website |
The toll-free number is usually the best first call for application status, payoff questions, document requests, and general account support. A direct corporate line can help if a caller cannot get through on the main customer service channel.
Fax remains relevant in legal funding because attorneys, courts, and medical providers may still exchange signed records that way.
Do not fax Social Security numbers, bank data, or settlement documents unless the number is confirmed from the official source immediately before sending.
Other ways to contact Oasis Financial
- Use the official website’s contact form for non-urgent questions and document routing.
- Check loan agreements or approval emails for a case-specific representative or extension.
- If an attorney is involved, ask counsel to confirm the correct department before sharing case records.
- For mailed correspondence, use the address printed on the latest official statement or contract.
A practical next step is to compare the number on the website, the contract, and any recent email footer. If those do not match, pause and verify through the company’s main website before discussing account details.
This caution matters because legal funding accounts involve sensitive personal and case information. Acting on an outdated or copied number could expose private records or delay urgent paperwork.
Information to have before calling Oasis
Have your file details in front of you before calling Oasis. That shortens the call, reduces verification errors, and helps you compare anything discussed with your signed paperwork.
If the call involves a pending lawsuit or a settlement advance, keep your attorney’s contact details and your contract nearby. Do not rely on memory for payoff amounts, fees, or case status.
| Have this ready | Why it matters |
| Your full name exactly as it appears on the contract or case file | Matching the file name helps the representative locate the correct account. |
| Application, account, or reference number from Oasis paperwork | A reference number is usually the fastest way to pull a record and avoid mixing up similar names. |
| Attorney name, law firm, phone number, and email | Settlement funding companies often need attorney confirmation before discussing case-related details. |
| Case number and court information, if available | That helps confirm the stage of the case and whether documents are missing. |
| Your signed agreement, disclosures, and any payoff letter | You can compare the contract terms with what the representative says on the call. |
| Recent emails, letters, or text notices from Oasis | Current correspondence may show status updates, document requests, or payment instructions. |
| A written list of questions | This helps you ask about funding status, missing documents, payoff amount, and processing time. |
If the call is about an existing obligation, ask for an itemized statement. The key figures to confirm are the amount advanced, fees, and total payoff shown on the written contract or payoff letter.
For identity safety, verify the number before sharing sensitive information. The Federal Trade Commission says an initial fraud alert lasts 1 year and an extended fraud alert lasts 7 years, which matters if you suspect misuse of your personal data.
If you want to review your broader financial file first, the Consumer Financial Protection Bureau says consumers can get free credit reports from the 3 nationwide credit bureaus through AnnualCreditReport.com.
That step can help spot unfamiliar inquiries or contact information.
- Ask the representative for their name and department.
- Write down the date, time, and any promised next step.
- Request copies of anything discussed if it affects money owed or documents required.
- Do not send money or banking details until the contact number matches Oasis paperwork or the official company website.
Caution: Phone discussions are not a substitute for reading the contract. If the numbers on the call do not match your documents, stop and ask for written confirmation before acting.
What Coin Abul independently reviewed
Coin Abul independently reviewed Oasis Financial’s public contact information, corporate disclosures.
And consumer-facing support channels relevant to people searching for an “Oasis loan number.” The review focused on verifiable facts from primary or near-primary sources, not marketing claims or unverified directory listings.
Because phone numbers, hours, and legal entities can change, readers should confirm current details directly through Oasis Financial’s official website, signed paperwork.
Or state business records before sharing personal information or discussing a pending case.
The review checked whether Oasis Financial publicly identifies a customer-service phone line, mailing address, and business background.
It also checked how the company describes its product, since legal funding is not the same as a traditional personal loan and that distinction affects consumer expectations.
| Item reviewed | What was verified | Source |
| Primary phone number | (866) 353-6691 was listed for Oasis Financial | Oasis Financial official website contact page |
| Corporate address | 9525 W. Bryn Mawr Ave, Suite 900, Rosemont, IL 60018 | Oasis Financial official website contact page |
| Product description | Oasis describes its product as “pre-settlement funding” rather than a standard consumer loan | Oasis Financial official website and product pages |
| BBB profile status | BBB lists Oasis Financial with a profile consumers can use to review complaint information | Better Business Bureau business profile for Oasis Financial |
| State corporate filing check | An Illinois business-record search can be used to confirm entity status and registered details | Illinois Secretary of State business services records |
The phone number matters because many people search “Oasis loan number” when they need payoff information, status updates, underwriting questions, or documents for an attorney.
A wrong number can expose private case details to third parties, so using the official contact page is safer than relying on copied listings.
The review also noted a terminology issue.
Pre-settlement funding is commonly structured as non-recourse legal funding, meaning repayment usually depends on case proceeds, but readers should verify the exact contract language in their own agreement because terms differ by transaction and state.
- Official phone and address details were cross-checked against Oasis’s own website first.
- Business-background checks were limited to public records and public complaint portals.
- No customer reviews, approval times, fee amounts, or rates were treated as facts unless a primary source stated them.
- If a caller needs payoff or balance information, the safest source is the signed contract and the company’s official servicing line.
This section does not confirm pricing, approval odds, or legal rights in any state. For those points, readers should check their contract, ask their attorney, and confirm current rules with the relevant state regulator or court-approved source.
When to verify Oasis details first
Verify Oasis details before sharing money, documents, or personal data. That matters most when a call, email, letter, or credit entry looks urgent, unfamiliar, or inconsistent with paperwork already on hand.
Start with the original contract, any funding approval notice, and the phone number printed on official documents.
Then compare that information with the company’s public contact details and any court or attorney records tied to the underlying case.
Verification should come first in several common situations. The trigger usually is speed, pressure, or a mismatch between records. The table below shows when to stop and confirm details before acting.
| Situation | Fact to use | Source | What to verify first |
| A caller says payment is overdue and demands fast action | Debt collectors generally must send validation information within 5 days of the first communication, and consumers generally have 30 days to dispute the debt after getting that notice | Consumer Financial Protection Bureau, summary of the Fair Debt Collection Practices Act | The legal name of the business, account number, mailing address, and whether the notice matches the contract |
| An account appears on a credit report | There are 3 nationwide consumer reporting companies: Equifax, Experian, and TransUnion | Consumer Financial Protection Bureau | Whether the entry lists the correct creditor name, balance, and dates, and whether it belongs to the same lawsuit or funding agreement |
| You are asked to pay through unusual methods | The FTC warns that requests to pay by gift card, wire transfer, cryptocurrency, or payment app are major scam indicators | Federal Trade Commission consumer scam guidance | Whether the payment instruction appears in your signed agreement or on the company’s official website |
Verify details first if the phone number changes from one document to another. Verify first if the email domain differs from prior messages.
Verify first if someone asks for a Social Security number, bank login, or debit card before confirming the account.
Caution: do not rely on a callback number in a suspicious message alone. Use a number from signed paperwork, a state business record, or the company’s official website.
If legal rights or repayment terms are unclear, check the primary contract and ask a qualified attorney or consumer law professional before paying.
- Match the company name exactly, including any “LLC” or “Inc.” suffix.
- Match the funding date and amount to your contract.
- Keep copies of letters, envelopes, emails, and caller IDs.
- Dispute inaccurate reporting with the credit bureau and the furnisher in writing if needed.
Alternatives before taking settlement funding
Settlement funding can be fast, but it is usually expensive. Before using any advance tied to a lawsuit, compare lower-cost options that do not depend on the case outcome and may preserve more of a future settlement.
Start with options that reduce the bill itself or spread payments over time. Then compare borrowing costs using primary-source figures, and confirm terms directly with the provider before signing anything.
| Alternative | Specific fact | Why it may cost less |
| Hospital or doctor payment plan | Nonprofit hospitals must have written financial assistance and emergency medical care policies to keep federal tax-exempt status under IRS section 501(r), according to the Internal Revenue Service. | Reducing or stretching a medical bill can avoid new financing charges altogether. |
| Credit card hardship or 0% APR offer | The average credit card interest rate assessed interest was 22.80% in May 2024, according to the Consumer Financial Protection Bureau. | Even standard card rates can be lower than many legal funding contracts, but missed payments can be costly. |
| Personal loan from a bank or credit union | The average 24-month personal loan rate at commercial banks was 12.33% in February 2025, according to the Federal Reserve. | A fixed-rate installment loan can be cheaper and easier to compare than case-based funding. |
| 401(k) loan | For defined contribution plans, 13% of participants had a plan loan outstanding in 2022, according to the Employee Benefit Research Institute. | Some plans allow borrowing from personal retirement savings, though job loss can trigger fast repayment. |
Medical providers are often the first place to ask. The CFPB has warned that medical bills can contain errors, and dispute rights may apply under federal law.
Ask for an itemized bill, uninsured discount, charity care review, or no-interest payment plan.
If income dropped after an injury, check public benefits. Medicaid, SNAP, or temporary disability programs can reduce pressure without pledging lawsuit proceeds. Eligibility rules differ by state, so verify details with the relevant agency.
Borrowing from family or friends can also be cheaper, but put the terms in writing. State the amount, repayment trigger, and whether repayment depends on winning the case. Clear terms reduce conflict later.
Caution: A lower advertised rate does not always mean a lower total cost. Fees, compounding, missed-payment penalties, tax effects, and retirement-plan rules can materially change the result.
Check the contract and, for legal rights, ask a qualified attorney or financial professional.
Frequently Asked Questions
What is the Oasis loan number for customer service?
Oasis Financial lists 866-353-9765 as its contact number on its official website, OasisFinancial.com.
Before calling, compare the number on the website with any number shown in your contract or recent account notice, because scammers sometimes spoof financial company phone lines.
Is there a different Oasis loan number for applying versus managing an existing account?
Oasis Financial uses the same main phone number, 866-353-9765, on its official contact pages for general communication, according to OasisFinancial.com.
If the matter involves an existing advance, have the reference number from the company’s paperwork ready so the representative can locate the file faster.
Where can a borrower find the correct Oasis loan number safely?
The safest source is the company’s official website, signed account documents, or direct written notices from Oasis Financial.
Do not rely on a number from an ad, social post, or search snippet alone; verify it against the primary source first because a wrong number could expose personal or case information.
What information should be ready before calling the Oasis loan number?
A caller should have the full name on the account, the case or account reference if one was assigned, and any recent correspondence from Oasis Financial.
Avoid giving a Social Security number, bank login, or lawsuit details until the caller confirms the number came from OasisFinancial.com or official account paperwork.
Can someone handle an Oasis account issue without calling the loan number?
Yes. Oasis Financial also provides online contact options through its official website, OasisFinancial.com, which may help with general questions when a phone call is not convenient.
For urgent account-specific issues, the company may still require a phone conversation or written documentation to verify identity and authority.
What should a caller do if the Oasis loan number does not work?
First, recheck the number on OasisFinancial.com and compare it with the latest contract or notice, because contact details can change.
If the number still fails, use the official website’s contact form and keep copies of every message; if money is due or legal rights are involved.
Confirm deadlines directly with the original contract or a qualified attorney rather than relying on this article alone.
Related Reading
- Tribeca Group Review – The Truth You Didn't Know
- Pre Settlement Loans Without A Lawyer
- Is Oasis Financial Legit?
- Pre Settlement Loans Near Me
- Oasis Financial Login
- Behind the Oasis Financial Lawsuit
- Same Day Pre Settlement Loans – What You Need to Know
- Best Pre Settlement Loans
- Lawsuit Loans With Low Interest Rates
- All Blog Guides
- Oasis Financial Contact Us (2025)
- Better Business Bureau: Oasis Financial (2025)
- Consumer Financial Protection Bureau, Consumer Advisory: Considering a lawsuit loan? (2017)
- Federal Trade Commission, Need Cash Fast? Know the Risks of Advance Settlement Funding (2018)
- National Consumer Law Center, The State of Lending: Consumer Litigation Funding (2023)