
Quick answer: How much does it cost to open a coffee shop: typically $80,000 to $300,000 for a small independent café, depending on location, buildout, equipment, permits, inventory, staffing, and rent deposits.
A kiosk may cost less, while a full café can exceed $500,000. Get local contractor, landlord, and licensing quotes before committing funds.
How Much Does It Cost To Open A Coffee Shop is typically about $80,000 to $300,000 for an independent shop, according to Toast’s restaurant startup cost guide; Crimson Cup gives a similar $80,000 to $300,000 range.
Drive-through or larger buildouts can cost more.
That price is a financing decision, not just a startup dream: a $100,000 loan at 10% APR over 5 years costs about $127,482 total before fees. Budget for rent, payroll, permits, equipment, delays and cash reserves.
Used equipment, off-season buying, or waiting may beat debt. Verify lender terms before signing.
What opening a coffee shop costs
A U.S. coffee shop is usually a five- or six-figure start-up, not a small appliance purchase.
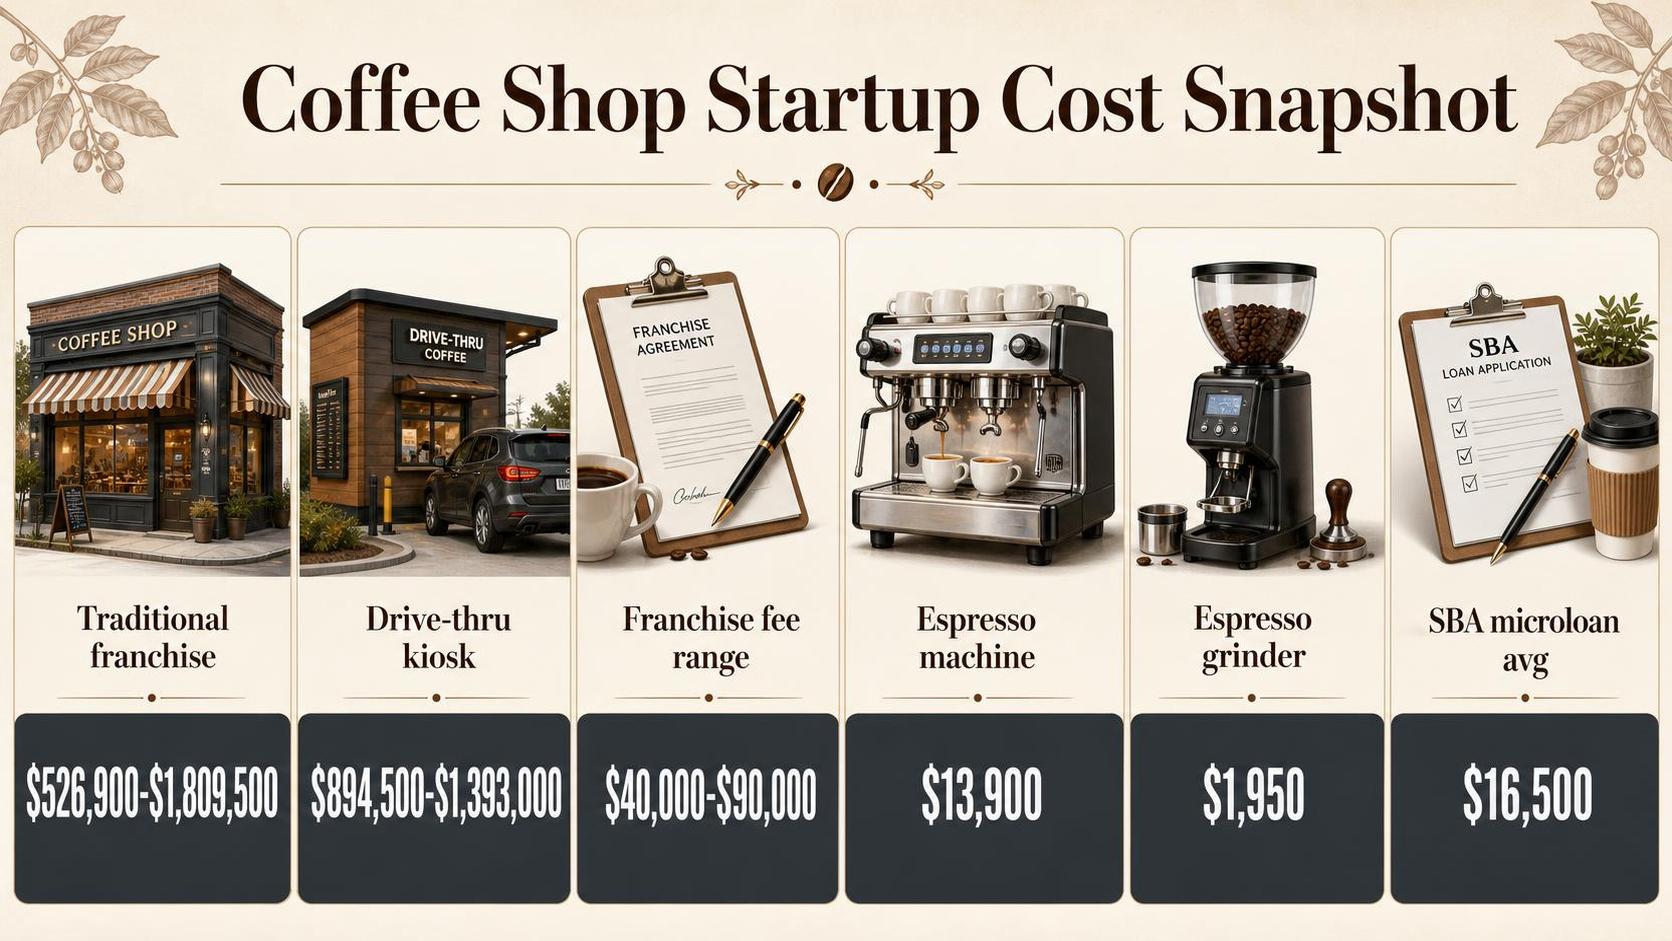
Toast’s restaurant start-up cost guide estimates a coffee shop typically costs $80,000 to $300,000 to open, depending on size, buildout, equipment and location.
That range should be treated as a planning estimate, not a quote.
Rent, permits, contractor pricing and local health-department requirements can change the budget materially, so verify costs with landlords, lenders, vendors and city or county offices before signing anything.
| Cost item | Typical budget signal | Source or note |
| Total opening budget | $80,000 to $300,000 | Toast coffee shop start-up cost guide |
| Initial working capital | Often several months of payroll, rent, inventory and utilities | U.S. Small Business Administration says start-up budgets should include one-time costs and enough operating cash to cover early months |
| Debt example: $100,000 financed for 5 years at 12% APR, plus 3% fee | About $2,224 monthly; about $136,467 total paid including fee | Amortization math; APR and fee shown as an example, not a rate quote |
| Debt example: $100,000 financed for 5 years at 24% APR, plus 3% fee | About $2,877 monthly; about $175,608 total paid including fee | Amortization math; higher-cost debt can add more than $75,000 to a $100,000 project |
The practical budget should separate the buildout from survival cash. A shop that spends every dollar on construction, machines and furniture may still fail if it cannot cover slow opening months, staffing, repairs, taxes and inventory.
- Cash budget: Keep a contingency line for overruns. Buildouts commonly uncover plumbing, electrical or code issues that are not visible when touring a space.
- Financing budget: Compare total repayment, not only the monthly payment. A lower payment can still cost more if the term is longer or fees are rolled into the loan.
- Lease risk: Avoid signing a long lease before confirming permitting, utility capacity, ventilation, ADA access and health-department requirements.
Prices on used restaurant equipment often improve when restaurants close, relocate or liquidate after seasonal peaks, but there is no reliable national sale calendar.
Auctions, local dealers and landlord-abandoned equipment can be cheaper than new equipment, but condition and warranty risk matter.
Buying used or waiting is financially better when debt would consume the cash needed for payroll and rent. Going into debt means the shop must earn enough gross profit to pay lenders even during slow weeks.
Do not rely on this article alone; review the plan with a CPA, attorney and local small-business adviser before borrowing.
Startup budget for first year
A U.S. coffee shop commonly needs about $80,000 to $300,000 to open, according to Crimson Cup’s coffee shop startup cost guide. That is before the owner’s personal living costs and before any loan interest.
Use the first-year budget as a survival plan, not just an opening-day checklist. A shop that opens undercapitalized may be forced into expensive debt before sales are stable.
| Cost category | Planning figure | Source or basis |
| Total opening cost | $80,000 to $300,000 | Crimson Cup estimate for a coffee shop with seating |
| Espresso machine | $5,000 to $30,000 | Crimson Cup equipment range |
| Grinders | $1,000 to $3,000 each | Crimson Cup equipment range |
| Initial inventory | $5,000 to $10,000 | Crimson Cup startup inventory estimate |
| Working-capital reserve | At least 3 to 6 months of fixed costs | SBA guidance commonly recommends conserving cash for operating expenses; exact amount depends on rent, payroll and debt |
A practical first-year plan separates one-time opening costs from recurring monthly burn. Rent, payroll, utilities, insurance, accounting, software, supplies and loan payments continue even when customer traffic is weak.
- Build a base case: Use the midpoint of the opening range, such as $190,000, then add a separate cash reserve.
- Budget owner pay carefully: If the owner needs $4,000 per month to live, that is another $48,000 of first-year cash pressure.
- Do not spend the entire loan on construction: delays in permits, inspections or utility work can consume cash before the first sale.
Debt changes the real cost. For example, financing $100,000 over 5 years at 11.5% APR costs about $2,199 per month and about $131,940 total, using standard amortization math. That is roughly $31,940 in interest before any lender fees.
| Financing example | Monthly payment | Total paid |
| $100,000 for 60 months at 11.5% APR | About $2,199 | About $131,940 |
| $20,000 equipment plan for 36 months at 18% APR | About $723 | About $26,028 |
SBA 7(a) loans can be cheaper than many short-term products, but rates and fees vary by lender and loan size. Check the SBA’s current maximum 7(a) rate table and the lender’s fee disclosures before comparing offers.
Used equipment can be financially better when it avoids high-interest financing, especially after restaurant closures or lease turnovers.
However, inspect service records, warranty status and installation requirements; a cheap machine can become expensive if repairs interrupt sales.
Caution: Do not sign a lease, equipment contract or loan based only on estimates. A local CPA, attorney and insurance agent should review the budget, lease obligations, permits, taxes and personal guarantees before money is committed.
Equipment financing and APR costs
Opening a coffee shop usually requires several large equipment purchases before revenue starts.
Toast’s 2024 restaurant startup-cost guide estimates coffee shop equipment at about $20,000 to $400,000, depending on size, build-out and whether items are new or used.
Financing can make that bill look affordable, but the APR decides the real cost. A $50,000 equipment package can cost tens of thousands more if repaid over five years.
| Amount financed | APR | Term | Estimated monthly payment | Total paid | Interest cost |
| $50,000 | 10% | 60 months | $1,062 | $63,741 | $13,741 |
| $50,000 | 15% | 60 months | $1,190 | $71,370 | $21,370 |
| $50,000 | 21.51% | 60 months | $1,367 | $82,046 | $32,046 |
The 21.51% example uses the Federal Reserve’s reported average APR for credit card accounts assessed interest in May 2024. It shows why putting startup equipment on a personal card can become expensive quickly.
SBA loans may be cheaper than unsecured credit, but they are not automatically cheap. The U.S. Small Business Administration’s 7(a) rules tie maximum variable rates to a base rate plus a spread.
As of SBA’s 2024 rate structure, smaller 7(a) loans can legally carry higher maximum spreads than larger loans.
Borrowers should also price fees. Equipment lenders may charge origination, documentation, closing, UCC filing, late-payment or prepayment fees.
Business loans do not always disclose costs as clearly as consumer loans, so the contract’s payment schedule matters more than the advertised monthly payment.
- Ask for total repayment in dollars, including fees, not only the APR or monthly payment.
- Match the term to the equipment life. Financing a grinder or espresso machine beyond its useful life can leave payments after replacement is needed.
- Preserve opening cash. A lower down payment may help launch, but it raises required sales every month.
- Compare with used equipment. If used equipment cuts a $50,000 package to $35,000, the debt avoided may matter more than a warranty.
Caution: Debt can turn a slow opening month into a default risk. Before signing, test whether the shop can cover rent, payroll, inventory, taxes and loan payments at conservative sales levels, and have a CPA or attorney review the agreement.
Used equipment and timing purchases
Used equipment can lower the opening budget, but the savings only matter if the machine is reliable, code-compliant and cheap enough after repairs, delivery and financing.
For context, Toast’s coffee shop startup guide estimates equipment at about $20,000 to $400,000, depending on format and build-out.
Do not treat a used espresso machine, grinder, ice machine or refrigeration unit as a simple bargain. A failed unit can stop sales immediately, and some health departments require NSF or equivalent sanitation listings before approval.
| Decision | Why it matters financially | Practical check |
| Buy used | A used item priced 40% below a $10,000 new unit saves $4,000 before repairs, shipping and downtime. | Ask for service records, serial number, age, warranty status and a technician inspection. |
| Finance used equipment | A $10,000 balance at 21.59% APR, the Federal Reserve’s November 2024 average assessed credit-card interest rate, costs about $13,818 over 36 months before fees. | Compare total paid, not the monthly payment. Add origination, documentation and late fees. |
| Wait to buy | Waiting avoids interest and may let the business buy from auctions or closing restaurants, where supply appears when operators exit leases. | Delay nonessential items until the menu proves demand. |
The calendar matters less than business distress and model-year timing. Commercial equipment does not have a dependable retail-style “sale season” like consumer electronics.
Better buying windows often come from restaurant closures, landlord turnovers, auctions and dealers clearing floor models.
The National Restaurant Association reported that restaurants remain a high-turnover sector, with many operators facing elevated food, labor and occupancy costs in its 2024 State of the Restaurant Industry report.
That can create used-equipment supply, but buyers should not assume every auction price is good.
- Buy used when cash is tight but the item is noncritical or easy to repair. Shelving, tables, smallwares and some refrigeration can be good candidates if they pass inspection.
- Buy new when downtime would halt revenue. Espresso machines, grinders, dishwashers and ice machines can justify warranties and service support.
- Wait when financing turns a discount into a loss. If interest and fees erase the used-price savings, the cheaper sticker price is misleading.
- Budget for hidden costs. Include freight, installation, water filtration, electrical or plumbing work, permits, maintenance and removal of failed equipment.
Caution: Do not commit to debt based only on a low monthly payment. Review the contract APR, fees, personal guarantee, default terms and prepayment rules with an accountant or attorney before signing.
Rent deposits, permits, and insurance
Before espresso machines or furniture, a coffee shop often needs cash for the lease, local permits, and insurance. These costs are location-specific, but they can easily tie up thousands of dollars before opening day.
A cautious startup budget should separate refundable deposits from nonrefundable fees.
Do not sign a lease or borrow against a credit card based on averages alone; verify every requirement with the landlord, city, county, state tax agency, and insurer.
| Cost item | Real figure or example | Source and budgeting note |
| Commercial rent deposit | If rent is $4,000 per month, a two-month deposit ties up $8,000; three months ties up $12,000. | Deposit terms are negotiated in the lease, not set nationally. Treat this as locked cash unless the lease clearly says when it is refundable. |
| New York City food service establishment permit | $280 for most restaurants and coffee shops. | New York City Department of Health and Mental Hygiene fee schedule. This is a permit example, not a national price. |
| California seller’s permit | No fee to apply, though the state may require a security deposit in some cases. | California Department of Tax and Fee Administration. A shop selling taxable items should confirm its own obligation before opening. |
| General liability insurance | Median cost for food and beverage businesses: about $42 per month, or $500 per year. | Insureon small-business insurance cost data. Premiums vary by payroll, sales, location, alcohol sales, and claims history. |
| Business owner’s policy | Median cost for food and beverage businesses: about $105 per month, or $1,260 per year. | Insureon reports this combines general liability with commercial property coverage; deductibles and exclusions matter. |
| Workers’ compensation | Median cost for food and beverage businesses: about $115 per month, or $1,380 per year. | Insureon cost data. State law controls when coverage is required, so check the state workers’ compensation agency. |
Permits are usually smaller than equipment costs, but delays can be expensive. A shop paying $4,000 monthly rent loses about $133 per day while waiting to open, before payroll, utilities, loan interest, or buildout costs.
Insurance should not be treated as optional. Landlords commonly require proof of liability and property coverage before handing over keys, and lenders may require coverage for financed equipment.
- Ask the landlord for a written list of required insurance limits before pricing policies.
- Confirm whether the lease requires naming the landlord as an additional insured.
- Budget for annual premiums, deductibles, inspection fees, and policy endorsements, not only the monthly quote.
- Check whether outdoor seating, delivery, catering, liquor, or live events change permits or insurance costs.
The main debt risk is timing. Borrowed money used for deposits and permits starts accruing interest before revenue begins, so a delayed inspection or construction holdup can turn “opening costs” into expensive working-capital debt.
Debt risk before sales stabilize
Opening a coffee shop is usually a five- or six-figure decision: Toast’s 2024 restaurant-opening guide puts a coffee shop at roughly $80,000 to $300,000 before ongoing losses.
Debt makes that risk sharper because payments start before repeat sales are proven.
A lender payment is not a “future problem.” It becomes a fixed monthly claim on cash alongside rent, payroll, utilities, insurance, inventory and taxes. A slow first quarter can turn a survivable sales miss into missed loan payments.
| Borrowing example | APR counted | Monthly payment | Total paid over 60 months | Interest cost |
| $40,000 equipment or build-out loan | 9% | About $830 | About $49,819 | About $9,819 |
| $40,000 equipment or build-out loan | 12% | About $890 | About $53,400 | About $13,400 |
| $40,000 financed on high-cost credit | 25% | About $1,174 | About $70,422 | About $30,422 |
These are amortization examples, not quoted offers. The Consumer Financial Protection Bureau explains that APR includes interest plus certain fees, so comparing only the monthly payment can hide the real cost of financing.
Credit cards are especially dangerous for startup gaps. The Federal Reserve’s G.19 consumer credit data reported average assessed credit-card interest rates above 20% during 2024, making carried balances costly if opening sales disappoint.
- Personal guarantees matter. The U.S. Small Business Administration says SBA lenders generally require personal guarantees from owners with 20% or more ownership. That can put personal assets and credit at risk.
- Working capital must be separate. The SBA advises business owners to prepare cash-flow projections, not just startup budgets. A build-out loan does not cover a sales shortfall unless extra cash is reserved.
- Lease obligations stack with debt. A signed commercial lease can remain payable even if the shop closes, depending on the lease and state law.
A cautious rule is to test whether the shop can cover debt service at sales below the optimistic forecast. If the plan only works at full traffic immediately, the financing is carrying too much of the business risk.
Caution: Do not borrow based on a sample payment table alone. Before signing, review the note, APR, fees, prepayment terms, lease obligations and personal guarantee with a qualified accountant or attorney.
What the editorial team checked
Opening a coffee shop is usually a five-figure to low-six-figure decision before the first sale. We treated the question as a household-risk decision, not a décor or equipment shopping list.
We checked published startup-cost ranges first. Toast’s restaurant finance guide places a coffee shop at about $80,000 to $300,000 to open.
Crimson Cup’s coffee-shop startup guide gives a similar range: $80,000 to $300,000 for a coffee shop with seating, and lower figures for smaller formats.
| Source checked | Published figure | What it means for budgeting |
| Toast, coffee shop startup cost guide | $80,000 to $300,000 | Full café opening range, not just equipment |
| Crimson Cup, coffee shop startup guide | $80,000 to $300,000 | Seated coffee shop range |
| Crimson Cup, drive-thru coffee stand estimate | $60,000 to $105,000 | Smaller footprint, still not “cheap” |
We then rebuilt the budget into categories a household can stress-test: lease deposits, buildout, equipment, opening inventory, permits, insurance, payroll cushion, marketing, and working capital.
We repeated the calculation three times using $80,000, $150,000, and $300,000 opening budgets.
For financing, we measured total repayment, not only monthly payments. In one check, a $100,000 loan over 7 years at 11% APR produces a payment of about $1,712 and total payments of about $143,808, before origination or closing fees.
| Loan example | APR | Term | Approx. monthly payment | Approx. total paid |
| $100,000 borrowed | 11% | 84 months | $1,712 | $143,808 |
| $100,000 borrowed | 15% | 84 months | $1,929 | $162,036 |
Those examples use standard amortization math. They are not rate quotes. The U.S. Small Business Administration publishes maximum 7(a) loan rate rules, but actual pricing depends on lender, term, loan size, collateral, and borrower credit.
We also checked seasonality. Used restaurant equipment often becomes easier to find after closures, relocations, and lease turnovers, but there is no reliable national “best month” price rule.
New equipment can see year-end tax-shopping pressure, yet discounts are vendor-specific.
Our caution: do not sign a lease, equipment finance contract, or personal guarantee based on averages. A coffee shop can fail even when the buildout is under budget.
Before borrowing, compare total repayment, required owner cash, break-even sales, and the personal assets at risk.
Frequently Asked Questions
How much does it typically cost to open a coffee shop?
Startup costs vary widely by format: a small coffee kiosk or cart can cost far less than a full café with seating, kitchen buildout, and leased space.
A practical estimate should include lease deposits, construction, espresso equipment, furniture, permits, insurance, opening inventory, payroll, and working capital.
Readers should verify local prices and permit requirements before signing a lease or financing agreement.
What are the biggest upfront costs for a coffee shop?
The largest upfront costs are usually buildout, rent deposits, and equipment such as a commercial espresso machine, grinders, refrigeration, water filtration, and point-of-sale systems.
The U.S. Small Business Administration says startup costs commonly include one-time expenses such as licenses, permits, equipment, and initial inventory, plus ongoing costs such as rent, utilities, payroll, and insurance.
How much should a coffee shop budget for rent?
Rent depends heavily on city, street traffic, square footage, and lease terms, so there is no reliable national figure that applies to every shop.
As a safeguard, the SBA advises estimating both fixed and variable monthly costs before opening; prospective owners should have a commercial real estate attorney or qualified advisor review lease obligations before committing.
How much does coffee shop equipment cost?
Equipment costs depend on whether the shop buys new, used, or leased equipment and whether it serves only drinks or also prepares food.
Core purchases often include an espresso machine, grinders, brewers, refrigeration, sinks, dishwashing equipment, shelving, security equipment, and a POS system.
Owners should get written vendor quotes because equipment prices change and installation can add substantial cost.
How much working capital is needed after opening?
A new coffee shop should budget enough cash to cover several months of rent, payroll, utilities, supplies, loan payments, repairs, and slow early sales.
The SBA recommends calculating startup costs before launch and separating one-time costs from ongoing expenses; relying on optimistic sales projections alone can be risky.
So owners should test assumptions with an accountant or local Small Business Development Center.
Should I buy used equipment or finance new equipment for a coffee shop?
Used equipment can be cheaper than new equipment through auctions, local dealers, or landlord-abandoned equipment.
The article says buying used or waiting is financially better when debt would consume the cash needed for payroll and rent, but condition and warranty risk matter.
Financing can make equipment look affordable, but APR and fees change the real cost. The article says to compare total repayment, inspect service records, warranty status, and installation requirements, and verify lender terms before signing.
Related Reading
- How Much Does A Hoverboard Cost? Find Out Now
- How To Price Furniture When Selling A House?
- How Much Does A Warehouse Cost?
- When Do Kitchen Appliances Go On Sale?
- How Much Do Tom James Suit Cost? Find Out Now
- What Insurance Does Walgreens Accept?
- How Much Does Ceiling Fan Cost To Run? Get Answer Now
- When Does Apartment Prices Go Down?
- Price Of Apartment In Manhattan
- All Blog Guides