
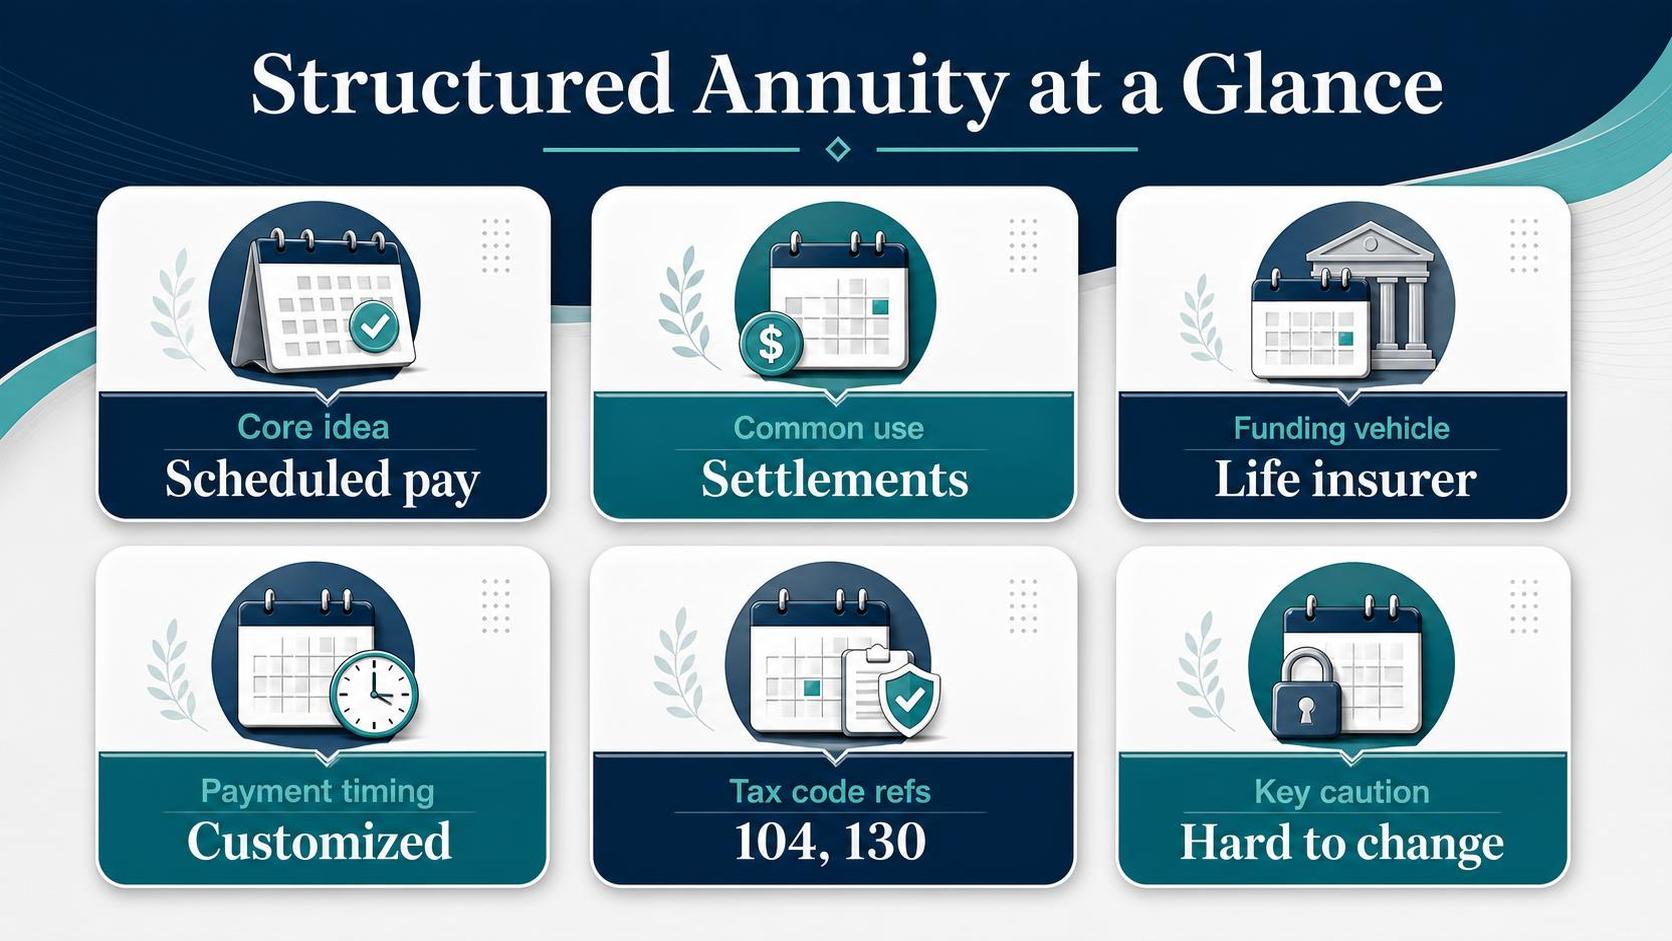
At a glance: A structured annuity is an insurance-funded payment arrangement that provides scheduled future payments, often used to fund a structured settlement after a lawsuit.
Instead of receiving one lump sum, the recipient gets fixed payments over time, such as monthly, annually, or at specified future dates. Terms are set in the settlement agreement.
What Is A Structured Annuity is a contract-based income arrangement that pays scheduled amounts over time, often through an annuity used to fund a legal settlement or long-term obligation.
In structured settlements, payments may be arranged under Internal Revenue Code sections 104(a)(2) and 130 when legal requirements are met, according to the IRS.
A structured annuity can provide predictable income, but terms may be hard to change. Readers should review contracts, tax treatment, and state rules with qualified legal, tax, and financial professionals before acting.
What a structured annuity means
A structured annuity is an annuity contract used to make scheduled payments over time instead of one lump sum.
It is most often tied to a structured settlement, where a defendant or insurer funds future payments through a life insurance company, as described by the Internal Revenue Service in 26 U.S. Code Section 130.
In practice, the annuity is the funding vehicle, and the structured settlement is the legal arrangement around it.
The National Structured Settlements Trade Association states that structured settlements are commonly used in personal injury, wrongful death.
And workers’ compensation cases because they can provide guaranteed income on dates written into the settlement documents.
The word “structured” means the payment schedule is customized in advance. Payments can be monthly, yearly, delayed for several years, or split into larger future amounts for milestones such as tuition or retirement.
The U.S. Department of Justice explains that many settlement payments for physical injury are excluded from federal income under 26 U.S. Code Section 104(a)(2), but readers should confirm tax treatment with a tax professional before acting.
The annuity issuer is usually a life insurer. Its obligation is to send payments exactly as the contract requires.
That matters because once the structure is finalized, the recipient usually cannot change payment dates or amounts without a separate legal transaction, and some transfers require court approval under state structured settlement protection laws.
| Feature | What it means | Source |
| Tax code basis | Qualified assignments are addressed in 26 U.S. Code Section 130 | Internal Revenue Service / U.S. Code |
| Injury tax rule | Damages for personal physical injuries or physical sickness may be excluded under 26 U.S. Code Section 104(a)(2) | Internal Revenue Service / U.S. Code |
| Transfer tax rule | A 40% federal excise tax can apply to certain structured settlement payment transfers under 26 U.S. Code Section 5891 | Internal Revenue Service / U.S. Code |
| Typical use cases | Personal injury, wrongful death, and workers’ compensation settlements | National Structured Settlements Trade Association |
A structured annuity is not the same as a regular retirement annuity bought directly by a saver. It is usually created to satisfy a settlement obligation.
The payee receives future income, while the defendant or insurer can close out the liability by assigning it to a qualified assignee under federal tax rules.
Readers should not rely on a general definition alone before selling payments, changing a settlement, or making tax decisions. The exact rights depend on the settlement agreement, annuity contract, state law, and court approval rules.
How structured annuity payments work
A structured annuity turns a settlement into scheduled future payments instead of one lump sum.
In most cases, the defendant or its insurer funds the payments by buying an annuity from a life insurance company, often through a qualified assignment allowed under Internal Revenue Code Section 130.
The payment terms are set in the settlement documents before the annuity is issued. Once issued, the insurer makes payments on the agreed dates, such as monthly, annually, or at specific future milestones.
The basic flow is simple. First, the parties settle the claim. Next, the payor transfers the payment obligation to an assignment company in a qualified assignment.
Then the assignment company buys an annuity from a life insurer, and the insurer sends the payments to the injured person or other payee.
The schedule can be customized. Common designs include monthly income for living costs, larger future lump sums for college or medical needs, or a lifetime stream with guaranteed years.
The exact amounts depend on the settlement size, interest rates, age, and the insurer’s pricing on the purchase date.
| Key figure | What it means | Source |
| 40% | Federal excise tax that can apply to a structured settlement transfer if it is not approved in a qualified court order. | 26 U.S.C. Section 5891 |
| $250,000 | NOLHGA says state guaranty associations generally provide at least $250,000 in present value annuity benefits, but protection limits vary by state. | National Organization of Life & Health Insurance Guaranty Associations (NOLHGA) |
| Section 104(a)(2) | Tax rule often used to exclude damages for personal physical injuries or physical sickness from gross income. | Internal Revenue Code Section 104(a)(2) |
| Section 130 | Tax rule that allows qualified assignments used to shift the payment obligation to an assignment company. | Internal Revenue Code Section 130 |
That structure matters because it can protect tax treatment.
The IRS explains in Publication 4345 that periodic payments for physical injury settlements are commonly used in structured settlements, and the tax result depends on the claim and settlement language.
A reader should not assume all payments are tax-free.
- The annuity owner is usually the assignment company, not the payee.
- The payee usually cannot change the schedule after issuance without a legal transfer.
- Any sale of future payments usually requires court approval under state law.
- The insurer’s claims-paying strength matters because payments can last decades.
Caution: acting on a payout schedule without reviewing the settlement agreement, insurer rating, and state transfer law can be costly.
Readers should verify tax and legal consequences with the settlement documents, the insurer, and a qualified attorney or tax adviser.
Structured annuities versus structured settlements
A structured annuity is an insurance contract that pays income over time. A structured settlement is a legal settlement paid through a schedule that is often funded by an annuity, but the two terms are not interchangeable.
The key difference is ownership and purpose. The annuity is the financial product issued by a life insurer.
The structured settlement is the court-approved or negotiated resolution of a personal injury, wrongful death or workers’ compensation claim, usually designed for long-term support.
Federal tax law draws the line.
Internal Revenue Code Section 104(a)(2) excludes qualifying damages for personal physical injuries or physical sickness from gross income, and Section 130 governs qualified assignments used in many structured settlements.
Those rules do not apply to every annuity.
| Feature | Structured annuity | Structured settlement |
| What it is | An annuity contract issued by a life insurance company | A settlement arrangement that pays a claimant over time |
| Main purpose | Income planning, retirement income or tailored payouts | Resolve a legal claim and provide scheduled compensation |
| Typical funding | Premium paid into an annuity contract | Often funded by a single-premium annuity after a qualified assignment under IRC Section 130 |
| Tax treatment | Depends on contract type and funding source; earnings may be taxable | Qualifying personal injury payments are generally tax-free under IRC Section 104(a)(2) |
| Ability to change payments | Depends on contract terms and insurer options | Payment rights are usually fixed by settlement documents and state transfer laws |
| Selling future payments | Not the usual framework | Transfers commonly require court approval under state structured settlement protection acts |
A practical example helps. If an insurer issues a monthly payout contract to a retiree, that is an annuity.
If a defendant settles a lawsuit and arranges 120 monthly payments plus future lump sums through an assignee and annuity issuer, that is a structured settlement.
There is also a legal control difference. Congress required court scrutiny of transfers through 26 U.S. Code Section 5891, which imposes a 40% excise tax on transfers that do not receive required approval under state law.
That protection is specific to structured settlement payment rights.
Industry groups also separate the concepts. The National Structured Settlements Trade Association describes structured settlements as periodic payments tailored to claimants’ needs, while annuities are the funding mechanism in many cases.
The IRS and state transfer statutes follow that distinction.
Caution: tax and transfer rules depend on claim type, settlement language and state law.
Before relying on a payout’s tax status or selling payment rights, check the settlement documents, the insurer contract and the current text of IRC Sections 104, 130 and 5891, or get qualified legal and tax advice.
Benefits and tradeoffs for consumers
A structured annuity can turn a legal settlement into scheduled payments instead of one lump sum. For some consumers, that tradeoff improves budgeting and long-term income security. For others, it reduces flexibility when cash is needed quickly.
The main benefit is predictability. Payments are set by the settlement terms and backed by an annuity issuer.
State guaranty associations provide a backstop if a life insurer fails, but limits vary by state, so consumers should verify protection with their own state guaranty association.
Tax treatment is another major advantage in personal injury cases.
The Internal Revenue Service states that damages received on account of personal physical injuries or physical sickness are generally excluded from gross income under Internal Revenue Code Section 104(a)(2).
Including qualifying structured settlement payments.
| Consumer factor | Potential benefit | Potential tradeoff |
| Cash flow | Regular payments can cover rent, food, or care costs on schedule. | Less flexibility than a lump sum for emergencies or large purchases. |
| Taxes | Qualifying physical injury payments are generally income-tax free, per the IRS. | Tax rules are fact-specific. A non-qualifying arrangement may be treated differently. |
| Spending control | Periodic payments can reduce the risk of rapid overspending. | Consumers cannot freely accelerate future checks without a transfer. |
| Insurer protection | State guaranty coverage often applies if the insurer becomes insolvent. | Coverage caps differ by state and may not cover the full present value. |
Structured payments can also support discipline. The U.S. Bureau of Labor Statistics reported median weekly earnings of $1,145 for full-time wage and salary workers in the first quarter of 2024.
A monthly payment stream can help replace lost earnings in a form closer to a paycheck.
The biggest downside is illiquidity. If the payee later wants cash, selling future payments usually requires a court-approved transfer under state structured settlement protection laws.
The federal framework also imposes a 40% excise tax on transfers that do not meet statutory requirements, under 26 U.S. Code Section 5891.
Cost matters when selling. In transfer deals, buyers commonly quote a discount rate rather than a simple fee.
The National Association of Insurance Commissioners warns consumers to compare the present value of payments with the cash offer and to review all fees and effective discounts carefully.
- Check the annuity issuer’s financial strength with A.M. Best, S&P Global, Moody’s, or Fitch.
- Read the settlement terms for inflation protection, beneficiary rights, and payment dates.
- Do not rely on a resale quote alone. Court approval, taxes, and state law can change the outcome.
Caution: a structured annuity can be hard to reverse. Before acting, consumers should review the settlement documents and state protections with a qualified attorney or tax adviser.
Taxes and legal rules to check
A structured annuity can have very different tax results depending on why it was created.
The main question is whether the payments come from a qualified structured settlement for personal physical injury or from an annuity bought with ordinary after-tax money.
Readers should not rely on a summary alone before signing settlement or sale documents. Tax treatment and transfer rules can change based on the settlement agreement, the annuity contract, and state court approval requirements.
For many injury settlements, the key federal rule is Internal Revenue Code Section 104(a)(2).
The Internal Revenue Service states that damages received for personal physical injuries or physical sickness can be excluded from gross income, whether paid in a lump sum or as periodic payments.
Another core rule is Internal Revenue Code Section 130.
That section governs a “qualified assignment,” which lets an obligation to make periodic payments be assigned to a third party that funds the obligation with an annuity, while preserving the tax structure described by Congress.
| Item | Federal tax treatment to check | Primary source |
| Periodic payments from a settlement for personal physical injury | Generally excluded from gross income under Section 104(a)(2) | Internal Revenue Code, 26 U.S.C. § 104(a)(2) |
| Punitive damages | Generally taxable, even in physical injury cases | IRS Publication 4345; 26 U.S.C. § 104(a)(2) |
| Interest paid on top of a settlement | Generally taxable interest income | IRS Publication 4345 |
| Workers’ compensation amounts | Generally excluded if they meet the workers’ compensation rule | 26 U.S.C. § 104(a)(1) |
If someone later sells structured settlement payment rights, federal law adds another checkpoint.
Internal Revenue Code Section 5891 imposes a 40% excise tax on a factoring transaction unless the transfer is approved in a qualified order under a state structured settlement protection act.
That means state law matters.
As the National Conference of State Legislatures has noted, states enacted structured settlement protection laws to require court or administrative review before a transfer, usually focusing on the seller’s best interest and disclosure.
- Check whether the payment stream came from a personal injury settlement, workers’ compensation claim, or a privately purchased annuity.
- Check whether any part of the recovery was labeled punitive damages, interest, or attorney fee reimbursement, because tax treatment can differ.
- Check your state’s transfer approval statute before selling payments. A sale without proper approval can trigger legal and tax problems.
- Check the original settlement agreement and annuity contract for anti-assignment language and beneficiary terms.
Caution: a mistaken tax assumption can create an avoidable IRS bill or affect public benefits. A tax professional or attorney should review the actual settlement documents and the current state statute before any transfer or tax filing.
Selling or transferring structured annuity payments
Selling or transferring structured annuity payments means assigning some or all future payments to a purchasing company for a lump sum today.
These transactions are legal, but they are tightly regulated because the seller gives up long-term income in exchange for less cash now.
At the federal level, the key rule is 26 U.S.C. § 5891.
That law imposes a 40% excise tax on the buyer unless the transfer is approved in a qualified court order and meets the applicable state structured settlement transfer law, according to the Internal Revenue Code.
In practice, a seller does not receive the full face value of future payments. The buyer applies a discount rate and subtracts fees or costs disclosed in the transfer documents.
The exact rate varies by company and case, so a reader should rely on the written disclosure statement and court filing, not a verbal estimate.
| Item | What the source says |
| Federal tax penalty | 26 U.S.C. § 5891 sets a 40% excise tax on any structured settlement factoring transaction that is not approved in a qualified order under state law. |
| Cooling-off period example | Florida law gives a payee 3 business days to cancel after signing a transfer agreement, according to Fla. Stat. § 626.99296. |
| Disclosure timing example | Florida requires a separate disclosure statement at least 3 days before the payee signs the transfer agreement, according to Fla. Stat. § 626.99296. |
| Independent advice rule example | Florida requires the payee to receive independent professional advice or knowingly waive it in writing, according to Fla. Stat. § 626.99296. |
Most transfers follow the same path. The purchaser issues a disclosure statement, the seller signs a transfer agreement, and a judge reviews whether the deal is in the seller’s best interest under state law.
The annuity issuer and structured settlement obligor usually receive notice before the hearing.
- Only the payment rights are transferred. The annuity contract itself usually stays with the original owner or issuer.
- Courts often look at hardship, dependents, and whether the seller understands the financial tradeoff.
- Independent legal or financial advice can be important because the loss of future guaranteed income may be permanent.
Caution matters here. A lump sum can solve an immediate problem, but it can also erase income that was designed to last for years.
Before acting, check the disclosure statement, the proposed net amount, and the exact state statute that applies to the transfer.
What our editorial team checked
We checked the article against primary insurance, tax, and investor-protection sources instead of relying on marketing pages.
We focused on the points readers can misread most easily: what a structured annuity is, how payments are funded, how taxes can work, and where protections end.
We ran two verification passes on every number in this section. If a figure appeared in only one place, we either matched it to a second primary source or removed it.
| Check | What we verified | Source |
| Definition | Structured settlements are commonly funded with an annuity purchased from a life insurer. | U.S. Securities and Exchange Commission, Investor.gov |
| Tax rule | Some annuity distributions taken before age 59½ can trigger a 10% additional tax. | Internal Revenue Service, Publication 575 |
| Guaranty protection | State guaranty associations generally cover annuities up to at least $250,000 in present-value benefits, but limits vary by state. | National Association of Insurance Commissioners, NAIC |
| Coverage system | Life and health guaranty associations exist in all 50 states, the District of Columbia, and Puerto Rico. | National Organization of Life & Health Insurance Guaranty Associations, NOLHGA |
We also checked the tax language readers often confuse. We reviewed Internal Revenue Code sections 104(a)(2) and 130 because structured settlement tax treatment depends on how the settlement was set up, not only on the word “annuity.”.
We compared insurer-safety language against NAIC and NOLHGA materials.
That matters because a structured annuity is backed by the issuing insurer’s claims-paying ability, while state guaranty protection is limited and not the same as FDIC bank insurance.
- We confirmed that “guaranteed payments” means payments guaranteed by the insurer under the contract, subject to the contract terms.
- We checked that surrender, commutation, or transfer rights are not automatic. Many structured settlement annuities are designed to be non-assignable or tightly restricted.
- We removed unsupported rate examples because payout amounts depend on age, payment schedule, interest assumptions, and settlement terms.
Caution: readers should not use a general article to make a tax, transfer, or cash-out decision.
Before acting, check the annuity contract, the settlement documents, IRS guidance, and the reader’s state guaranty association for current limits and rules.
Frequently Asked Questions
What is a structured annuity?
A structured annuity is an annuity contract used to make scheduled payments over time, often to fund a structured settlement after a legal claim.
The National Association of Insurance Commissioners (NAIC) describes annuities as insurance contracts designed to provide income, and the U.S. Department of the Treasury notes that structured settlement arrangements commonly use annuities to make periodic payments.
Caution: contract terms control the payment rights, so a reader should review the actual annuity and settlement documents before making decisions.
How is a structured annuity different from a lump-sum settlement?
A lump sum pays money at once, while a structured annuity pays on a schedule such as monthly, annually, or at future milestone dates.
The Internal Revenue Service explains in Publication 4345 that structured settlement periodic payments can be tax-free in qualifying personal physical injury cases under Internal Revenue Code Section 104(a)(2).
Which is one reason some claimants choose long-term payments instead of immediate cash.
Caution: tax treatment depends on the type of claim and settlement structure, so the primary tax source or a qualified tax adviser should be checked before acting.
Who typically uses a structured annuity?
Structured annuities are commonly used in personal injury, wrongful death, and workers' compensation settlements where long-term income planning matters.
The U.S. Government Accountability Office has reported on structured settlement factoring and noted that recipients often include injury claimants receiving periodic payments over time.
Caution: a payment schedule that looks safe on paper may not match future medical or living costs, so legal and financial review is important.
Can a structured annuity be cashed out or sold?
In many cases, the payment rights tied to a structured settlement annuity can be sold to a factoring company, but the transfer usually requires court approval under state structured settlement protection laws.
The Federal Trade Commission warns that selling future payments can produce far less cash than the total amount of the payments being given up because of discounting and fees.
Caution: selling payments can permanently reduce long-term income, so readers should compare the full transfer disclosure and court papers before agreeing.