
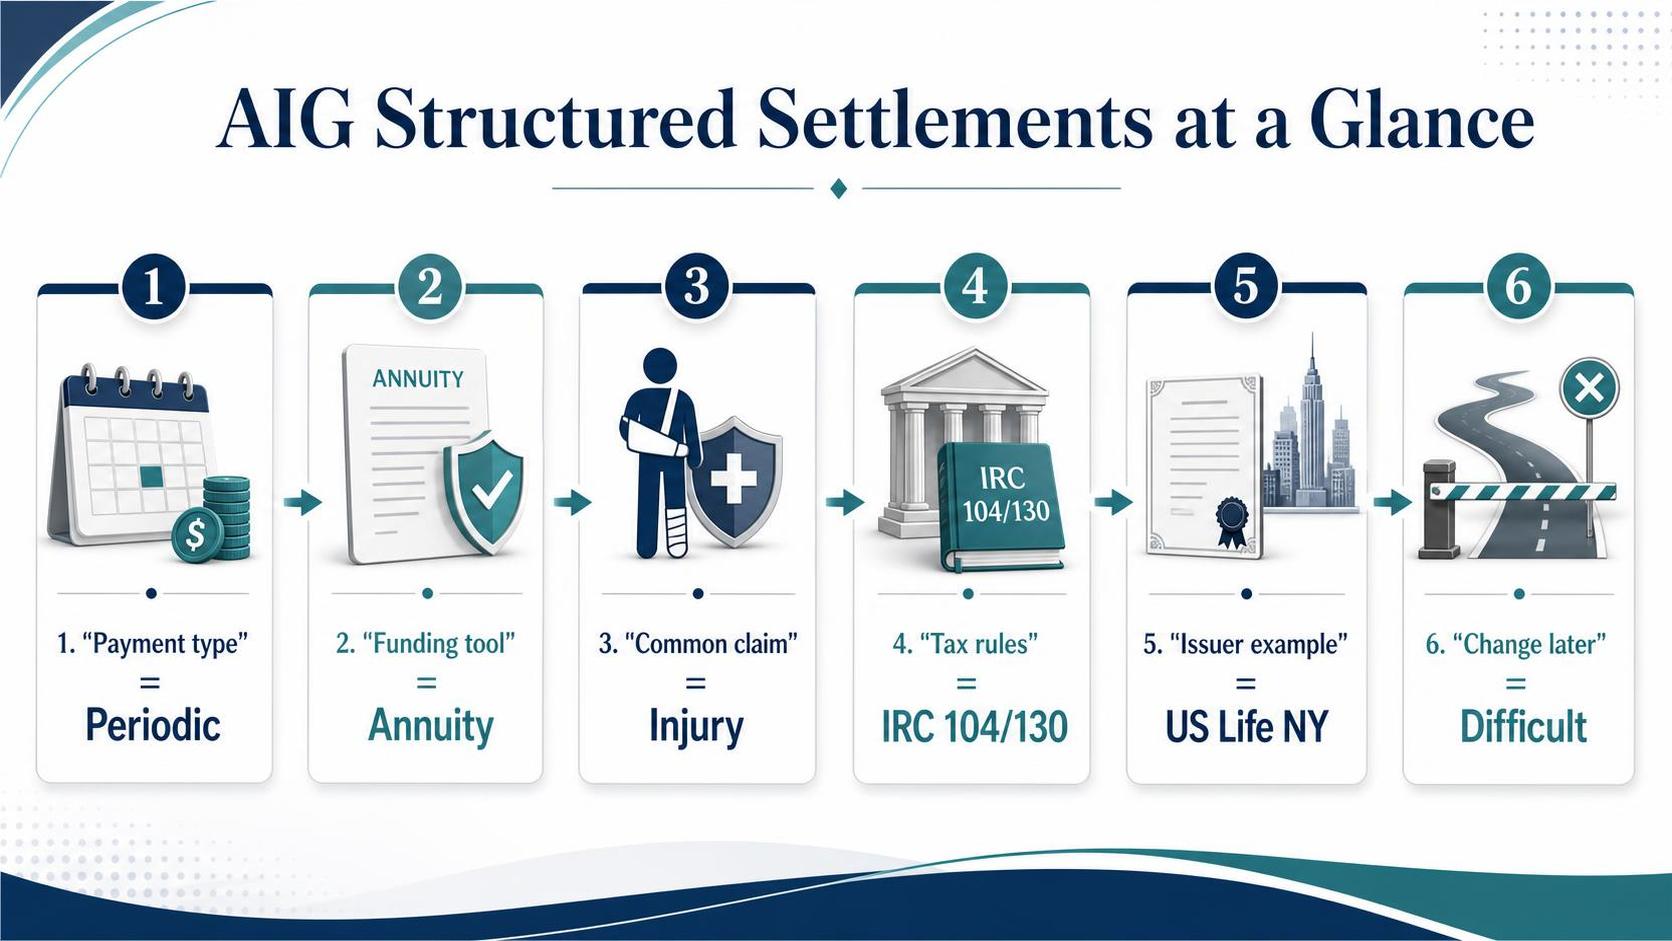
The short answer: AIG Structured Settlements are periodic payment arrangements typically funded through annuities issued by AIG-affiliated life insurers to resolve personal injury or similar claims.
They provide scheduled, often tax-advantaged payments instead of one lump sum. Terms depend on the settlement agreement, insurer, court approval, and applicable federal and state law.
AIG Structured Settlements are periodic payment arrangements backed by annuities issued through AIG-affiliated insurers to fund injury, legal, or insurance claim obligations over time.
AIG’s life and retirement businesses have historically issued annuity products used in structured settlement markets, while payment terms depend on the settlement contract, court approval, and insurer obligations.
Readers should verify current issuer details, ratings, tax treatment, and transfer rules through AIG filings, state insurance regulators, and qualified legal or tax counsel before relying on any payment decision.
How AIG structured settlements work
AIG structured settlements typically use a life insurance company within the AIG group to issue an annuity that funds future payments.
In practice, the defendant or insurer pays a single premium, and the annuity issuer then makes the scheduled payments to the injured person or claimant.
The basic framework comes from federal tax law.
Internal Revenue Code Section 130 governs qualified assignments, and Sections 104(a)(2) and 130 are the provisions most often cited in structured-settlement transactions involving personal injury claims.
In a typical case, the parties settle a lawsuit, agree on the payment schedule, and assign the payment obligation to a qualified assignment company.
That assignee buys an annuity from an AIG-affiliated insurer, and the annuity is designed to match the settlement terms.
AIG’s structured settlement business has historically used insurers such as The United States Life Insurance Company in the City of New York.
Financial strength matters because payments may continue for decades, so readers should verify the exact issuing company named in the settlement documents before relying on any description.
| Item | Fact | Source |
| Federal tax rule for damages | IRC Section 104(a)(2) | Internal Revenue Service, U.S. Code |
| Qualified assignment rule | IRC Section 130 | Internal Revenue Service, U.S. Code |
| AIG group insurer often cited for structured settlements | The United States Life Insurance Company in the City of New York | AIG annuity and structured settlement materials; New York Department of Financial Services filings |
| AIG long-term issuer credit rating | A- | S&P Global Ratings, American International Group, Inc. ratings profile |
| AIG financial strength rating | A | A.M. Best ratings for key AIG life/insurance entities |
| AIG long-term issuer rating | A2 | Moody’s ratings for American International Group, Inc. |
Payment design is flexible. A settlement can provide one lump sum at a future date, monthly income, annual increasing payments, or a mix of guaranteed payments and life-contingent payments.
The exact amounts depend on pricing when the annuity is purchased and on the terms negotiated in the release.
- The claimant and settling parties decide the payment schedule before the settlement is finalized.
- The premium is paid once, at settlement, to purchase the annuity.
- The annuity issuer sends payments according to the contract schedule.
- Changing the schedule later is usually difficult or impossible without a separate transfer process.
Caution matters here. Tax treatment, creditor protection, and transfer rights can change by case and state law.
Do not sign settlement papers or sell payment rights based on a general article alone; confirm the issuer, ratings, and legal terms in the original documents and with a qualified attorney or tax adviser.
AIG annuity issuers and payment guarantees
AIG structured settlement payments are backed by the specific life insurer that issued the annuity contract, not by the parent company’s general brand alone.
For most U.S. structured settlements, that issuer is American General Life Insurance Company, an AIG subsidiary licensed in all 50 states and the District of Columbia, according to AIG’s company profile.
The core guarantee is contractual. The issuing insurer promises the scheduled payments, and its claims-paying ability is the first source of protection.
AIG states in its annuity materials that guarantees are backed by the claims-paying ability of the issuing insurance company.
For AIG, the main issuer to know is American General Life Insurance Company.
The company was organized in 1960, is domiciled in Texas, and reported admitted assets of $101.6 billion, liabilities of $94.6 billion, and capital and surplus of $7.0 billion as of December 31, 2024, according to its NAIC statutory filing summary.
| Issuer / measure | Figure | Source |
| American General Life Insurance Company founded | 1960 | AIG company profile |
| Licensed jurisdictions | 50 states + DC | AIG company profile |
| Admitted assets | $101.6 billion | NAIC, 2024 statutory filing summary |
| Liabilities | $94.6 billion | NAIC, 2024 statutory filing summary |
| Capital and surplus | $7.0 billion | NAIC, 2024 statutory filing summary |
Credit ratings are another check on payment strength.
As of 2024-2025 published insurer rating pages, American General Life Insurance Company was rated A by AM Best, A2 by Moody’s, A+ by S&P Global Ratings, and A+ by Fitch Ratings.
Those ratings are opinions, not guarantees, and they can change.
| Agency | Financial strength rating | Source |
| AM Best | A | AM Best rating report / AIG ratings page |
| Moody’s | A2 | Moody’s / AIG ratings page |
| S&P Global Ratings | A+ | S&P / AIG ratings page |
| Fitch Ratings | A+ | Fitch / AIG ratings page |
If an issuer fails, state life and health insurance guaranty associations may provide a backstop, but limits depend on state law.
The National Organization of Life & Health Insurance Guaranty Associations says annuity protection is typically at least $250,000 in present-value benefits, though some states set higher limits.
- Coverage is state-based, not federal, according to NOLHGA.
- Protection usually applies only if the insurer becomes insolvent, according to state guaranty association rules.
- Limits vary by state and residency status. Check the guaranty association in the payee’s state before relying on any number.
Caution: do not assume “AIG” alone answers the safety question.
Confirm the exact issuing company on the settlement documents, review its current ratings, and verify guaranty-association limits with the relevant state association or insurance department.
What AIG settlement documents should show
An AIG structured settlement file should show the payee, the payment stream, the company legally obligated to pay, and the annuity issuer if one was used.
The goal is to confirm who owes the money, when each payment is due, and whether tax treatment and transfer limits were documented correctly.
Readers should not rely on memory or marketing summaries.
Before signing, compare the final settlement agreement, any qualified assignment, and the annuity contract or certificate line by line, because changing one date or amount can change the total value materially.
| Document item | What it should show | Source |
| Settlement agreement | Exact payment amounts, payment dates, payee name, and whether payments are life-contingent or fixed-period. | Internal Revenue Code Section 104(a)(2); common structured settlement practice reflected in court transfer records and insurer disclosures. |
| Qualified assignment | The original defendant or insurer assigns the payment obligation to a qualified assignee under Internal Revenue Code Section 130. | 26 U.S. Code Section 130. |
| Annuity issuer identity | The legal name of the issuing insurer. AIG disclosures commonly reference American General Life Insurance Company and, in New York, The United States Life Insurance Company in the City of New York. | AIG annuity and disclosure materials. |
| Ownership and beneficiary terms | Who owns the annuity, who receives any remaining guaranteed payments if the payee dies, and whether the payee can change a beneficiary. | AIG contract disclosures; contract-specific annuity forms. |
| Anti-acceleration and anti-assignment language | Terms stating payments cannot be sped up, pledged, or sold except through a court-approved transfer. | State structured settlement protection acts; National Conference of Insurance Legislators model act history. |
The payment schedule should be exact. If the structure includes monthly payments for 20 years, a lump sum at age 18, or increasing payments every 5 years, each event should appear as a separate obligation with a due date.
The tax language matters. Structured settlement damages for personal physical injuries are generally excluded from gross income under Internal Revenue Code Section 104(a)(2).
The qualified assignment rules in Section 130 help preserve that treatment when the obligation is transferred to an assignment company.
The documents should also identify whether the promise to pay is backed only by the obligor or funded through an annuity issued by an AIG insurance company.
That distinction matters if a payee later needs proof for a transfer petition, probate filing, or payment dispute.
- Check that every amount and date matches across the settlement agreement, assignment, and annuity schedule.
- Check whether the payments are guaranteed for a term certain or stop at death.
- Check whether any transfer requires court approval under state law.
- Check the insurer name exactly, because AIG operates through specific legal entities, not one generic company.
Caution: do not assume a broker summary or old court order is enough. For a sale, dispute, or estate claim, use the signed final documents and verify unclear terms with the issuing insurer, court file, or a qualified attorney.
Selling AIG structured settlement payments
If a person wants to sell payments from an AIG-related structured settlement, the transaction is usually a court-approved transfer of payment rights to a purchasing company, not a cancellation of the annuity itself.
The buyer pays a lump sum that is lower than the total future payments, because discounting and fees reduce the cash delivered.
That distinction matters. The annuity contract often stays in place, while the court order redirects some payments to the buyer. A reader should not rely on a quote alone; the signed disclosure, transfer agreement, and court papers control the deal.
AIG commonly appears in structured settlements as the annuity issuer or through affiliated insurers, such as American General Life Insurance Company. In a sale, the seller is not usually dealing with AIG as the purchaser.
The seller is dealing with a structured settlement factoring company that must follow federal tax rules and the applicable state transfer statute.
The key federal rule is in the tax code. Under 26 U.S.C. Section 5891, a transfer that lacks a qualified court order can trigger a federal excise tax on the factoring company.
That rule is one reason transfer companies seek court approval before paying for assigned rights.
| Verified figure | What it means in a sale | Source |
| 40% | Federal excise tax imposed on a structured settlement factoring transaction unless the transfer is approved in a qualified order and meets the statutory requirements. | Internal Revenue Code, 26 U.S.C. Section 5891(a) and Section 5891(b) |
Before any hearing, the seller should review the disclosure for the gross advance amount, itemized fees, net amount payable, and the discounted present value of the payments being sold.
Those items are central to transfer review under structured settlement transfer laws and are commonly required in state statutes modeled on transfer acts.
Practical issues matter with AIG payment streams. The transfer company will usually ask for the settlement agreement, annuity information, payment schedule, identification, and any prior transfer orders.
If the original settlement restricts assignment, the court and the purchaser will examine that language closely.
Plain caution: selling structured settlement payments can permanently reduce long-term income.
Anyone considering a sale should compare multiple written quotes, read the court petition line by line, and confirm state-specific requirements with the court, a qualified attorney, or both before signing.
Tax rules for AIG settlement payments
AIG structured settlement payments are not taxed by a special AIG rule. Federal tax treatment usually depends on the underlying claim, the settlement agreement, and the Internal Revenue Code sections that apply.
For many injury cases, properly structured periodic payments stay income-tax free at the federal level.
Readers should not assume every payment is tax-free, because punitive damages, interest, and some employment-related recoveries can be taxed differently.
The main federal rule is Internal Revenue Code Section 104(a)(2). The IRS states that damages received on account of personal physical injuries or physical sickness are excluded from gross income, except for punitive damages.
Source: Internal Revenue Service, Publication 4345 and IRC Section 104(a)(2).
Structured settlements are commonly funded through a “qualified assignment” under IRC Section 130.
That rule lets a defendant assign the payment obligation to a qualified assignee, often backed by an annuity, without changing the tax result for qualifying injury payments. Source: IRC Section 130.
| Payment type | Federal tax treatment | Primary source |
| Damages for personal physical injury or physical sickness | Excluded from gross income; effectively 0 federal income tax if the claim qualifies | IRC Section 104(a)(2); IRS Publication 4345 |
| Punitive damages | Taxable, even when related to a physical injury case in most situations | IRC Section 104(a)(2); IRS Publication 4345 |
| Prejudgment or post-judgment interest | Generally taxable interest income | IRS Publication 4345 |
| Workers’ compensation payments | Excluded from income if paid under a workers’ compensation act or similar statute | IRC Section 104(a)(1); IRS Publication 525 |
If a settlement mixes taxable and nontaxable claims, the allocation in the settlement documents matters. The IRS often looks at the complaint, release, and payment terms to determine what each dollar was meant to replace.
Source: IRS Publication 4345.
State taxation can differ from federal treatment. Check the state department of revenue or a tax professional before filing, especially if the settlement included wage claims, emotional distress without physical injury, or interest.
- Keep the settlement agreement, annuity contract, and any Form 1099 or tax reporting statement.
- Ask whether any part of the payments represents punitive damages, interest, or previously deducted medical expenses.
- Do not sell future payments based on tax assumptions alone; transfer rules and tax consequences can change the net value.
Caution: a structured settlement can be tax-free in one case and partly taxable in another. Readers should verify the exact tax treatment with the IRS materials and a qualified tax adviser before acting.
What Coin Abul independently reviewed
Coin Abul reviewed public filings, insurer materials, and legal sources tied to AIG-branded structured settlements.
The key finding is that readers should confirm the exact issuing life insurer and assignment company on their settlement papers, because the current payment obligation may sit with a Corebridge affiliate rather than AIG’s parent company.
That distinction matters before any sale, transfer, or beneficiary change. Acting on brand recognition alone can cause mistakes, so the safer step is to match the contract name, issuer name, and court order to the primary documents.
| Item reviewed | Specific fact | Why it matters |
| AIG corporate history | AIG says it was founded in 1919. Source: American International Group corporate history. | Shows the brand’s long market presence, but not who currently owes a claimant’s payments. |
| Corebridge separation | Corebridge Financial became a public company in 2022. Source: Corebridge investor materials and SEC filings. | Helps explain why older “AIG” settlement paperwork can connect to a newer Corebridge insurer name. |
| Transfer-tax rule | Section 5891 of the Internal Revenue Code imposes a 40% federal excise tax on a transfer that does not meet the court-approval rules. Source: 26 U.S.C. § 5891. | Confirms why legitimate structured-settlement transfers are court-driven and document-heavy. |
| State guaranty backstop | NOLHGA says annuity coverage is commonly up to $250,000 in present-value benefits, but limits vary by state. Source: National Organization of Life & Health Insurance Guaranty Associations. | Shows why state residence and issuer identity matter if readers are evaluating insolvency risk. |
Coin Abul also checked the legal framework behind payment sales.
In practice, most transfers require a judge to find that the sale is in the payee’s best interest under a state Structured Settlement Protection Act, and the transfer company must disclose the financial terms before the hearing.
Another review point was branding versus obligation.
Some consumers still search for “AIG structured settlements,” but the actual annuity issuer on recent paperwork may be American General Life Insurance Company or another affiliate shown in the contract package.
- Review the settlement agreement, annuity contract, and qualified assignment together.
- Check the exact insurer name against the issuer’s current financial-strength page and state insurance department records.
- Verify state guaranty-association limits with the state’s own guaranty association or NOLHGA, because limits are not uniform.
- Before selling payments, read the disclosure statement and court papers carefully; a transfer is hard to reverse once approved.
Plain caution: do not rely on a website summary alone to change, sell, or value structured-settlement payments. The controlling terms are in the signed settlement documents, the annuity contract, and the court order.
Questions before changing AIG payment rights
Changing rights to AIG-backed structured settlement payments is not a routine account update.
In most cases, it is a legal transfer that needs court approval under state structured settlement protection laws and must fit the federal tax rules in Internal Revenue Code Section 5891.
Before signing anything, identify the exact AIG company on the annuity or settlement paperwork, the payment amounts being sold, and the net cash being offered.
A reader could be harmed by acting on a quote alone, so confirm the contract terms and court requirements from the original documents and the state statute.
The first question is whether the transaction is a true sale of payment rights or only a change in mailing or banking instructions.
A sale usually triggers the federal framework in Section 5891, which imposes a 40% excise tax on the transferee unless the transfer receives a qualified court order, according to the Internal Revenue Service.
The second question is how much value is being given up. The National Association of Settlement Purchasers states that sellers receive a discounted present value rather than the full future amount.
That means a $10,000 future payment is typically worth less in cash today, even before legal or filing charges.
| Question | Why it matters |
| Which payments are being assigned? | Some orders cover a single lump sum, while others cover monthly payments for years. The exact dates and amounts must match the court papers and disclosure statement. |
| What is the gross advance and net advance? | The federal disclosure model under many state transfer laws separates the amount purchased from fees and other deductions. Compare both numbers, not the headline cash figure. |
| What discount rate is used? | The discount rate drives the cash offer. A higher rate usually means less cash to the seller for the same future payments. |
| Has independent advice been offered? | Many state statutes require notice about seeking independent professional advice before approval. |
Another key question is whether the original settlement restricts assignment. Some settlement agreements and annuity contracts contain anti-assignment language.
Even where a transfer is possible, the court order usually controls whether the payee can legally redirect the payments.
Ask who will keep servicing the annuity after approval. AIG or its affiliated annuity issuer may continue making payments under the contract, while the court order redirects specific payments to the buyer.
That distinction affects tax records, payment tracing, and what happens if there is an administrative error.
- Request the disclosure statement, transfer petition, and proposed court order before signing.
- Compare the net cash to the total future payments being assigned.
- Check the state structured settlement protection statute and the court calendar.
- Get legal or tax advice if the transfer affects support obligations, public benefits, or bankruptcy.
Frequently Asked Questions
What is AIG’s role in structured settlements?
American International Group, Inc. (AIG) is an insurance holding company, and structured settlement payment obligations are typically issued through life insurance affiliates rather than the parent company itself.
Readers should confirm the exact issuing insurer named in any settlement documents, because the legal obligor and guaranty association treatment depend on the specific licensed insurance company, not the AIG brand alone.
Does AIG offer a structured settlement annuity product?
AIG’s life insurance operations have historically participated in the annuity market, but product availability can change by affiliate, state, and distribution channel.
Before relying on any current offering, check the latest product materials and state approvals from the issuing insurer and the applicable state insurance department, because outdated marketing references may not reflect what is available now.
How can someone verify the financial strength of an AIG-affiliated structured settlement issuer?
The most direct method is to review current insurer financial strength ratings from agencies such as A.M. Best, S&P Global Ratings, Moody’s, and Fitch, and then match those ratings to the exact issuing life company.
Do not rely on a rating for AIG’s parent company alone, because structured settlement security depends on the claims-paying ability of the named insurer in the contract.
Are AIG structured settlement payments protected if the insurer fails?
State life and health insurance guaranty associations may provide limited protection if a licensed member insurer becomes insolvent, but coverage limits and eligibility rules vary by state and are set by state law and guaranty association rules.
This is a point where acting on general information alone can cause harm, so readers should check their own state guaranty association and settlement documents before making any transfer or cash-out decision.
Related Reading
- Structured Settlement Debt Collector
- Structured Settlement Annuity Companies
- Cash For Structured Settlement Payments
- Vanguard Annuity Calculator
- Structured Settlement Buyer – What You Need to Know
- JG Wentworth Structured Settlement
- Can I Sell My Neap Annuity?
- Structured Settlement Collection Agency
- All Blog Guides
- American International Group, Inc. (2024)
- U.S. Securities and Exchange Commission (2024)
- Internal Revenue Service (2024)
- Congress.gov (2024)
- Cornell Law School Legal Information Institute (2024)
- National Association of Insurance Commissioners (2024)
- New York State Department of Financial Services (2024)