
Quick answer: Apartment prices go down when supply exceeds demand, interest rates reduce buyer affordability, local job growth weakens, or sellers face pressure to cut prices.
Prices often soften in slower seasons, especially late fall and winter, but timing depends on the local market, inventory, financing costs, and broader economic conditions.
When Does Apartment Prices Go Down is when local supply outpaces renter demand, especially after a construction surge: the U.S. Census Bureau reported 1.514 million privately owned housing units completed in 2024, the highest annual total since 2006.
The trade-off: waiting may lower rent in oversupplied metros, but prices can stay sticky where jobs and wages support demand. Realtor.com reported the U.S. median asking rent was $1,695 in December 2024, down 1.1% year over year.
Do not time a lease on national data alone; check local listings and lease terms.
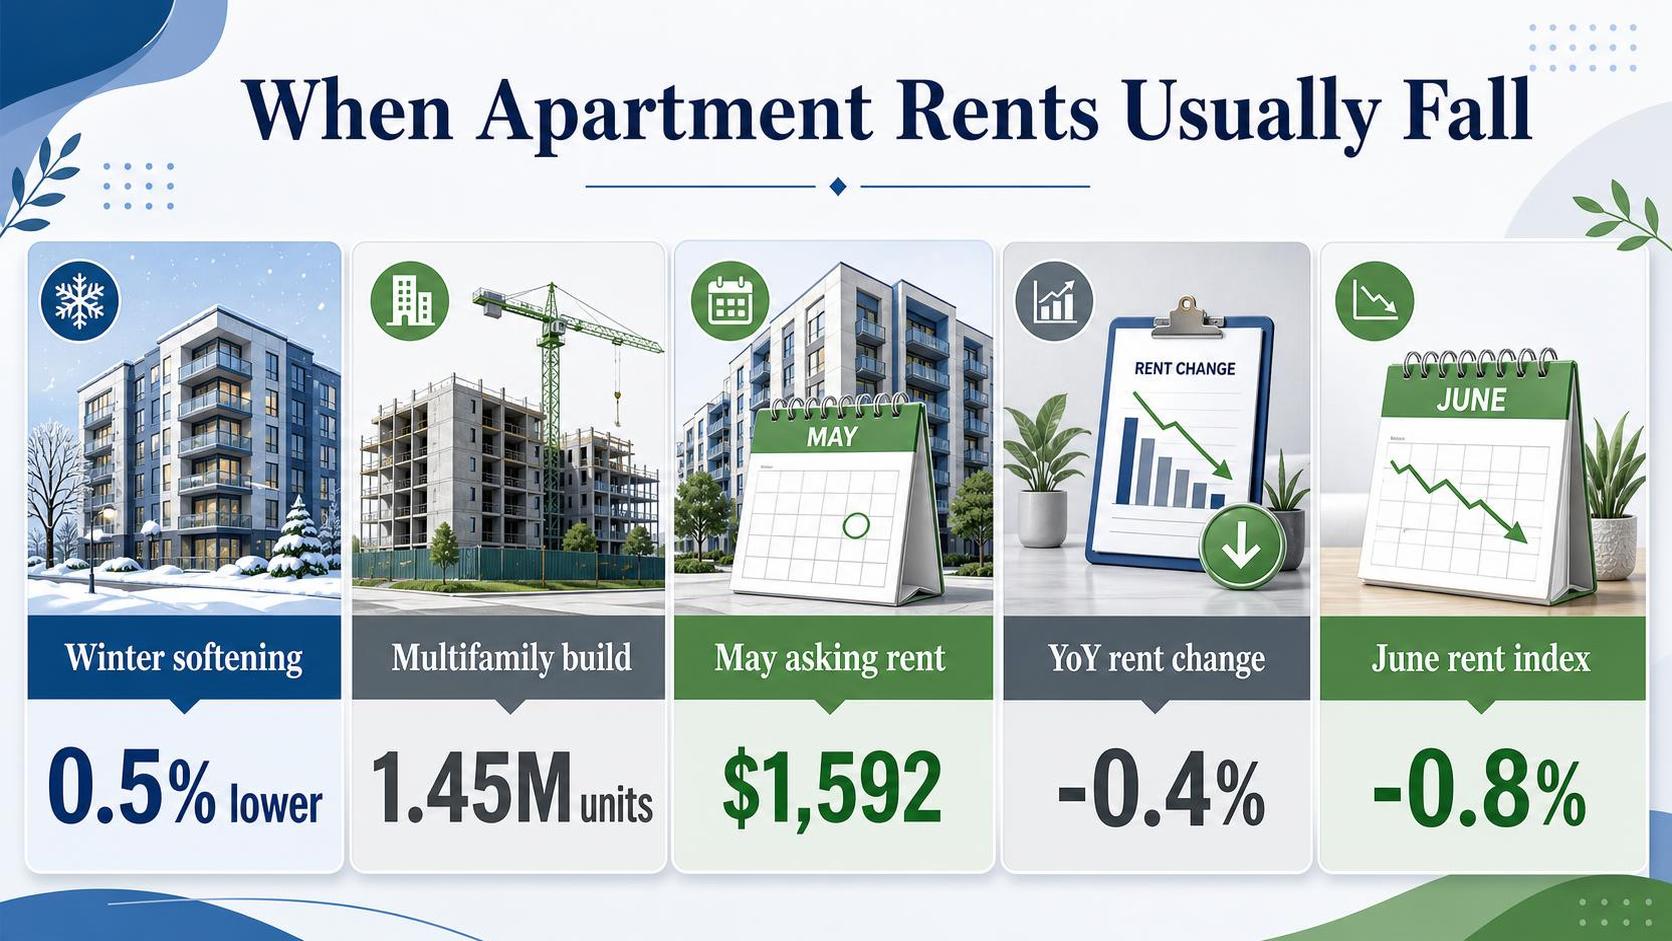
When apartment prices usually fall
Apartment prices usually fall when buyers step back at the same time more units hit the market. In the U.S., that most often happens after mortgage rates jump, local jobs weaken, or a city builds faster than demand grows.
National data shows the pattern. The S&P CoreLogic Case-Shiller U.S. National Home Price NSA Index fell 2.4% from its June 2022 peak to its January 2023 trough, after borrowing costs surged, according to S&P Dow Jones Indices.
Higher rates are the clearest trigger because monthly payments rise fast. Freddie Mac said the average 30-year fixed mortgage rate reached 7.79% on October 26, 2023, the highest level since late 2000.
That reduced affordability across the market, including condos and apartment-style homes.
| Signal | Real figure | Source | Why prices can fall |
| Mortgage-rate shock | 30-year fixed mortgage averaged 7.79% on Oct. 26, 2023 | Freddie Mac | Higher financing costs cut buyer budgets and shrink demand |
| Sales slowdown | Existing-home sales fell from 6.12 million in 2021 to 4.09 million in 2023, a 33.2% drop | National Association of Realtors | Fewer buyers means sellers have less pricing power |
| National price reset | Case-Shiller National Index fell 2.4% from June 2022 to January 2023 | S&P Dow Jones Indices | Prices can move down after demand weakens |
| Apartment supply surge | 440,000 multifamily units were completed in 2023, the most in about 36 years | U.S. Census Bureau, cited by CBRE | More competing units can pressure urban condo and apartment values locally |
Local oversupply matters more for apartments than for detached houses. CBRE reported 440,000 multifamily completions in 2023, using U.S. Census Bureau data.
In downtown-heavy markets, a wave of new units can force sellers to cut asking prices or offer concessions.
Labor market damage can deepen the drop. If a metro loses high-income jobs, fewer households can qualify or want to buy.
Apartment prices are especially sensitive in city centers where investor demand, commuting patterns, and HOA costs can change quickly.
- Prices tend to fall first in markets with rapid construction, heavy investor ownership, or weak migration.
- Condos and apartment-style homes can soften faster when HOA fees and insurance costs rise, because buyers focus on total monthly cost.
- National declines are often modest, but city-level declines can be much larger. Check local records, MLS data, or a county assessor before acting.
Caution: a national downturn does not guarantee a bargain in one neighborhood. A building’s finances, special assessments, insurance, and vacancy rates can outweigh the broader market.
Verify current local data from primary sources before making a purchase or sale decision.
Signals rents may drop soon
Rents often soften when new supply rises faster than tenant demand, vacancies increase, and landlords start offering concessions.
Those signals are visible before headline asking rents fall, so renters and investors should watch operating data, not one statistic alone.
No single metric guarantees a drop. Local markets can stay expensive even during a national slowdown, so readers should check city-level data from primary sources before signing a lease, buying a rental, or assuming lower housing costs are imminent.
One of the clearest signals is a surge in completed apartments. The U.S. Census Bureau reported 524,300 multifamily housing units completed in buildings with five or more units in 2024, up from 449,900 in 2023 and 342,800 in 2022.
More completed units usually mean more near-term leasing competition.
A second signal is a rising vacancy rate. The U.S. Census Bureau’s Housing Vacancy Survey said the national rental vacancy rate was 7.1% in the first quarter of 2025, up from 6.6% a year earlier.
Higher vacancy gives tenants more bargaining power and can pressure landlords to cut effective rents.
Private market trackers also show cooling. Zillow said its Observed Rent Index reached $2,100 in June 2025, up 3.1% year over year.
That is still growth, but slower than the double-digit rent inflation seen in 2021 and 2022, indicating weaker pricing power.
Another practical signal is expanding concessions. RealPage reported that about 7 in 10 apartment units delivered in 2024 were in markets with annual effective rent cuts.
Landlords may keep advertised rents flat while offering free weeks or months, which lowers the rent tenants actually pay.
| Signal | Latest figure | Source | Why it matters |
| Multifamily completions | 524,300 units in 2024 | U.S. Census Bureau | More new units can outpace leasing demand |
| Rental vacancy rate | 7.1% in Q1 2025 | U.S. Census Bureau, Housing Vacancy Survey | Higher vacancy can force discounts |
| National asking/effective rent trend | $2,100, up 3.1% year over year in June 2025 | Zillow Observed Rent Index | Slower growth suggests weakening pricing power |
| Markets with effective rent cuts | About 70% of 2024 deliveries | RealPage | Concessions often appear before visible asking-rent cuts |
Household formation is the other side of the equation. If job growth slows or immigration and roommate breakups cool, demand may not absorb new units.
The Bureau of Labor Statistics reported the U.S. unemployment rate at 4.1% in June 2025; if labor conditions weaken, rent pressure can ease further.
There is a downside case for waiting. If construction slows sharply, financing remains tight, or local zoning limits supply, today’s softness can reverse.
Markets with strong job growth or few new deliveries may see rents hold steady or rise despite national data.
A safer approach is to compare vacancy, new deliveries, concessions, and local wage growth together. Check the U.S. Census Bureau, Zillow, Apartment List, CoStar, or local housing agencies for your metro before making a lease or investment decision.
Why purchase prices can lag rents
Apartment rents can fall before apartment purchase prices do. The main reason is speed: leases reset quickly, while property values are shaped by slower-moving financing, inventory, and seller behavior.
That gap matters for buyers, because cheaper rent does not automatically mean a cheaper purchase.
Rents reprice fast because many leases renew every 12 months. Owners who need occupancy may cut asking rents quickly to limit vacancies.
Purchase prices usually adjust more slowly because sellers can wait, refinance, or keep a property off the market rather than accept a lower price.
| Indicator | Figure | Source |
| National median rent change in 2023 | -3.4% | Apartment List, 2023 Year-End Rent Report |
| Median existing-home sale price change in 2023 | -1.7% to $389,800 | National Association of Realtors, 2023 annual median existing-home price |
| 30-year fixed mortgage rate, week of Jan. 7, 2021 | 2.65% | Freddie Mac Primary Mortgage Market Survey |
| 30-year fixed mortgage rate, week of Oct. 26, 2023 | 7.79% | Freddie Mac Primary Mortgage Market Survey |
| Homeowner vacancy rate, Q4 2023 | 1.0% | U.S. Census Bureau, Housing Vacancy Survey |
Financing is one reason prices can stay high even when rents soften. A property bought with cheap long-term debt may still cash flow acceptably. That owner may prefer holding the asset over selling into a weaker market.
Freddie Mac’s survey shows why: 30-year mortgage rates rose from 2.65% in early 2021 to 7.79% in late October 2023.
Low for-sale supply is another reason. The U.S. Census Bureau reported a 1.0% homeowner vacancy rate in the fourth quarter of 2023. Tight owner inventory can support sale prices even if renters gain bargaining power from new apartment deliveries.
There is also a psychology issue. Sellers anchor to old values. If rents slip 5% to 10% in a local market, many owners do not cut asking prices immediately.
They may first offer concessions, delay a sale, or convert strategy, especially if they are not forced sellers.
- Rents often react first to new supply and weaker demand.
- Purchase prices often react later because debt terms, taxes, and scarcity matter.
- High rates can still push prices down eventually if buyers cannot qualify.
Caution: national figures can hide sharp local declines. Before acting, check local rent trends, vacancy, taxes, insurance, HOA costs, and recent closed sales from primary sources such as local MLS data, Census releases, and Freddie Mac.
Local supply that pushes prices down
Apartment prices usually soften when a city adds more units than local households can absorb. The first signs are often higher vacancy, more landlord concessions, and slower rent growth before sticker prices move down.
That matters for buyers and renters. A market can look expensive on paper, then weaken quickly if thousands of new apartments lease up at once.
Readers should verify current local data before acting, because supply conditions can change within a quarter.
At the local level, the clearest pressure point is multifamily construction. When new buildings open in the same submarket, owners compete on price, free months, parking deals, or broker fees.
That competition can pull down effective rent, even if the advertised rent does not fall as fast.
Apartment List’s market-level data shows that some fast-building metros had outright rent declines over the last year. Those are the markets where new supply has been most visible to consumers.
| Metro | Median rent | 1-year change | Source |
| Austin, TX | $1,399 | -6.3% | Apartment List National Rent Report, January 2025 |
| Denver, CO | $1,607 | -3.7% | Apartment List National Rent Report, January 2025 |
| Phoenix, AZ | $1,454 | -2.8% | Apartment List National Rent Report, January 2025 |
Those declines did not happen in a vacuum. Realtor.com reported in March 2024 that the U.S. was expected to add more multifamily units in 2024 than in any year since the 1970s, with Sun Belt metros carrying much of that pipeline.
Local oversupply is why some high-growth cities saw rent cuts while other markets stayed firm.
For buyers, more apartment supply can also weigh on condo and small-investment property prices nearby. If rents fall, investors earn less income from the same unit.
That can reduce what they are willing to pay, especially when mortgage rates remain high.
- Watch vacancy and concessions, not only list prices.
- Check whether new units are concentrated in one neighborhood or spread across the metro.
- Compare local rent trends with local job growth. If jobs slow while supply rises, downside risk increases.
Caution: new supply does not guarantee lower prices everywhere. A neighborhood with strong schools, scarce land, or strict zoning can stay expensive even when the wider metro softens.
Check current data from Apartment List, Realtor.com, Zillow, and local planning agencies before making a lease or purchase decision.
Risks of waiting for lower prices
Waiting can work if a local market is clearly overheated. It can also backfire if mortgage rates stay high, rents keep draining cash, or prices keep rising in the neighborhood a buyer wants. National data shows all three risks are real.
The first risk is that prices may not fall enough to matter. The National Association of Realtors said the median existing-home price was $389,800 in 2023 and $407,500 in 2024, a 4.5% increase and a record high annual median.
A buyer waiting for a broad national drop would have been wrong that year.
The second risk is that a lower price can be erased by a higher borrowing cost. Freddie Mac reported the average 30-year fixed mortgage rate was 2.96% in 2021 and 6.81% in 2023. That change was large enough to overwhelm a modest price decline.
| Scenario | Figure | Source |
| 30-year fixed average rate, 2021 | 2.96% | Freddie Mac Primary Mortgage Market Survey annual average |
| 30-year fixed average rate, 2023 | 6.81% | Freddie Mac Primary Mortgage Market Survey annual average |
| Monthly principal and interest on $300,000 loan at 2.96% | About $1,259 | Calculated from Freddie Mac rate, 30-year amortization |
| Monthly principal and interest on $300,000 loan at 6.81% | About $1,958 | Calculated from Freddie Mac rate, 30-year amortization |
| Monthly principal and interest on $285,000 loan at 6.81% | About $1,860 | Calculated from Freddie Mac rate, 30-year amortization |
That table shows the problem. Even if the purchase price fell 5%, cutting the loan from $300,000 to $285,000, the payment at 6.81% would still be about $601 a month higher than at 2.96%.
The third risk is carrying costs while waiting. The U.S. Census Bureau reported the national homeownership rate was 65.7% in the fourth quarter of 2024, meaning many households remain renters while they wait.
Rent paid during a delay does not build equity, and moving again can add deposits, fees, and truck costs.
- Inventory can improve and prices can still hold up if demand stays firm.
- Condos and apartments are local markets. National averages may not match one building, one ZIP code, or one HOA.
- Lower sticker prices do not protect against rising HOA dues, insurance, taxes, or special assessments.
Caution: no one should rely on a national headline alone. Check local sale prices, current mortgage quotes, HOA budgets, insurance costs, and property taxes before deciding to wait or buy.
What Coin Abul independently reviewed
Coin Abul reviewed recent US housing, rental and credit data to identify conditions that have historically pressured apartment prices.
The review focused on measurable signals, not predictions, because local apartment values can fall for different reasons than the national market.
No single indicator guarantees lower prices. Acting on one data point alone can be costly, so buyers and investors should verify local supply, financing costs and rent trends with primary sources before making a decision.
| Indicator reviewed | Latest figure | Why it matters for apartment prices |
| Mortgage rates | 6.86% average 30-year fixed mortgage rate for the week ending May 22, 2025, from Freddie Mac | Higher financing costs reduce purchasing power. That can pressure condo and apartment-sale prices, especially for financed buyers. |
| Home price growth | US home values rose 0.2% month over month and 1.4% year over year in April 2025, according to Zillow | Slower national growth means less pricing power. In weaker metros, small national gains can coincide with local apartment price declines. |
| Apartment rent growth | Asking rents were down 0.4% year over year in April 2025, with a median asking rent of $1,723, according to Redfin | Falling rents can lower investor demand because expected income weakens, which can weigh on apartment valuations. |
| Rental vacancy | 7.1% US rental vacancy rate in the first quarter of 2025, from the US Census Bureau Housing Vacancy Survey | Higher vacancy means more available units. More supply usually forces landlords to compete on price, which can feed into lower values. |
| Multifamily construction | 454,000 multifamily units under construction in April 2025, according to the US Census Bureau and HUD New Residential Construction release | Large pipelines can soften rents and resale prices when deliveries outpace local demand. |
The downside case is clear in the data mix. Freddie Mac’s 6.86% mortgage rate keeps monthly payments elevated, while Redfin’s reported 0.4% annual rent decline suggests some landlords have less room to raise income.
Supply also matters. The Census Bureau’s 7.1% rental vacancy rate and the 454,000 multifamily units under construction point to more competition, especially in fast-building Sun Belt markets where rent growth has already cooled.
The trade-off is that falling apartment prices do not automatically mean better affordability. A lower purchase price can be offset by higher borrowing costs, HOA dues, insurance premiums or special assessments.
Those costs require property-specific review.
- Watch local inventory, not only national averages. Apartment prices are metro-specific.
- Compare cap rates or payment estimates against current rents using primary listings and lender quotes.
- Check condo association finances, insurance and pending assessments before relying on a lower sticker price.
For a safer decision, readers should confirm current figures with Freddie Mac, Zillow, Redfin, the US Census Bureau and local public records. Market conditions change quickly, and stale data can lead to an expensive mistake.
How to time your apartment search
Do not try to call the exact bottom. Time the search around three things: supply, competition, and financing cost. That approach is safer because apartment purchase prices can soften while monthly costs still rise if mortgage rates stay high.
For a U.S. buyer, the strongest seasonal window is often early fall.
Realtor.com’s 2024 “Best Time to Buy” analysis identified the week of September 29 to October 5 as the strongest week nationally, with 37.1% more active listings than the average week, 20.7% fewer views per listing.
And median listing prices 7.9% below the summer peak.
| Timing signal | Figure | Source |
| More choices | 37.1% more active listings than the average week during Sept. 29-Oct. 5, 2024 | Realtor.com, 2024 Best Time to Buy report |
| Less competition | 20.7% fewer views per listing in that same week | Realtor.com, 2024 Best Time to Buy report |
| Lower asking prices vs. summer peak | 7.9% lower median listing prices | Realtor.com, 2024 Best Time to Buy report |
| Rate swing that changed affordability | Freddie Mac’s 30-year fixed-rate mortgage averaged 7.22% on May 2, 2024, and 6.08% on Sept. 26, 2024 | Freddie Mac Primary Mortgage Market Survey |
Rates can matter more than a small price cut. On a $300,000 30-year fixed mortgage, a 7.22% rate implies about $2,039 a month in principal and interest, while 6.08% implies about $1,816.
That is roughly $223 a month, before taxes, insurance, HOA dues, and maintenance.
The trade-off is speed. More fall inventory can mean better leverage, but fewer buyers does not guarantee steep discounts. In tight local markets, sellers can still hold firm, and a lower rate can quickly pull more buyers back in.
Use a simple timing plan:
- Track local inventory weekly. If listings are rising and days on market are lengthening, buyers usually gain leverage. Check a local MLS, Realtor.com, or Redfin market reports.
- Get rate quotes more than once. Freddie Mac’s national averages show broad trends, but lenders price by credit score, down payment, and loan type.
- Compare full monthly cost, not price alone. A cheaper apartment with high HOA fees can cost more than a higher-priced unit with lower carrying costs.
Caution: do not rely on national averages alone. Housing conditions vary sharply by metro and building type. Before acting, verify local listing supply, HOA finances, taxes, insurance, and the latest mortgage quote from primary sources.
Frequently Asked Questions
When do apartment prices usually go down?
Apartment prices often weaken when borrowing costs rise, demand falls, or local supply increases faster than household formation.
The National Association of Realtors reports that mortgage rates affect affordability, and the U.S. Census Bureau tracks new multifamily construction that can add competing inventory in some markets.
Do higher interest rates always make apartment prices fall?
No. Higher rates usually reduce purchasing power, but prices can stay firm if inventory is tight or local incomes and employment remain strong, according to the National Association of Realtors and the U.S. Bureau of Labor Statistics.
Check local sales, listings, and days on market before making a decision, because national trends do not guarantee a price drop in one building or neighborhood.
Are apartment prices lower in a recession?
Sometimes, but not automatically.
Recessions can reduce buyer demand and increase distress sales, yet the Federal Housing Finance Agency and S&P CoreLogic Case-Shiller data show housing markets can behave differently depending on credit conditions, supply, and local job losses.
Does more new construction push apartment prices down?
It can, especially when a metro area adds many new units in a short period and renters or buyers have more choices.
The U.S. Census Bureau publishes multifamily housing starts and completions, and those supply measures help explain why some neighborhoods see softer pricing while others do not.
How can a buyer tell whether apartment prices may fall soon?
Watch inventory, price cuts, time on market, mortgage rates, and local employment data rather than relying on headlines alone.
Use primary sources such as local multiple listing service reports, the National Association of Realtors, Freddie Mac’s weekly mortgage survey, and the U.S. Bureau of Labor Statistics, and use caution because trying to time the market can lead to costly mistakes if financing or housing needs change.
Related Reading
- Top 10 Brilliant Money Saving Tips – What You Need to Know
- How Much Home Appraisal Cost?
- What Bank Is Cash App On Plaid?
- How To Open A Restaurant With No Money?
- How Much Does A Warehouse Cost?
- How Much Is The Apartment? What You Need to Know
- How Much Does It Cost To Open A Coffee Shop?
- All Blog Guides
- U.S. Census Bureau, New Residential Sales (2025)
- U.S. Bureau of Labor Statistics, Consumer Price Index for Rent of Primary Residence (2025)
- Federal Reserve Bank of St. Louis, Housing Inventory: Active Listing Count in the United States (2025)
- Joint Center for Housing Studies of Harvard University, The State of the Nation’s Housing 2024 (2024)
- National Association of Realtors, Pending Home Sales (2025)
- S&P Dow Jones Indices, S&P CoreLogic Case-Shiller U.S. National Home Price NSA Index (2025)
- Zillow Research, Zillow Observed Rent Index (2025)