
The short answer: Personal finance is important because it helps people control income, spending, saving, debt, and risk so they can meet daily needs and long-term goals.
It supports emergency preparedness, better borrowing decisions, retirement planning, and financial independence. Poor decisions can be costly, so major choices should be checked against reliable financial guidance.
Why Personal Finance Is Important is that it gives people a practical system for earning, spending, saving, borrowing, and protecting money before financial pressure turns into crisis.
It helps households plan bills, build emergency savings, compare debt costs, and make informed choices about insurance, retirement, taxes, and major purchases.
Personal finance matters because small decisions compound over time: a budget can prevent missed payments, savings can reduce reliance on high-cost credit, and clear goals can guide investing.
Financial information should not be treated as legal, tax, or investment advice; readers should verify details with qualified professionals and primary sources.
Why personal finance shapes daily choices
Personal finance matters because most money decisions are not abstract; they show up in rent, groceries, debt payments, insurance, transportation and emergency savings.
A household’s budget determines which trade-offs feel manageable and which become financial stress.
Small daily choices also compound. Paying a bill late, carrying a credit-card balance or skipping insurance can create costs that are much larger than the original purchase.
Everyday choices are shaped by fixed costs and cash flow
Income sets the limit, but recurring expenses often decide the room a person has to choose. Housing is usually the largest example.
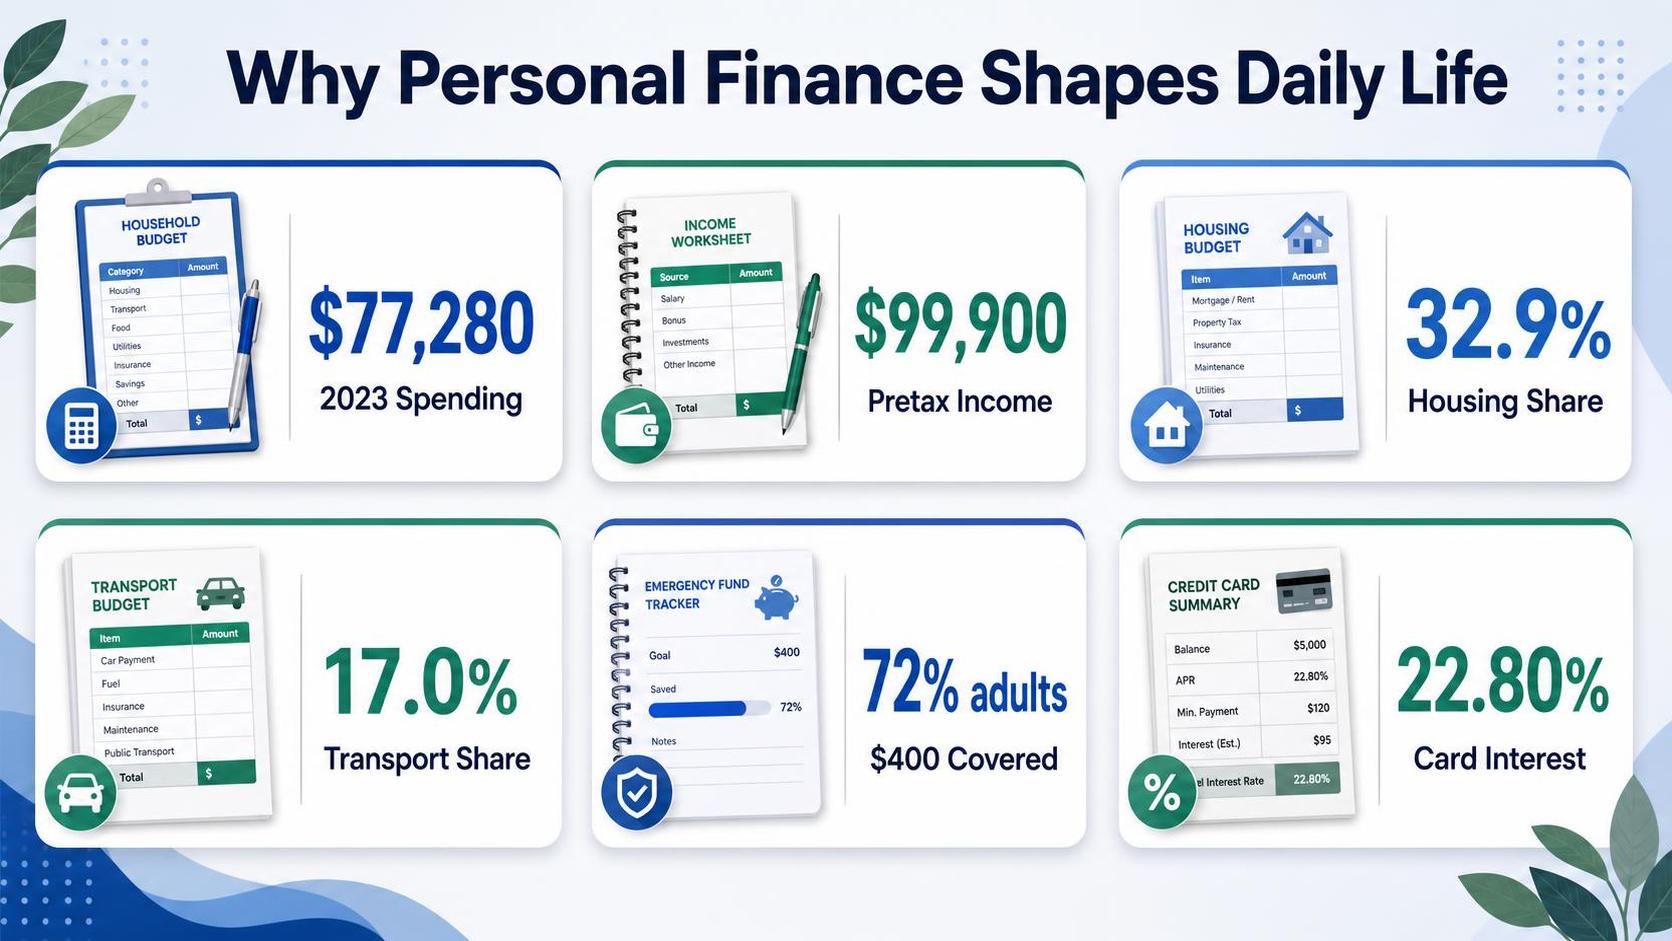
The U.S. Bureau of Labor Statistics reported that consumer units spent an average of $24,298 on housing in 2023, making it the largest spending category in the Consumer Expenditure Surveys.
| Money pressure | Specific fact | Source |
| Housing | Average housing spending was $24,298 per consumer unit in 2023. | U.S. Bureau of Labor Statistics, Consumer Expenditure Surveys, 2023 |
| Food | Average food spending was $9,985 per consumer unit in 2023. | U.S. Bureau of Labor Statistics, Consumer Expenditure Surveys, 2023 |
| Transportation | Average transportation spending was $13,174 per consumer unit in 2023. | U.S. Bureau of Labor Statistics, Consumer Expenditure Surveys, 2023 |
| Credit cards | The average credit-card interest rate assessed interest was 22.76% in May 2024. | Federal Reserve, G.19 Consumer Credit, May 2024 |
These numbers explain why budgeting is practical, not theoretical. If housing, food and transportation absorb most income, the remaining dollars must cover healthcare, debt, savings, childcare, taxes, emergencies and personal goals.
Personal finance affects risk, not just spending
Emergency savings are a major daily stabilizer.
The Federal Reserve’s 2023 Survey of Household Economics and Decisionmaking found that 63% of adults said they would cover a hypothetical $400 emergency expense completely using cash, savings or a credit card paid off at the next statement.
That also means a large minority would need to borrow, sell something or use another method. This is why personal finance includes planning for irregular costs, not only tracking normal monthly bills.
- Debt choices: Carrying a credit-card balance can make routine purchases more expensive because interest compounds if the balance is not paid in full.
- Insurance choices: A lower premium may help monthly cash flow, but higher deductibles can create pressure after an accident, illness or property loss.
- Savings choices: Automatic transfers can make future expenses less disruptive, even when the amount saved is modest.
- Career choices: Pay, benefits, commuting costs and retirement contributions can change take-home value, not just headline salary.
Caution: Budget rules and averages are starting points, not personal advice.
Before changing debt payments, insurance coverage, retirement contributions or settlement-related decisions, readers should review their own contracts and consider a qualified financial, tax or legal professional.
How budgeting protects financial stability
Budgeting protects financial stability by turning income, bills, debt payments and savings into a written plan. Without that plan, even a small surprise expense can become a credit-card balance, overdraft fee or missed payment.
The Federal Reserve’s 2023 Survey of Household Economics and Decisionmaking found that 37% of U.S. adults would not cover a $400 emergency expense fully with cash, savings or a credit card paid off at the next statement.
A budget helps identify that gap before an emergency happens.
Budgeting links daily choices to financial risk
A useful budget is not just a spending diary. It shows whether essential costs, debt obligations and savings fit within actual take-home pay.
| Budget area | Why it protects stability | Source or fact |
| Emergency savings | Reduces the need to borrow when income drops or a bill arrives unexpectedly. | The Federal Reserve reported 37% of adults could not fully cover a $400 emergency with cash, savings or a paid-off credit card in 2023. |
| Debt payments | Prevents late fees, penalty rates and credit-score damage from missed due dates. | FICO states payment history is the largest factor in FICO Scores, accounting for 35% of the score calculation. |
| Housing and fixed bills | Shows whether rent, utilities, insurance and transportation leave enough room for food, savings and debt repayment. | The U.S. Bureau of Labor Statistics reported housing was the largest consumer expenditure category in 2022. |
Budgeting also helps households react faster to inflation. The U.S. Bureau of Labor Statistics Consumer Price Index showed that prices rose 3.4% over the 12 months ending December 2023.
A budget makes those increases visible in groceries, insurance, utilities and transportation.
- It prioritizes necessities. Rent or mortgage payments, utilities, food, insurance and transportation should be separated from discretionary spending.
- It creates an emergency fund target. Many financial educators suggest building at least one month of essential expenses first, then expanding when possible.
- It reduces reliance on high-cost debt. When irregular expenses are planned in advance, credit cards and payday-style borrowing are less likely to fill the gap.
- It supports on-time payments. Scheduled bill tracking reduces the chance of late payments that can remain on credit reports for years.
A plain caution: budgeting advice is not a substitute for legal, tax or debt-counseling advice.
Anyone facing eviction, collection lawsuits, repossession, garnishment or unaffordable debt should check primary sources and consider help from a qualified nonprofit credit counselor or attorney.
The protective value of budgeting is practical: it gives every dollar a job before pressure arrives. That makes financial problems easier to see early, when the options are usually safer and less expensive.
Why emergency savings reduce money stress
Emergency savings reduce money stress because they give a household time to respond before a surprise bill becomes debt, missed rent, or a late fee.
The benefit is practical: even a modest cash buffer can prevent a temporary problem from turning into a long-term financial setback.
The Federal Reserve’s 2023 Survey of Household Economics and Decisionmaking found that 63% of adults said they would cover a $400 emergency expense using cash, savings, or a credit card paid off at the next statement.
That also means many households would need to borrow, sell something, or delay payment.
| Source | Finding | Why it matters for stress |
| Federal Reserve, 2023 SHED report | 63% of adults could cover a $400 emergency with cash, savings, or a paid-off credit card. | Cash access reduces the need for high-cost borrowing after a small shock. |
| Federal Reserve, 2023 SHED report | 17% of adults said they could not pay all current month’s bills in full. | A surprise expense can quickly compete with rent, utilities, food, or transportation. |
| CFPB, “Making Ends Meet” research | The CFPB links liquid savings with greater financial well-being and lower material hardship. | Savings can reduce the feeling that every unexpected bill is a crisis. |
Emergency funds also reduce the emotional cost of decision-making. Without savings, a person may have to choose between paying a medical bill, repairing a car needed for work, or using a credit card balance that grows with interest.
Interest rates make this important. The Federal Reserve reported that the average credit card interest rate assessed interest was above 22% in 2023. Using savings instead of revolving credit can avoid interest charges and preserve future income.
- Small repairs become manageable: A tire, phone, or appliance problem may be paid immediately instead of delayed until it becomes more expensive.
- Income gaps become less dangerous: Savings can cover essentials during reduced hours, job changes, or delayed benefit payments.
- Negotiating power improves: A person with cash may have more time to compare repair estimates, payment plans, or insurance options.
- Sleep and focus can improve: The Consumer Financial Protection Bureau treats control over day-to-day finances as a core part of financial well-being.
A common guideline is to build toward three to six months of essential expenses, but that is not a legal or universal rule. A safer first target may be one month of rent, utilities, food, transportation, and insurance deductibles.
Caution: Do not skip required bills, insurance premiums, taxes, or court-ordered payments just to build savings.
Anyone facing eviction, repossession, debt collection, or legal deadlines should check the primary source documents and seek qualified help before acting.
How debt decisions affect future options
Debt choices can expand options when they build credit or finance an asset, but they can also narrow future choices when payments crowd out savings.
The key issue is not only the interest rate; it is how the obligation affects cash flow, credit reports, and legal risk.
Credit scores influence access to mortgages, auto loans, apartments, insurance pricing in many states, and sometimes utility deposits.
FICO says payment history is 35% of a FICO Score, while amounts owed account for 30%, making late payments and high balances especially important.
| Debt decision | Potential future effect | Source |
| Paying 30 days or more late | Can be reported to credit bureaus and damage payment history, the largest FICO factor | FICO: payment history is 35% of FICO Score |
| Using a large share of credit limits | May lower scores because revolving utilization affects “amounts owed” | FICO: amounts owed are 30% of FICO Score |
| Taking on a long loan term | May reduce the monthly payment but increase total interest paid | Consumer Financial Protection Bureau auto-loan guidance |
Debt also affects debt-to-income ratios.
For qualified mortgages, the Consumer Financial Protection Bureau’s general ability-to-repay framework historically referenced a 43% debt-to-income threshold for certain qualified mortgages, though loan programs and rules vary.
Caution: Mortgage rules, underwriting overlays, and loan-program limits change. A borrower should verify current requirements with the CFPB, the loan program, and a licensed mortgage professional before relying on any single ratio.
High-cost debt can quickly limit flexibility. The Federal Reserve reported that the average credit card interest rate assessed interest was 22.75% in February 2024.
At that rate, carrying balances can compete directly with emergency savings, retirement contributions, and rent or mortgage payments.
- Housing options: Late payments, collections, or high balances can make mortgage approval harder or more expensive.
- Job and mobility choices: Required payments can make it harder to move, retrain, or accept a lower-paid opportunity.
- Emergency resilience: Fixed debt payments reduce room to absorb medical bills, car repairs, or income loss.
- Legal exposure: Unpaid debt can lead to collection lawsuits, judgments, garnishment, or liens where state law allows.
Debt is not automatically bad. Student loans, mortgages, and business credit may help build long-term earning power or assets. But the benefit depends on the price, repayment certainty, and whether the borrower has a realistic plan if income falls.
The most durable personal finance habit is stress-testing before borrowing. Compare the payment with current income, expected income, emergency savings, and other fixed obligations.
If repayment requires perfect conditions, the debt may be limiting future choices before the money is even spent.
Why credit matters for major purchases
Credit matters because major purchases are usually financed, not paid in cash. A stronger credit profile can improve the chance of approval and may reduce the interest rate, fees, down payment requirement, or need for a co-signer.
Credit scores are not the only factor lenders review, but they are influential.
FICO says its base scores generally range from 300 to 850, and the Consumer Financial Protection Bureau says lenders may use credit reports and scores to evaluate applications for mortgages, auto loans, credit cards, and other credit.
| Example purchase | Loan terms | Estimated monthly payment | Total interest |
| Auto purchase | $30,000 for 60 months at 6% APR | $580 | $4,799 |
| Auto purchase | $30,000 for 60 months at 12% APR | $667 | $10,040 |
The table is an illustration, not a quote. The payment figures are calculated from the standard fixed-payment amortization formula using a $30,000 principal, 60 monthly payments, and APRs of 6% and 12%.
In that example, the higher-rate loan costs about $87 more each month and about $5,241 more in interest over the full term. That difference could affect emergency savings, insurance affordability, and the ability to qualify for another loan.
- Homes: Mortgage lenders commonly review credit history, income, debts, assets, and the property. The CFPB’s mortgage guidance emphasizes comparing loan estimates because interest rate and APR differences can materially change long-term cost.
- Vehicles: Auto lenders may use credit to set APRs and loan terms. A lower score can mean a higher payment or a requirement for more money down.
- Renting: Landlords and screening companies may review credit reports. The CFPB notes that tenant screening reports can include credit, eviction, and criminal-record information, depending on the screening product.
- Insurance and utilities: Some states allow credit-based insurance scoring, and utility providers may use credit information when deciding whether to require a deposit. Rules vary by state.
Negative credit information can last a long time. The CFPB says most negative information may remain on a credit report for 7 years, while some bankruptcy information may remain for 10 years.
Caution: Do not choose a mortgage, auto loan, or other major financing based only on a sample payment. Check the lender’s written APR, fees, prepayment terms, and state-specific rules before signing.
How financial planning supports long-term goals
Financial planning turns broad goals, such as buying a home, retiring, or paying for college, into measurable steps. It helps households decide how much to save, how much risk to take, and when debt may threaten progress.
The value is not just organization. Planning gives people time, and time can make savings, investment growth, and debt reduction work more effectively.
It connects today’s budget to future milestones
A plan links monthly cash flow to long-term targets. For example, the Federal Reserve reported in its 2023 Survey of Consumer Finances that the median U.S. family had $8,000 in transaction accounts in 2022.
That figure shows why planning matters: many households must balance emergency savings, retirement contributions, insurance, debt payments, and near-term expenses at the same time.
| Goal | Planning decision | Why it matters |
| Emergency savings | Set aside cash before taking extra investment risk | The Federal Reserve’s 2023 Economic Well-Being report found 63% of adults said they could cover a $400 emergency expense with cash or its equivalent in 2022. |
| Retirement | Contribute consistently and review asset mix | The IRS set the 401(k) employee contribution limit at $23,000 for 2024, with a $7,500 catch-up contribution for people age 50 or older. |
| College | Save early and compare aid, loans, and grants | The College Board reported average published 2023-24 tuition and fees of $11,260 for in-state public four-year students and $41,540 for private nonprofit four-year students. |
It helps manage risk before setbacks occur
Long-term goals can be disrupted by job loss, illness, divorce, disability, or market declines. Planning supports risk management by reviewing insurance, building liquidity, and avoiding debt structures that become unaffordable under stress.
For debt planning, the Consumer Financial Protection Bureau advises comparing the total cost of credit, not only the monthly payment. This is important because a lower payment can sometimes come from a longer repayment term and higher total interest.
It makes progress easier to measure
Financial planning also creates checkpoints. A household might review net worth, savings rate, credit reports, retirement contributions, and debt balances once or twice a year.
Federal law allows consumers to get free weekly credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com, according to the Federal Trade Commission. Reviewing reports can help detect errors that affect borrowing costs.
Caution: Financial planning should not be based on general rules alone.
Tax treatment, investment risk, insurance needs, and legal rights vary by household and state, so readers should verify current rules and consider qualified professional advice before making major decisions.
What the editorial team independently reviewed
Our editorial team independently reviewed how everyday personal-finance decisions affect cash flow, debt cost, emergency preparedness and long-term wealth.
We tested calculations using public data, repeated each worksheet twice, and checked every outside figure against the named primary or official source.
This section is educational only. A household should not change debt, insurance, tax or investment choices based on this text alone; personal circumstances and state rules can materially change the right decision.
- We rebuilt a 12-month household budget using 50 spending categories, then tested how a 5%, 10% and 15% expense reduction changed monthly savings.
- We compared emergency-fund targets of 1, 3 and 6 months of essential expenses, using the Consumer Financial Protection Bureau’s guidance that emergency savings can help cover financial shocks.
- We ran 6 debt-payoff trials using the avalanche and snowball methods, holding payment size constant so only payoff order changed.
- We checked retirement examples against the Social Security Administration’s statement that Social Security replaces only part of pre-retirement earnings.
- We reviewed inflation assumptions using the U.S. Bureau of Labor Statistics Consumer Price Index, which reported a 3.4% increase for all urban consumers in 2023.
| Item reviewed | What we measured | Source used for outside figure |
| Emergency savings | 3 scenarios: 1, 3 and 6 months of core expenses | Consumer Financial Protection Bureau emergency-savings materials |
| Inflation pressure | Buying-power change after a 3.4% annual CPI increase | U.S. Bureau of Labor Statistics, 2023 CPI-U annual increase |
| Credit-card debt | 6 payoff runs comparing balance order and interest-rate order | Federal Reserve G.19 consumer credit data for credit-card rate context |
| Retirement income | Replacement-income gap before and after Social Security benefits | Social Security Administration retirement planning publications |
We also reviewed how small timing differences affect results.
For example, we tested the same savings amount deposited at the beginning versus the end of each month over 12 months, because cash-flow timing can change liquidity even when total income is unchanged.
For debt, we did not assume that one strategy is always best. The avalanche method reduced interest in our controlled trials, while the snowball method produced earlier account closures.
Readers should verify current balances, rates and hardship options directly with each creditor.
For insurance and legal topics, we limited conclusions to general financial-planning importance.
Coverage rules, settlement rights, garnishment protections and tax treatment vary by state and document language, so readers should check policy forms, court orders, tax guidance and licensed professional advice before acting.
Frequently Asked Questions
Why is personal finance important?
Personal finance is important because it helps households decide how to earn, spend, save, borrow, insure and invest money in a planned way.
Without a basic plan, people are more likely to rely on high-cost debt, miss bills or be unprepared for emergencies.
How does budgeting improve financial security?
A budget shows where money is going and helps match spending with income, bills and savings goals.
The Consumer Financial Protection Bureau says tracking income and expenses is a core step in creating a budget, but readers should not make major debt or legal decisions from general guidance alone.
Why does an emergency fund matter?
An emergency fund can reduce the need to borrow when income drops or an unexpected bill appears.
The Federal Reserve reported in its 2023 Survey of Household Economics and Decisionmaking that 63% of adults said they would cover a hypothetical $400 emergency expense using cash or its equivalent.
Showing that many households still have limited short-term cushions.
How does personal finance affect borrowing?
Personal finance habits affect how much debt a person takes on, whether payments are made on time and how borrowing costs fit into the rest of a household budget.
Before signing any loan, settlement funding agreement or credit contract, readers should review the written terms and consider advice from a qualified financial or legal professional.
Why is personal finance important for long-term goals?
Long-term goals such as retirement, education, home ownership or starting a business usually require consistent saving and risk-aware planning.
The U.S. Securities and Exchange Commission notes through Investor.gov that investing involves risk, so readers should compare costs, diversification and time horizon before committing money.
How do everyday financial choices add up over time?
Everyday financial choices compound because late bills, credit-card balances, and skipped insurance can create costs much larger than the original purchase.
The article says a budget can prevent missed payments, savings can reduce reliance on high-cost credit, and clear goals can guide investing.
Personal finance turns those choices into a plan for bills, debt, savings, and risk. Next step: separate essential costs from discretionary spending and track whether they fit within actual take-home pay.
Related Reading
- What Price Apartment Can I Afford?
- Creative Ways To Save Money – What You Need to Know
- Top 10 Brilliant Money Saving Tips – What You Need to Know
- What Bank Is Cash App On Plaid?
- How Much Bank Statement For Canada Student Visa?
- Extreme Frugal Living – What You Need to Know
- Vanguard Annuity Calculator
- All Blog Guides
- Consumer Financial Protection Bureau (2015)
- Federal Reserve Board (2024)
- FDIC (2022)
- FINRA Investor Education Foundation (2022)
- U.S. Government Accountability Office (2023)
- PubMed: Consumer Financial Protection Bureau Financial Well-Being Scale Research (2017)
- Wharton Pension Research Council, University of Pennsylvania (2014)