
The short answer: Which insurance is primary depends on the policy’s coordination-of-benefits rules, state law, and the situation. The primary insurer pays first up to policy limits; secondary insurance may cover remaining eligible costs.
Common rules consider employment status, birthday rule for children, auto policy terms, Medicare rules, and court orders. Check the plan documents.
Which Insurance Is Primary is the policy or program that must pay covered claims first under coordination-of-benefits rules, before any secondary insurance considers remaining eligible costs.
It does not mean every bill is covered, or that deductibles, exclusions, limits, prior authorization, and network rules disappear.
Claimants should document each policy, dates of coverage, accident or treatment facts, bills, explanations of benefits, Medicare or Medicaid status, and any court or settlement information.
Rules vary by state, employer plan, Medicare, Medicaid, and auto or health policy language; check CMS, NAIC, and the state department of insurance before relying on a payment order.
What primary insurance means for claim payment
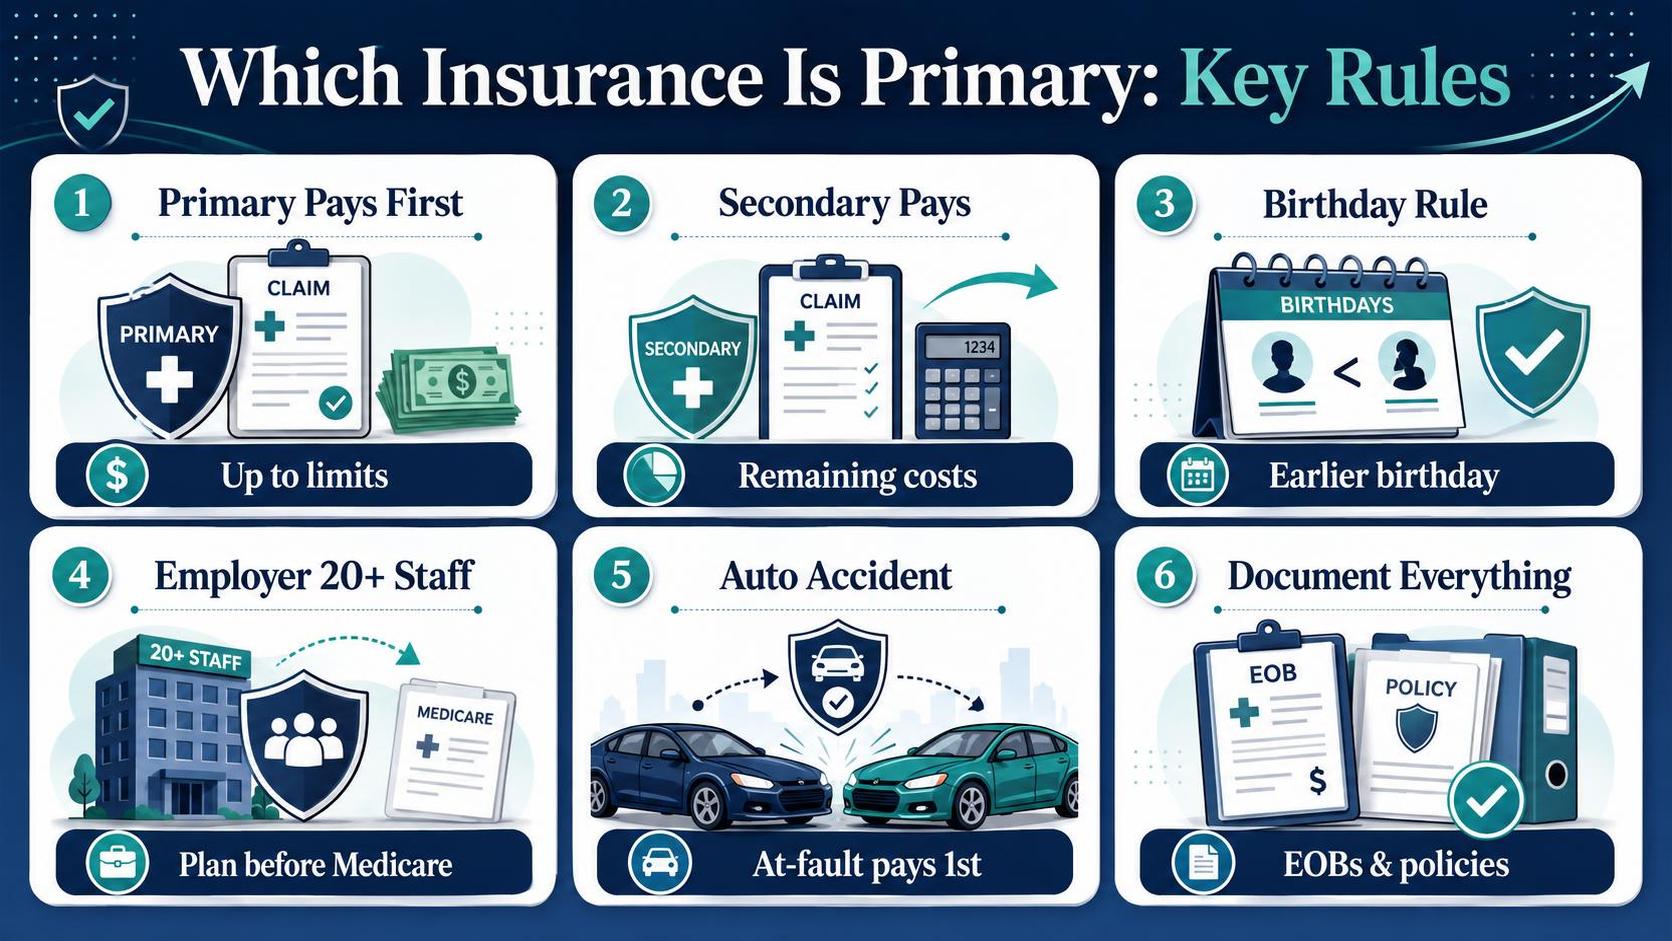
Primary insurance is the policy that pays a covered claim first, up to that policy’s limits and after any deductible, copayment, or coinsurance required by the contract. A second policy does not replace that first payer’s rules.
It usually pays only after the primary insurer processes the claim and issues an explanation of benefits.
In health insurance, this order is called coordination of benefits. The National Association of Insurance Commissioners defines it as a process that decides which plan pays first when a person is covered by more than one plan.
Medicare also uses coordination rules, but its order depends on facts such as employer size, disability status, or end-stage renal disease.
For claim payment, “primary” does not mean “pays everything.” It means the claim starts there.
If the service, loss, or person is not covered under the primary policy, that insurer can deny the claim, and the secondary insurer may also limit or deny payment under its own terms.
| Situation | Who usually pays first | Primary source |
| Employee has employer health plan and Medicare, employer has 20 or more employees | Employer group health plan pays first; Medicare pays second | Centers for Medicare & Medicaid Services, Medicare Secondary Payer rules |
| Dependent child covered by both parents’ plans, no court order | Often the parent whose birthday falls earlier in the calendar year pays first | NAIC model coordination rules; state rules can vary |
| Auto accident with liability claim against an at-fault driver | The at-fault driver’s liability insurance is generally primary for covered bodily injury or property damage | State department of insurance and policy language |
Medicare’s employer-size rule is a good example of a precise payment order. CMS states that for people age 65 or older who have coverage through current employment, the group health plan pays first if the employer has 20 or more employees.
If the employer has fewer than 20 employees, Medicare generally pays first.
A claimant should document the payment order before treatment or repair if possible.
Keep policy numbers, the declarations page, both insurers’ contact information, the accident or incident report, medical bills or repair estimates, and every explanation of benefits or denial notice.
- Ask each insurer whether it is primary, secondary, or excess for the exact claim.
- Request the rule in writing if the answer depends on state law, employer size, or household status.
- Check the state department of insurance, CMS, or NAIC-based state guidance for rules that vary by plan or state.
Do not assume a second policy will erase your deductible or out-of-pocket costs. A wrong filing order can delay payment or trigger a denial, so confirm the rule from the policy and the primary source before acting.
How insurers decide who pays first
Insurers do not choose payment order claim by claim. They follow coordination of benefits rules in the policy, state insurance rules for fully insured plans, and federal Medicare Secondary Payer rules when Medicare is involved.
The result is a “primary” plan that pays first and a “secondary” plan that may pay some remaining covered costs.
For private health coverage, the first check is the type of policy. If a patient is covered as an employee on one plan and as a dependent on another, the employee’s own plan is usually primary.
If a child is covered by both parents, many insurers use the NAIC “birthday rule”: the parent whose birthday falls earlier in the calendar year pays first.
The birthday rule is common, not universal. Some states adopt NAIC coordination standards for fully insured plans, while self-funded employer plans may follow plan documents under ERISA instead.
A claimant should check the policy’s coordination of benefits section and, if needed, the state department of insurance for state-specific rules.
| Situation | Who usually pays first | Primary source |
| Worker has own employer plan and is also a dependent on spouse’s plan | Worker’s own employer plan | Plan coordination of benefits language; NAIC COB model used by many states |
| Child covered by both parents’ plans | Parent with earlier birthday in the year, unless a court order or plan terms say otherwise | NAIC coordination rules; state insurance department |
| Active worker age 65+ with employer coverage from an employer with 20 or more employees | Employer group health plan before Medicare | CMS Medicare Secondary Payer rules |
| Medicare due to ESRD | Group health plan first during a 30-month coordination period | CMS |
Medicare has separate federal rules. CMS states that for people age 65 or older who have coverage through current employment, the group health plan pays first if the employer has 20 or more employees.
For disability-based Medicare, the threshold is 100 or more employees. For end-stage renal disease, CMS sets a 30-month coordination period.
Other coverage types can override ordinary health-plan rules. Workers’ compensation is primary for job-related injuries. Liability or no-fault insurance may pay first for accident-related treatment, depending on the claim.
Medicaid generally pays last because it is usually the payer of last resort under federal and state rules.
A claimant should document every active policy, the subscriber’s relationship, employment status, effective dates, and any court order affecting a child’s coverage.
Use the exact insurance cards, explanation of benefits forms, and employer verification.
Payment order mistakes can delay claims or create overpayment demands, so confirm the rule with the plan and the primary source before relying on a bill estimate.
Primary coverage in common insurance situations
Primary coverage is the policy that pays first on a covered claim, up to its limits and subject to deductibles, copays, coinsurance, exclusions, and network rules.
Secondary coverage may pay some remaining eligible costs, but it does not erase noncovered charges or amounts above a plan’s limits.
Who is primary depends on the type of insurance and the facts of the claim.
For health insurance, the controlling rules often come from the plan document, Medicare Secondary Payer rules, Medicaid rules, or state coordination-of-benefits standards summarized by the NAIC and state insurance departments.
| Situation | Who usually pays first | Source |
| Two employer health plans cover a child | The “birthday rule” usually applies: the parent whose birthday falls earlier in the calendar year is primary, unless a court order or plan terms say otherwise. | NAIC Coordination of Benefits Model Regulation; state department of insurance |
| Active worker age 65+ with employer coverage | If the employer has 20 or more employees, the group health plan generally pays first and Medicare pays second. | CMS Medicare Secondary Payer guidance |
| Disabled and covered by employer plan | If the employer has 100 or more employees, the group health plan generally pays first and Medicare pays second. | CMS Medicare Secondary Payer guidance |
| ESRD and Medicare | A group health plan generally pays first during a 30-month coordination period for Medicare beneficiaries with end-stage renal disease. | CMS Medicare Secondary Payer guidance |
| Medicaid plus other coverage | Medicaid is generally the payer of last resort. | CMS Medicaid third-party liability rules |
| Auto accident with MedPay or PIP | State law and policy language control. In no-fault states, PIP often pays first for covered medical bills and lost wages. | State department of insurance; policy contract |
For property claims, “primary” usually means the policy directly insuring the damaged property pays before any excess or umbrella policy.
An umbrella policy typically starts only after the underlying policy’s stated limits are exhausted. Check the declarations page and “other insurance” clause.
A claimant should document the date of loss, policy numbers, names of all insurers, the insured person’s employment status, and whether Medicare or Medicaid is involved.
For auto or liability claims, add the police report, photos, witness information, repair estimates, and medical bills.
Caution: do not assume a secondary policy will pay your deductible, denied services, or out-of-network charges. Rules vary by state and plan.
Verify coordination rules with the plan document, CMS, the NAIC-based state regulation, or the state department of insurance before relying on coverage.
Documents claimants need to prove coverage order
Coverage order disputes are usually document disputes. The claimant must show which policy was active on the date of service or loss, what each policy covers, and whether a law, plan rule, or coordination rule makes one insurer pay first.
Do not rely on an insurance card alone. Cards often prove enrollment, not payment order.
For health coverage, auto no-fault, workers’ compensation, Medicare, and dependent coverage, the deciding document is usually the policy, plan, or official eligibility record.
Claimants should gather documents that prove four points: identity, active coverage dates, policy terms, and any rule that changes payment priority.
The Centers for Medicare & Medicaid Services says Medicare pays secondary in many situations covered by the Medicare Secondary Payer rules, including certain group health plan, liability, no-fault, and workers’ compensation cases.
Check CMS’s Medicare Secondary Payer guidance for the current rule set.
| Document | What it proves | Primary source to verify |
| Policy declarations page or certificate of coverage | Named insured, policy number, effective dates, covered vehicle/person/property | Insurer-issued policy documents |
| Summary Plan Description or Evidence of Coverage | Plan type, exclusions, coordination language, subrogation or reimbursement terms | Employer plan administrator or insurer |
| Eligibility or benefits verification dated for the service/loss date | Whether coverage was active on the exact date at issue | Insurer eligibility unit, CMS, state Medicaid agency |
| Explanation of Benefits (EOB) or Medicare Summary Notice | Who processed first, what was denied, and why | Insurer or CMS Medicare notices |
| Accident or employer report | Whether workers’ compensation, auto no-fault, or liability coverage may be primary | Employer, police report, adjuster file |
| Court order, custody order, or Qualified Medical Child Support Order | Dependent coverage responsibility when parents disagree | Court record or plan administrator |
For dependent children covered by both parents’ plans, many group and individual health policies use the NAIC coordination of benefits “birthday rule,” which looks at the month and day of the parents’ birthdays, not the year.
Some plans follow other valid rules, especially if a court order exists. Confirm the controlling rule in the plan document and with the state department of insurance.
- Request the full policy or certificate, not only an ID card.
- Match every document to the exact date of treatment, accident, or loss.
- Keep denial letters, EOBs, and claim numbers from every insurer.
- If Medicare or Medicaid is involved, verify status directly with CMS or the state Medicaid agency.
If records conflict, do not assume a provider or adjuster is correct. Ask the insurer for the written basis for its coverage-order decision and compare it with CMS rules, NAIC model guidance, and state insurance department materials.
A wrong filing order can delay payment or trigger repayment demands.
When Medicare or Medicaid changes priority
Medicare and Medicaid do not always pay in the same order as private insurance. Priority depends on federal coordination rules, employer size, eligibility reason, and whether another insurer has a legal duty to pay first.
A claimant should not assume government coverage is primary.
Check the plan document, the Medicare Secondary Payer rules from CMS, and state Medicaid coordination rules through the state Medicaid agency or state department of insurance before submitting or appealing a claim.
For Medicare, CMS says Medicare is secondary in several common situations. The most important triggers are current employment coverage, age, disability, and end-stage renal disease, or ESRD.
| Situation | Who pays first | Source |
| Age 65+ with employer group health plan from current employment, employer has 20 or more employees | Group health plan first, Medicare second | CMS Medicare Secondary Payer guidance |
| Under 65 and entitled to Medicare due to disability, covered by a large group health plan from current employment, employer has 100 or more employees | Large group health plan first, Medicare second | CMS Medicare Secondary Payer guidance |
| ESRD, first 30 months of Medicare eligibility or entitlement | Group health plan first, Medicare second during the 30-month coordination period | CMS Medicare Secondary Payer guidance |
After the ESRD coordination period ends, Medicare usually becomes primary if no other Medicare Secondary Payer rule applies.
A claimant should document the ESRD effective date because the 30-month period is a federal rule and can change who owes the bill first.
Medicaid works differently. Federal law generally makes Medicaid the payer of last resort, meaning Medicaid pays after other liable coverage. CMS describes this rule in Medicaid third-party liability guidance, but state procedures can differ.
- Report all other coverage, including auto, workers’ compensation, employer plans, and Medicare.
- Keep the denial, explanation of benefits, or payment record from the primary plan.
- Save proof of eligibility dates, employer size, and whether coverage came from current employment.
- For Medicaid, check the state Medicaid agency’s coordination-of-benefits rules and any managed care handbook.
Medicare also has strict reporting and recovery rules. If Medicare paid conditionally when another payer should have paid first, CMS can seek repayment. Acting on a guess can create bills, delays, or overpayment demands.
Verify the rule with CMS, the state Medicaid agency, or the state department of insurance.
State rules that can change primary coverage
Primary coverage does not always follow the same rule in every state.
State insurance law can change who pays first for auto claims, health claims, no-fault benefits, and workers’ compensation-related treatment, so a claimant should verify the rule with the state department of insurance and the policy itself.
The key point is practical: the policy that pays first may not be the policy the claimant expects.
A wrong claim order can delay payment, trigger denials, or leave the claimant responsible for deductibles, copays, or unreimbursed expenses until coordination is sorted out.
Auto insurance is one of the clearest examples.
The Insurance Information Institute states that 12 states have no-fault auto insurance systems: Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania, and Utah.
In those states, a driver’s own personal injury protection may pay first for covered medical expenses after a crash, subject to state rules and policy terms.
That does not mean every injury or every expense is fully covered. No-fault rules, verbal or monetary injury thresholds, required forms, and time limits vary by state.
A claimant should check the state department of insurance and the declarations page for the exact benefit, exclusion, and deadline.
| Issue | State rule that may control | Primary source to check |
| Auto crash medical bills | No-fault or PIP may pay before liability coverage in certain states | State department of insurance; Insurance Information Institute state summaries |
| Health plan coordination | State insurance rules may apply to fully insured plans, but not necessarily self-funded ERISA plans | State department of insurance; plan document; U.S. Department of Labor for ERISA plans |
| Medicare secondary payer | Federal MSP rules can override state practice when Medicare is involved | CMS Medicare Secondary Payer guidance |
| Dependent child coverage | Birthday rule is common, but state rules and court orders can change it | NAIC model guidance; state department of insurance; plan documents |
For health insurance, coordination can split by plan type. State regulators generally oversee insured policies sold in the state, while many employer self-funded plans are governed under ERISA.
That distinction matters because the same state rule may not control both plans. The claimant should collect the summary plan description, ID cards, and coordination-of-benefits notices.
When Medicare is involved, federal law matters first. CMS says Medicare is usually the secondary payer when another insurer has primary responsibility, including many workers’ compensation, liability, and no-fault situations.
A claimant should keep accident reports, settlement documents, explanation of benefits forms, and any conditional payment notices from Medicare.
Dependent coverage can also change by state and plan.
The NAIC’s coordination-of-benefits model uses the “birthday rule” in many cases, meaning the parent whose birthday falls earlier in the calendar year pays first, but court orders and plan-specific exceptions can override that rule.
Do not rely on a general article alone; verify with the insurer and the controlling regulator.
What the editorial team reviewed
We did not claim first-hand insurer testing for this section because primary-versus-secondary coverage depends on plan language, state rules, and claim facts.
We limited this review to verifiable public sources and flagged the points that must be checked against the controlling document before a claim is filed.
We focused on who pays first, what a policy typically excludes from primary payment, and what documents a claimant must keep.
Readers should not rely on a general explainer alone where delayed payment, denied claims, or Medicare mistakes could create bills or collection risk.
We checked Medicare coordination rules against CMS and Medicare.gov.
CMS states Medicare is generally secondary for a worker age 65 or older when covered through current employment by an employer with 20 or more employees, and secondary for disability-based Medicare when the employer has 100 or more employees.
We also verified the End-Stage Renal Disease rule from Medicare.gov. Employer group health coverage pays first during a 30-month coordination period, then Medicare usually pays first after that period ends, subject to the plan and eligibility facts.
We confirmed that Medicare does not pay first when another responsible payer exists for injury-related care.
CMS identifies workers’ compensation, liability insurance, and no-fault insurance as primary to Medicare when they are responsible for the bill.
We checked Medicaid’s role through Medicaid.gov and CMS materials. Medicaid is generally the payer of last resort, which means other health coverage must be billed first before Medicaid pays, if Medicaid covers the service at all.
| Scenario reviewed | Who usually pays first | Primary source |
| Worker 65+ with employer coverage from current employment, employer has 20+ employees | Group health plan | CMS / Medicare.gov |
| Disabled Medicare beneficiary with current-employment group plan, employer has 100+ employees | Group health plan | CMS / Medicare.gov |
| ESRD during first 30 months of coordination | Group health plan | Medicare.gov |
| Workers’ compensation, liability, or no-fault claim | That insurer, if responsible | CMS Medicare Secondary Payer guidance |
| Medicaid with other valid coverage | Other coverage first | Medicaid.gov / CMS |
We did not assign a universal rule for two private health plans because that varies.
State insurance departments and plan contracts control coordination of benefits details, including dependent rules such as the birthday rule, NAIC-based provisions, and exceptions for court orders or divorce decrees.
A claimant should document the policy declarations page, member ID cards, Explanation of Benefits forms, accident reports, employer size, employment status, effective dates, and any court order affecting dependent coverage.
If the case involves Medicare or Medicaid, the claimant should also keep agency letters and report changes promptly.
- Check the policy’s coordination-of-benefits clause.
- Verify state-specific rules with the state department of insurance.
- Verify Medicare order-of-payment rules with CMS or Medicare.gov.
- Do not assume an auto, liability, or workers’ compensation carrier will pay without a formal claim record.
Frequently Asked Questions
Which insurance is primary when a person has two health plans?
Primary insurance pays covered claims first, and secondary insurance may pay some remaining eligible costs after the primary plan processes the bill.
Which plan is primary depends on coordination of benefits rules in the policy and state rules; the National Association of Insurance Commissioners says plans use coordination rules to avoid duplicate payments.
So the member should verify the order with both insurers before treatment.
Which insurance is primary for a child covered by both parents’ health plans?
Many employer and group health plans use the “birthday rule,” meaning the parent whose birthday falls earlier in the calendar year usually has the primary plan for the child, according to the National Association of Insurance Commissioners.
This is not universal, and court orders, custody arrangements, or specific plan language can override it, so parents should check the actual plan documents and any legal order before relying on that rule.
Is Medicare primary or secondary to employer insurance?
It depends on the employer size and the reason the person has Medicare.
Medicare states that for people age 65 or older with group health coverage from current employment, the employer plan generally pays first if the employer has 20 or more employees, while Medicare generally pays first for smaller employers.
Because exceptions apply, the person should confirm with Medicare and the group plan before delaying enrollment or treatment.
Related Reading
- What Insurance Does Walgreens Accept?
- Uninsured and Underinsured Motorist Coverage, Explained
- Does Health Insurance Cover Injuries From a Car Accident
- How Insurance Subrogation Works After an Injury Settlement
- What Insurance Company Covers Mounjaro?
- Med-Pay vs PIP: Which One Pays Your Medical Bills After a Crash
- Health Insurance Liens on Personal Injury Settlements
- All Blog Guides
- Centers for Medicare & Medicaid Services – Medicare Secondary Payer
- Medicare.gov – Coordination of benefits
- California Department of Insurance – Coordinating Your Health Coverage
- National Association of Insurance Commissioners (2023)
- HealthCare.gov – Health coverage if you're turning 65 or eligible for Medicare
- Cigna Healthcare (2024)