
Bottom line: Neap annuity payments generally cannot be sold if “NEAP” means the National Electrical Annuity Plan, because qualified retirement plan benefits are typically protected from assignment or transfer.
You may be able to take permitted distributions under plan rules. Check NEAP documents and consult a tax or benefits professional before acting.
Can I Sell My Neap Annuity is answered no for most participants because NEAP is a retirement plan benefit, not a transferable structured settlement payment stream.
The National Electrical Annuity Plan is an ERISA-covered defined contribution plan for eligible electrical industry workers, according to NEAP plan materials.
Participants generally must follow plan distribution rules, tax rules, and spousal-consent requirements before accessing money. Selling, assigning, or pledging retirement benefits can be restricted by federal law and plan documents.
Do not rely on an article alone; check the current NEAP Summary Plan Description and speak with a qualified tax or benefits professional.
What a NEAP annuity is
A NEAP annuity usually refers to the National Electrical Annuity Plan, a multiemployer defined contribution retirement plan for workers in the electrical industry.
It is not the same thing as a structured settlement annuity, and that difference matters before anyone assumes it can be sold for cash.
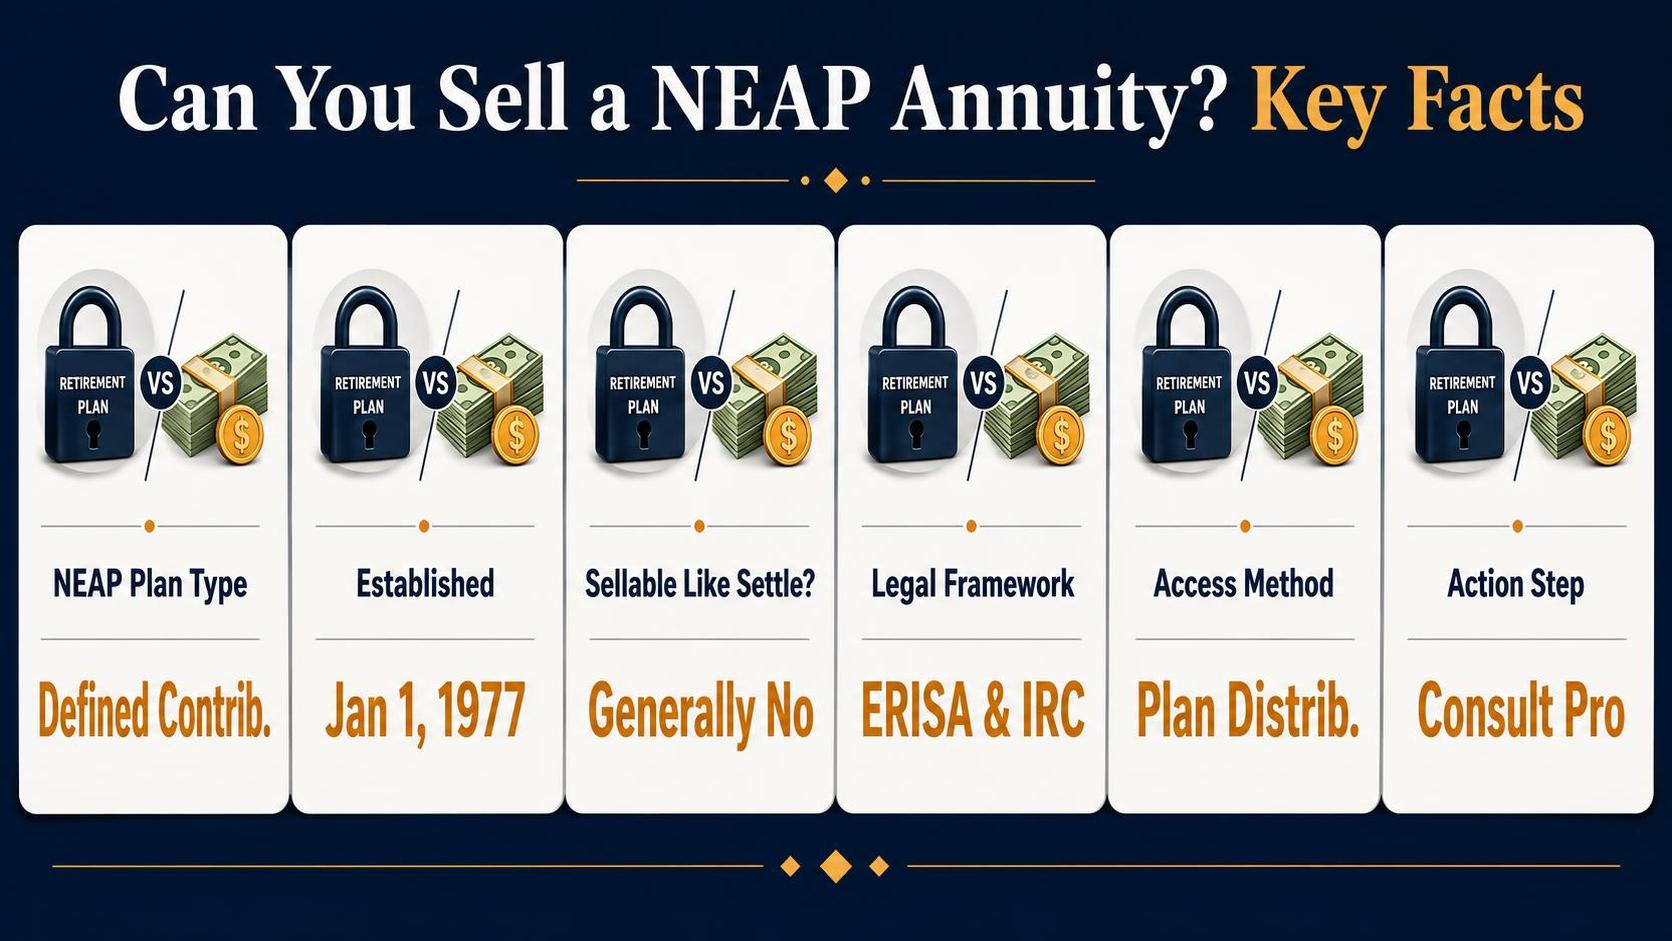
The National Electrical Annuity Plan states that it was established on January 1, 1977.
The plan is sponsored through the National Electrical Benefit Fund family of benefits and is designed to receive employer contributions negotiated under collective bargaining agreements and other approved participation arrangements.
NEAP is a defined contribution plan, not a pension promising a fixed monthly amount for life.
That means the value depends on contributions, investment performance, fees, and distribution choices allowed under the plan’s governing documents and federal law.
| Feature | NEAP annuity | Structured settlement annuity |
| Typical source of funds | Employer contributions under labor agreements, according to the National Electrical Annuity Plan | Payments funded after a lawsuit settlement, according to the Internal Revenue Service rules on structured settlements |
| Plan type | Defined contribution retirement plan, according to NEAP | Annuity contract used to make settlement payments, commonly court-supervised when transferred under state law |
| Can it usually be sold? | Often no direct “sale” like a settlement transfer; access depends on plan distribution rules and tax law | Sometimes, but only through a legal transfer process in many states |
| Main legal framework | ERISA and Internal Revenue Code retirement-plan rules | State structured settlement protection acts and tax rules under 26 U.S. Code Section 5891 |
The plan’s official participant materials explain that benefits are generally paid when a participant has a distributable event, such as retirement or another qualifying separation condition under the plan.
That is why a NEAP balance is usually discussed in terms of distributions, rollovers, or annuity payment options, not a private sale.
A practical caution is necessary here. Acting on the wrong assumption could trigger taxes, penalties, or a denied transaction, because retirement-plan money follows different rules than settlement payments.
Check the National Electrical Annuity Plan’s current Summary Plan Description and, if taxes are involved, IRS guidance before making any move.
- Established: January 1, 1977, according to the National Electrical Annuity Plan.
- Plan category: defined contribution, according to NEAP participant materials.
- Relevant tax law for retirement plans: Internal Revenue Code retirement-plan rules.
- Relevant transfer tax rule for structured settlements: 26 U.S. Code Section 5891.
Can you sell a NEAP annuity
Usually, no. If “NEAP annuity” means a benefit from the National Elevator Industry Annuity Plan, it is generally a qualified retirement plan benefit, not a structured settlement payment stream that can be assigned to a factoring company.
The key issue is control. Employer retirement-plan benefits are usually paid only under the plan’s distribution rules, and anti-assignment rules often block a direct sale to a third party.
Check the current NEAP plan documents and distribution forms before acting.
A NEAP benefit is typically handled through a distribution, rollover, or periodic payout election under the plan, not through a private sale contract.
That matters because tax treatment and access rules come from federal retirement-law rules and the plan administrator’s procedures.
| Issue | What the rule says | Source |
| Direct “sale” of plan payments | Qualified retirement plan benefits are generally controlled by the plan and federal law, so they are usually not sold like structured settlement payments. | U.S. Department of Labor ERISA framework; plan documents control benefit payment terms. |
| Cash paid to participant instead of direct rollover | 20% federal income tax withholding generally applies to eligible rollover distributions paid to the participant. | IRS, “Retirement Topics – Mandatory Withholding” and rollover guidance. |
| Early access tax risk | A 10% additional tax may apply to distributions taken before age 59½ unless an exception applies. | IRS Publication 575 and IRS early-distribution rules. |
| Rollover deadline | An indirect rollover generally must be completed within 60 days. | IRS rollover rules. |
| Required minimum distributions | RMDs generally begin at age 73 for affected taxpayers under current federal rules. | IRS retirement plan and IRA required minimum distribution guidance. |
If a participant needs cash, the realistic path is usually one of these plan-permitted options, if available:
- Lump-sum distribution after a triggering event such as retirement or separation from service.
- Direct rollover to an IRA or another eligible retirement plan.
- Installment or annuity-style payouts offered by the plan.
Do not assume a buyer can purchase future NEAP payments. A failed transfer attempt can waste fees and time, and a taxable distribution can create withholding and possible penalties.
Verify the exact NEAP plan terms with the administrator and confirm tax consequences with a CPA or tax attorney before signing anything.
NEAP rules on assignments and transfers
In most cases, a NEAP annuity cannot be sold or assigned like a private contract. NEAP is an employer-sponsored retirement plan, and plans of this type are usually controlled by federal anti-assignment rules under ERISA and the Internal Revenue Code.
The practical result is narrow: a participant usually cannot transfer plan rights to a buyer, use the account as collateral, or sign over future payments at will.
Before acting, check the current NEAP summary plan description and distribution forms, because plan language controls the transaction details.
ERISA section 206(d)(1) requires each covered pension plan to provide that benefits may not be assigned or alienated. The Internal Revenue Code mirrors that rule in section 401(a)(13).
Those two federal rules are the main reason a sale of an in-plan NEAP benefit is usually not permitted.
For readers asking, “Can I sell my NEAP annuity?” the key distinction is between an in-plan benefit and money already distributed.
While funds remain inside the plan, anti-alienation rules generally block a voluntary sale to a third party.
Plans in this category often recognize only limited exceptions allowed by law. Common examples include a qualified domestic relations order, certain federal tax levies, and other narrow legal processes specifically authorized under federal law.
| Rule or limit | What it means | Source |
| Assignment/alienation ban | Plan benefits generally cannot be sold, assigned, pledged, or transferred to another person | ERISA §206(d)(1); Internal Revenue Code §401(a)(13) |
| QDRO exception | A domestic relations order can assign benefits only if it qualifies under federal law | ERISA §206(d)(3) |
| Indirect rollover deadline | An eligible rollover distribution paid to the participant must generally be rolled over within 60 days to stay tax-deferred | IRS, rollover rules under IRC §402(c) |
| Mandatory withholding on eligible rollover distributions | If paid to the participant instead of sent by direct rollover, the payer must generally withhold 20% for federal income tax | IRS, “Retirement Topics – Rollovers” and IRC §3405(c) |
If NEAP permits a distribution, transfer options are usually limited to tax-law routes, not sales. The common permitted move is a direct rollover to an IRA or another eligible employer plan, if the receiving plan accepts it.
- A direct rollover is not a “sale.” It is a tax-qualified transfer.
- A cash distribution can trigger taxes, and if the participant is under age 59½, an additional 10% tax may apply unless an exception applies.
- State structured-settlement transfer laws usually do not override ERISA anti-alienation rules for a retirement plan.
Caution: do not sign a purchase agreement based only on marketing claims. Verify the current NEAP plan document, the summary plan description, and IRS rules first, or a transaction could fail and still create tax or legal problems.
Court approval for annuity sales
If the “annuity” is part of a structured settlement, a sale usually is not final until a court signs a transfer order. That is the key protection layer under state structured settlement laws and the federal tax rules in 26 U.S.C. § 5891.
If it is a standard retirement or income annuity, court approval often is not the issue. The first issue is the contract itself, because many annuities restrict assignment or do not allow payment rights to be sold at all.
For structured settlement payments, the buyer normally files a petition in state court and asks a judge to approve the transfer.
The judge usually reviews the purchase agreement, disclosure statement, payment history, and whether the transfer is in the seller’s best interest, including support for dependents.
The federal rule matters because 26 U.S.C. § 5891(a) imposes a 40% excise tax on the “factoring discount” of a structured settlement transfer unless the deal has a “qualified order.” A qualified order is generally a state.
Court or responsible administrative order described in 26 U.S.C. § 5891(b).
| Requirement | Specific fact | Source |
| Federal penalty without proper approval | 40% excise tax on the factoring discount | 26 U.S.C. § 5891(a) |
| Type of approval needed | 1 qualified order from a state court or responsible administrative authority | 26 U.S.C. § 5891(b) |
| New York disclosure timing example | Disclosure statement must be provided at least 10 days before signing | N.Y. Gen. Oblig. Law § 5-1703 |
| Florida disclosure timing example | Disclosure statement must be provided at least 3 business days before signing | Fla. Stat. § 626.99296(4) |
State procedures differ, so timing and paperwork can change depending on where the payee lives. Some courts schedule a hearing. Others decide on written filings.
Check the exact statute, local court rules, and any original settlement order before signing anything.
A judge can deny the transfer. Common reasons include unfair pricing, missing disclosures, signs of hardship exploitation, or conflict with the original settlement terms.
The National Association of Settlement Purchasers and state statutes also note that independent professional advice may be addressed or waived only under specific statutory language.
Caution: Do not assume court approval is automatic. Selling payment rights can permanently reduce future income.
Before acting, verify the contract, the state statute, and the court process with the primary documents or a qualified attorney in the relevant state.
Taxes before selling NEAP payments
Taxes are a key issue before trying to sell or cash out NEAP payments. In many cases, payments from a union or employer annuity plan are taxed under retirement-plan rules, not under the rules used for selling structured settlement payments.
A plain caution applies here: tax treatment depends on the plan document, the source of contributions, and the way money is paid out. A reader should verify the NEAP plan terms and the latest IRS guidance before acting.
If NEAP benefits come from a qualified retirement plan, distributions are usually taxed as ordinary income in the year received, according to IRS Publication 575 and Publication 590-A/590-B.
That means the payment is added to taxable income and taxed at the recipient’s federal income tax rate.
If the payment is made directly to the participant instead of rolled to another qualified plan or IRA, the payer generally must withhold 20% for federal income tax on an eligible rollover distribution, according to IRS rules on retirement plan distributions.
That 20% is withholding, not the final tax bill.
If the recipient is under age 59½, the IRS generally imposes an extra 10% tax on early distributions unless an exception applies.
IRS Publication 575 lists exceptions, which can include some disability cases, certain substantially equal periodic payments, and other narrow situations.
State taxes can also apply. State income tax treatment varies, so a reader should check the state department of revenue or a tax professional rather than assume the federal rule is the full cost.
| Tax item | General federal rule | Source |
| Tax on taxable distribution | Ordinary income rates apply | IRS Publication 575 |
| Mandatory withholding on eligible rollover distribution paid to participant | 20% | IRS retirement plan distribution rules |
| Additional tax for early distribution before age 59½ | 10% | IRS Publication 575 |
One more issue matters: if NEAP is an ERISA-governed retirement benefit, anti-assignment rules may limit or block a sale to a third party.
If that is true, the practical tax question may be about a permitted distribution or rollover, not a private sale.
- Ask the plan administrator whether the benefit is assignable.
- Ask whether the payment is eligible for direct rollover.
- Confirm how much of the distribution is taxable.
- Check whether any early-distribution exception applies.
The risk is simple. A transaction that looks like quick cash can trigger withholding, ordinary income tax, a possible 10% penalty, and state tax at the same time.
Risks of selling retirement income
Selling annuity payments can solve a short-term cash need, but it often reduces lifetime income by far more than the check suggests. The main risks are a steep discount, taxes or penalties, and losing inflation-resistant retirement cash flow.
Caution: a sale can be hard to reverse. Readers should confirm tax treatment, contract terms, and state approval rules with the annuity issuer, a tax professional, and, if required, the court record in their state.
The biggest risk is the discount rate used to value future payments. Consumer advocates and court records commonly show effective discount rates in the high single digits to the mid-teens, which can sharply cut the present value paid to the seller.
| Example: future payments sold | Figure | Source/meaning |
| Total future payments | $100,000 | Illustrative face amount for comparison |
| Present value at 9% | About $64,000 | Time-value math using a 9% annual discount rate |
| Present value at 15% | About $50,000 | Time-value math using a 15% annual discount rate |
| Income loss versus face amount | About $36,000 to $50,000 | Difference between $100,000 due later and cash now |
Inflation adds another risk. The U.S. Bureau of Labor Statistics reported 3.4% CPI-U inflation for 2023. If retirement costs keep rising, fixed income sold today may be expensive to replace later.
Taxes can also turn a sale into a costly mistake. The IRS says amounts received from an annuity that exceed the investment in the contract are generally taxable.
If the owner is under age 59½, taxable amounts may also face a 10% additional tax under Internal Revenue Code Section 72(q), unless an exception applies.
Contract restrictions matter. Many annuities are not freely assignable, and deferred annuities often impose surrender charges.
According to LIMRA, U.S. annuity sales reached a record $385.4 billion in 2023, showing how common these products are, but each contract can differ materially on transfer rights and penalties.
- Longevity risk: Less guaranteed income later if the seller lives longer than expected.
- Benefit loss: Death benefits or guaranteed minimum features may be reduced or forfeited.
- Public-benefit risk: A lump sum can affect SSI or Medicaid eligibility. Rules are fact-specific; check the administering agency.
- Fraud risk: The Federal Trade Commission warns consumers to verify buyers, fees, and promises before signing financial contracts.
The practical test is simple: compare the net cash offered, all taxes and fees, and the income being given up. If any number is unclear, pause and get the original contract and a written payoff analysis before acting.
Alternatives to selling NEAP benefits
Selling future NEAP payments is not the only way to raise cash. Before giving up long-term income, compare options that preserve retirement benefits or reduce the amount needed now.
Start with the plan documents. The National Electrical Annuity Plan’s summary materials and distribution forms control what payment choices, timing rules, and beneficiary options apply, and those terms matter more than any generic advice.
One alternative is delaying the transaction and using a short-term bridge source instead. That can cost less than permanently transferring annuity rights, especially because a sale usually trades long-term value for immediate cash.
| Alternative | Verified figures | Why it may fit better than a sale |
| 401(k) loan, if available | The IRS says a plan may let participants borrow the lesser of $50,000 or 50% of the vested account balance. Source: IRS Topic No. 424, “401(k) plans.” | It can provide liquidity without permanently assigning future annuity payments. Check first because not every employer plan permits loans. |
| Credit union payday alternative loan | NCUA rules cap PAL I at $200 to $1,000 for 1 to 6 months, with an application fee up to $20. PAL II can be up to $2,000 for 1 to 12 months. The maximum APR for both is 28%. Source: National Credit Union Administration. | For a smaller emergency, the dollar amount may be enough without giving up retirement income for years. |
| Hardship relief with creditors | The CFPB advises borrowers to ask lenders, servicers, hospitals, and utility providers about hardship programs, payment plans, or fee waivers. Source: Consumer Financial Protection Bureau. | Reducing or postponing bills can solve a cash crunch without taking on a new long-term loss. |
If the need is medical or household-related, ask for a structured payment plan first. Hospitals, utilities, and mortgage servicers often have hardship or loss-mitigation options, but terms vary.
Check the provider’s written program rules before agreeing.
If retirement cash flow is the issue, review whether adjusting other assets can cover the gap. The IRS says required minimum distributions generally begin at age 73 for many retirement accounts, but annuity plan rules differ.
Source: IRS retirement topics.
- Request the NEAP summary plan description and current distribution forms.
- Ask a tax professional whether another account offers a lower-cost withdrawal or loan option.
- Compare the total dollars kept under each option, not only the cash received today.
Caution: selling annuity rights can be hard to reverse and may reduce lifetime retirement security. Do not act on a quote alone; verify plan rules, taxes, fees, and any court-approval requirements with the primary source and a qualified adviser.
What Coin Abul independently reviewed
Coin Abul reviewed public-source material relevant to whether a NEAP annuity can be sold. The key issue is whether the benefit is still inside an employer retirement plan or has already been paid out into a separate contract.
That distinction matters because anti-assignment rules usually block sales of benefits held in a qualified plan.
A reader should verify the current NEAP plan document and personal distribution status before acting, because a mistake here can be costly and hard to reverse.
| Source reviewed | Specific citation | Why it matters |
| ERISA anti-alienation rule | ERISA §206(d)(1), codified at 29 U.S.C. §1056(d)(1) | Qualified retirement benefits generally cannot be assigned or alienated while held in the plan. |
| Internal Revenue Code qualification rule | IRC §401(a)(13) | Tax-qualified plans generally must restrict assignment to keep qualified status. |
| Federal tax on early distributions | IRC §72(t) | A 10% additional tax can apply to certain early retirement-plan distributions, depending on age and facts. |
| Required minimum distribution age | IRS explains current RMD age is 73 for many account holders after SECURE 2.0 changes | Distribution timing rules affect when money can leave a plan lawfully. |
Based on those sources, the strongest fact is this: if the NEAP benefit remains inside the National Elevator Industry Annuity Plan, a direct sale to a settlement-funding or factoring company is usually not available.
ERISA and the tax code generally require anti-assignment treatment for qualified plan benefits.
Coin Abul also reviewed how retirement-plan distributions differ from structured settlements. Structured settlement transfers are commonly reviewed under state transfer statutes and court approval standards.
Retirement-plan annuities are different products with different legal rules.
That means many articles about “selling annuity payments” do not fit a NEAP benefit.
If the benefit has already been distributed and converted into an individual annuity contract, the contract language controls next, including any anti-assignment clause, surrender schedule, or commutation limits.
- NEAP plan status matters first: in-plan benefits are usually not saleable.
- Post-distribution annuity contracts may allow limited options, but only if the contract permits them.
- A cash-out can trigger income tax, and sometimes the 10% additional tax under IRC §72(t), if no exception applies.
- State law may matter after distribution, but it does not override ERISA plan restrictions inside the plan.
Caution: do not sign transfer papers based on marketing alone.
Check the current NEAP summary plan description, distribution election forms, and the insurer’s contract, then confirm tax consequences with a qualified attorney or CPA using the primary documents.
Frequently Asked Questions
Can I sell my Neap annuity?
It depends on what “Neap annuity” means in the contract and how the payments are structured.
If it is a structured settlement or another annuity with transfer restrictions, a sale may require court approval or may be barred by the contract, so the owner should review the annuity documents and confirm details with the issuer before acting.
What if the annuity is a structured settlement annuity?
Structured settlement payment rights usually cannot be transferred freely because state structured settlement protection laws often require a judge to approve the sale as in the payee’s best interest.
The consumer should not sign a transfer agreement based on marketing alone because court approval is not automatic and the final net amount can be much lower after fees and discounting.
Can an annuity owner sell only part of the payments instead of the whole annuity?
In some transactions, a seller may transfer only selected future payments rather than all remaining payments, but that depends on the contract terms and applicable state law.
The owner should ask for a written disclosure showing exactly which payments would be assigned and what cash amount would be received, because a partial sale can still reduce long-term income materially.
Will selling an annuity trigger taxes or penalties?
It can, depending on the annuity type, the owner’s age, and whether the transaction is treated as a sale, surrender, or taxable distribution under IRS rules.
The Internal Revenue Service explains that annuity distributions can be taxable and may face an additional tax before age 59½ in some cases, so the owner should verify tax treatment with a CPA or tax attorney before signing.
How can someone check whether a buyer’s offer is fair?
The practical step is to compare the lump-sum offer against the present value of the future payments and review all fees, discount rates, and deductions in writing.
A reader should get multiple quotes and, for structured settlements, read the court disclosure package carefully, because once payment rights are transferred the loss of future income can be hard or impossible to reverse.
Related Reading
- Structured Settlement Sale
- Structured Settlement Buyer – What You Need to Know
- What Is A Structured Annuity?
- Structured Settlement Annuities for Minors
- Structured Settlement Collection Agency
- AIG Structured Settlements – The Truth You Didn't Know
- Structured Settlement Debt Collector
- Structured Settlement Annuity Companies
- All Blog Guides