
Key takeaway: Buy structured settlement payments only through a court-approved transfer from the original recipient.
In most U.S. states, a judge must find the sale is in the recipient’s best interest under structured settlement protection laws. Buyers usually pay a discounted lump sum, so sellers receive less than the full future payment value.
Buy Structured Settlement is a transaction where a company purchases some or all future structured settlement payments for a discounted lump sum, usually after court approval.
The buyer pays less than the full future value because it advances cash now and assumes collection timing risk.
For sellers, the key issue is whether the lump sum solves a documented need without creating a larger financial problem later.
State structured settlement protection laws commonly require a judge to decide whether the transfer is in the payee’s best interest, but rules vary.
Readers should compare disclosures, fees, discount rates, tax effects, and legal requirements with qualified independent advice before signing anything.
What buying structured settlement payments means
Buying structured settlement payments means a company purchases some or all future payments from a person who already has a court-approved settlement annuity.
In exchange, the seller gets a lump sum now, and the buyer receives the assigned payments later.
This is not the same as creating a structured settlement after a lawsuit. It is a secondary-market transfer, usually reviewed under state structured settlement transfer laws and federal tax rules before money changes hands.
Most structured settlements begin after a personal injury, wrongful death, or workers’ compensation claim is resolved.
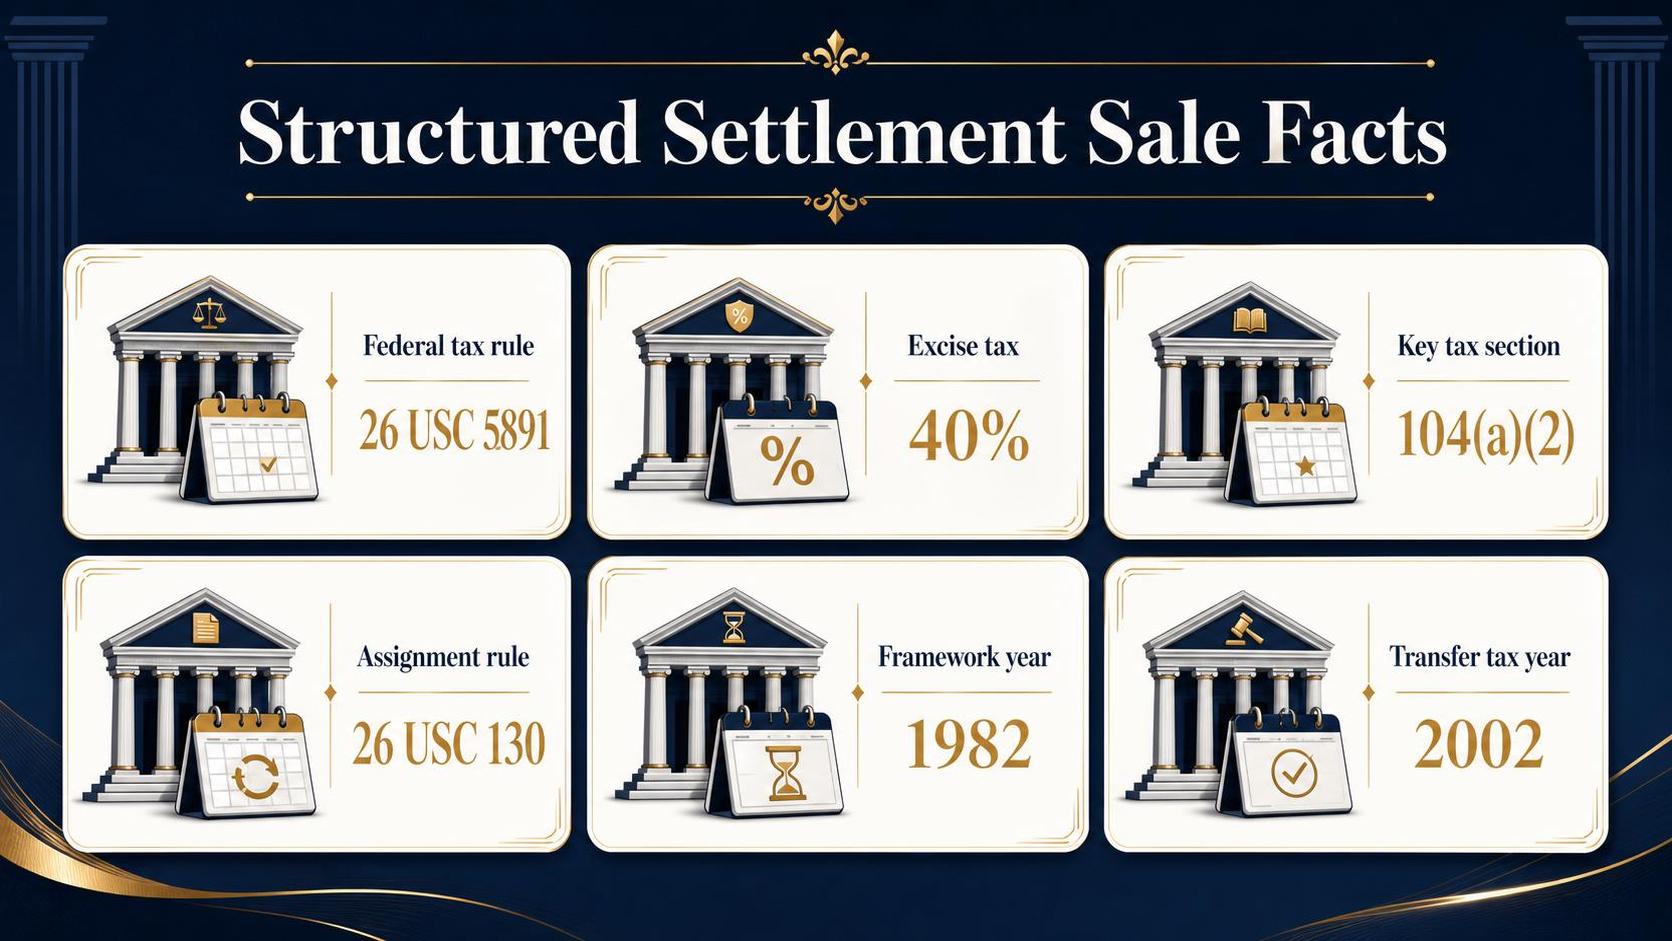
The tax treatment of the original settlement is rooted in 26 U.S.C. Section 104(a)(2), and many settlement annuities are funded through assignments under 26 U.S.C. Section 130, created by the Periodic Payment Settlement Act of 1982.
In a sale, the buyer does not usually purchase the annuity contract itself. The buyer purchases the right to receive identified payments, such as 60 monthly checks, a yearly payment, or one future lump sum.
The annuity issuer typically keeps making payments; the payee changes after approval.
Federal law adds a strong compliance rule. Under 26 U.S.C. Section 5891, enacted in 2002, a transfer without a qualified court order can trigger a 40% federal excise tax on the factoring company.
That tax rule is one reason buyers require a judge’s approval and detailed disclosures before closing.
| Rule or figure | What it means | Source |
| 1982 | Congress enacted the Periodic Payment Settlement Act, the modern federal framework for structured settlement assignments. | U.S. Congress, Periodic Payment Settlement Act of 1982; 26 U.S.C. Section 130 |
| 2002 | Congress added federal transfer-tax rules aimed at unapproved sales. | Victims of Terrorism Tax Relief Act of 2001, effective 2002; 26 U.S.C. Section 5891 |
| 40% | Excise tax applied to a transfer that lacks a qualified order. | 26 U.S.C. Section 5891(a) |
What the seller receives is usually less than the total face value of the future payments. Buyers discount for time, risk, legal costs, and profit.
The exact amount depends on the payment schedule, the annuity issuer, state law, and the buyer’s pricing.
Common reasons people sell include debt payoff, housing, medical bills, or avoiding foreclosure. Common risks include accepting too little cash, losing long-term income, and misunderstanding tax or benefit effects.
Caution: A structured settlement can be a long-term financial safeguard.
Before signing anything, compare offers, read the disclosure statement, and check the court-order and state-law requirements in the primary sources or with a qualified attorney or tax professional.
Who can buy structured settlement rights
In practice, structured settlement payment rights are usually bought by specialized factoring companies, not by ordinary consumers.
The sale is regulated because the payee is transferring future income, and federal tax law and state transfer laws can block or penalize noncompliant deals.
The key federal rule is Internal Revenue Code Section 5891.
It imposes a 40% federal excise tax on a structured settlement factoring transaction unless the transfer is approved in a qualified court or administrative order and meets state law requirements.
The typical buyer is a commercial purchaser that focuses on structured settlement transfers.
These companies review the annuity contract, the settlement terms, the payment schedule, and the payee’s state-law disclosures before asking a court to approve the transfer.
| Potential buyer | Can buy the rights? | Why |
| Structured settlement factoring company | Usually yes | These companies are set up to purchase future payments, make disclosures, and seek court approval under state transfer statutes and 26 U.S.C. § 5891. |
| Private individual investor | Usually no in practice | A private buyer usually lacks the compliance process, court paperwork, and settlement-specific underwriting used in approved transfers. |
| Annuity issuer or settlement obligor | Sometimes involved, but not usually as the buyer | These parties more often receive notice, confirm payment terms, or object under the contract or state law. |
| Broker or lead generator | No, unless it is also the actual purchaser | A marketing company may refer a seller, but the legal transferee is the entity named in the transfer agreement and court order. |
Courts usually examine whether the sale is in the payee’s best interest.
State structured settlement protection laws commonly require disclosure of the amounts being sold, the amounts being paid now, and the effective discount rate before approval.
Not every payment stream can be bought. Anti-assignment language, prior court orders, child-support liens, bankruptcy issues, or benefit eligibility concerns can limit or stop a transfer.
The annuity issuer and settlement obligor are typically entitled to notice.
A plain caution matters here: no one should assume a buyer is legitimate because it advertises online.
The safer step is to confirm the purchaser’s exact legal name in the transfer documents, verify that court approval is required in the payee’s state, and read the disclosure statement carefully.
If a reader is considering a sale, the primary sources to check are 26 U.S.C. § 5891, the payee’s state structured settlement transfer law, and the underlying settlement and annuity documents.
Those records determine who can legally buy the rights in that specific case.
How court approval protects sellers
Court approval is the main legal safeguard when someone wants to sell structured settlement payment rights.
The hearing forces an independent review before money changes hands, which helps screen out unfair pricing, missing disclosures, and transfers that could harm dependents.
This protection exists because federal tax law and state transfer statutes require it. Sellers should not rely on an advertisement or a quoted lump sum alone. The court order matters because it creates a legal checkpoint.
The core federal rule is 26 U.S.C. Section 5891.
It imposes a 40% excise tax on a structured settlement factoring transaction unless the transfer is approved in advance in a “qualified order” under a state structured settlement protection statute, according to the Internal Revenue Code.
State laws add seller protections. They usually require a written disclosure statement, a court finding that the transfer is in the seller’s best interest, and consideration of the welfare and support of dependents.
The National Association of Settlement Purchasers states that structured settlement protection laws exist in 49 states.
| Protection | What it does | Source |
| Court order | Prevents a transfer unless a judge approves it as a qualified order | 26 U.S.C. Section 5891 |
| Disclosure timing | Requires disclosure not less than 10 days before signing in many states, including New York and Texas | N.Y. Gen. Oblig. Law Section 5-1703; Tex. Civ. Prac. & Rem. Code Section 141.003 |
| Cooling-off cancellation | Allows cancellation within 3 business days after signing in California | Cal. Ins. Code Section 10139.5 |
The hearing can expose problems a seller may miss. Judges can question the discount rate, fees, family impact, and whether the seller understood alternatives.
Some courts deny transfers when the payee cannot show a genuine need or when the transaction appears unfair.
Disclosure rules are especially important.
New York and Texas require key terms, including the amounts being sold, the net amount payable, and the effective annual discount rate, to be given at least 10 days before the seller signs, according to those state statutes.
That waiting period gives time to compare offers and ask for legal or tax advice. California goes further by giving sellers the right to cancel within 3 business days after signing, according to California Insurance Code Section 10139.5.
Protection is not automatic. A judge can approve a transfer that still costs the seller substantial future value.
Before signing, compare the gross advance, all fees, and the effective annual discount rate, and confirm the exact rule in the seller’s state statute or court forms.
Pricing and discount rates buyers use
Structured-settlement buyers price a purchase by discounting future payments into a lump sum today.
The biggest driver is the discount rate, and public consumer guidance commonly describes rates in the high single digits to the high teens, depending on the case and the buyer.
The Consumer Financial Protection Bureau said buyers may apply discount rates that “typically range from 9 percent to 18 percent.” That rate is not the only deduction.
State disclosure forms usually also require separate line items for fees, commissions, and legal or filing costs, which reduce the net amount paid.
Price starts with the payment stream’s present value. A buyer looks at the size of each future payment, when it is due, the issuer’s credit quality, the court-approval timeline, and whether only part of the settlement is being sold.
A higher discount rate lowers the present value and usually lowers the seller’s cash offer.
The table below is an illustration, not a market quote. It shows the present value of one $25,000 payment due in 10 years, using the CFPB’s 9% to 18% range and standard present-value math.
Source for the rate range: Consumer Financial Protection Bureau. Source for the table figures: Coin Abul calculation using standard present-value math.
| Future payment | Time until paid | Discount rate | Illustrative present value before fees |
| $25,000 | 10 years | 9% | $10,559 |
| $25,000 | 10 years | 12% | $8,049 |
| $25,000 | 10 years | 18% | $4,784 |
That spread is why disclosures matter. On the same future payment, moving from 9% to 18% cuts the illustrated pre-fee value by $5,775. Source: Coin Abul calculation from the table above.
Federal tax law adds another pricing constraint.
Internal Revenue Code Section 5891 imposes a 40% excise tax on a structured-settlement transfer unless the transfer is approved in a qualified court order under a state structured-settlement protection act. Source: 26 U.S.C. § 5891.
- Ask for the annual discount rate, total fees, and net advance in writing.
- Compare offers on the same payment stream, not only the cash headline.
- Check the court documents and the state disclosure form before signing.
Caution: a higher cash-advance speed can mean a lower payout. Do not rely on a verbal quote alone. Review the disclosure statement and court filing, or get legal or financial advice before selling settlement payments.
State laws that affect purchases
Buying a structured settlement payment stream is not governed by contract law alone. In most cases, a transfer must satisfy both federal tax rules and a state Structured Settlement Protection Act, often called an SSPA, before a court will approve it.
That matters because state law controls the approval process, disclosures, and the judge’s “best interest” review.
A payee should not sign based on a quote alone, because a quoted price can still fail under state law or trigger tax consequences without a valid court order.
The federal backstop is strict. Under 26 U.S.C. Section 5891(a), a transfer that lacks a “qualified order” can trigger a federal excise tax equal to 40% of the factoring discount, according to the Internal Revenue Code.
| Law or rule | Specific figure | Why it matters | Source |
| Federal tax penalty without a qualified order | 40% | A buyer that closes a transfer without proper approval can face a federal excise tax equal to 40% of the factoring discount. | 26 U.S.C. Section 5891(a) |
| New York pre-signing disclosure timing | 10 days | The transferee must give the payee a separate disclosure statement at least 10 days before the payee signs a transfer agreement. | New York General Obligations Law Section 5-1703 |
| New York cancellation period | 3 business days | The payee may cancel the transfer agreement within three business days after signing, which can slow funding but adds protection. | New York General Obligations Law Section 5-1705 |
State SSPAs usually require a judge to find that the transfer is in the payee’s best interest.
Many statutes also require findings on dependents, disclosure of fees and net advance, and proof that the transfer does not violate prior court orders or the annuity contract.
Those standards are not identical from state to state.
The hearing venue, notice rules, and whether the payee must receive or waive independent professional advice can differ, so the governing statute is often the law of the payee’s home state or the state named in the settlement documents.
- Check the exact SSPA in the payee’s state before relying on any quote.
- Read the disclosure for gross amount, itemized fees, and net amount actually paid.
- Verify whether a cooling-off period or advice requirement applies.
Caution: a transfer approved in one state can still affect tax treatment, public benefits, or family finances.
A payee should confirm the current statute and court procedure with the state’s primary legal source or a qualified attorney before acting.
Risks before buying payment streams
Buying a structured settlement payment stream can produce predictable cash flow, but the risks are different from a bank product or Treasury bond.
The buyer must evaluate legal enforceability, insurer strength, tax treatment, and resale limits before pricing any stream.
Act before funding. Read the annuity contract, the assignment documents, and any court order. A mistake on ownership, anti-assignment language, or beneficiary terms can leave the buyer with a contract that pays differently than expected.
The first risk is credit exposure to the life insurer that issued the annuity.
Structured settlement payments are usually backed by an insurer’s general account, not by the U.S. government and not by FDIC deposit insurance, according to the FDIC and state guaranty associations.
| Protection example | Coverage figure | Source |
| FDIC bank deposits | $250,000 per depositor, per insured bank, per ownership category | Federal Deposit Insurance Corporation |
| California life and annuity guaranty coverage | $250,000 in present value for annuity benefits | California Life & Health Insurance Guarantee Association |
| New York life insurance company guaranty coverage | $500,000 in present value of annuity benefits, including cash surrender and withdrawal values | New York Life Insurance Company Guaranty Corporation |
Those figures are examples, not a federal guarantee. Coverage depends on state law, residency rules, and claim facts. Confirm the primary source before relying on any limit, because guaranty protection can differ materially by state.
The second risk is transferability. Many structured settlements were designed to be nonassignable.
A payment seller often needs court approval under a state structured settlement protection act, and the order may authorize only a defined set of payments.
The third risk is tax uncertainty. Periodic payments for personal physical injuries are generally excluded from gross income under Internal Revenue Code Section 104(a)(2), and qualified assignments are addressed in Section 130.
A buyer should not assume the same tax result applies after a purchase.
The fourth risk is valuation error. If the stream has inflation exposure, life-contingent terms, or a weak guaranty backstop, a headline yield can understate risk.
Review the insurer’s current ratings and the exact payment schedule before assigning any present value.
- Verify whether payments are fixed-term or life-contingent.
- Confirm the issuer, owner, payee, and beneficiary on the contract.
- Check state guaranty limits from the state guaranty association, not a sales summary.
- Get legal and tax advice before closing. Acting on a summary alone can cause permanent loss.
What the editorial team reviewed
Coin Abul did not run a live “sell my payments” transaction for this section.
Instead, the editorial team reviewed primary-source rules, public buyer disclosures, and court-approval standards to identify what a buyer of structured-settlement payments must verify before signing anything.
The review focused on documents a seller can check independently: federal tax law, state transfer-approval rules, and buyer-facing disclosures about timing, fees, and discounting.
That matters because a bad transfer can permanently reduce future income, and readers should confirm terms in the purchase agreement and court filing.
The editorial team reviewed the federal tax rule that governs transfers first.
Under 26 U.S. Code Section 5891, a transfer of structured-settlement payment rights can trigger a 40% federal excise tax unless it is approved in advance in a qualified order and meets state structured-settlement transfer law.
Source: Legal Information Institute, Cornell Law School, publishing the U.S. Code.
The team then checked the tax rules that make many structured settlements valuable in the first place.
Internal Revenue Code Section 104(a)(2) excludes qualifying personal-injury damages from gross income, and Section 130 governs qualified assignments used to fund many settlements.
Source: Internal Revenue Code, as published by the Legal Information Institute.
| Primary item reviewed | Specific fact checked | Source |
| Transfer-tax rule | 40% excise tax applies to non-qualified transfers | 26 U.S. Code Section 5891 |
| Tax treatment of damages | Personal-injury damages can be excluded from income | 26 U.S. Code Section 104(a)(2) |
| Qualified assignment rule | Section 130 sets rules for qualified assignments | 26 U.S. Code Section 130 |
The editorial team also reviewed public guidance from the Consumer Financial Protection Bureau.
The CFPB warns consumers to compare the lump sum offered with the value of the future payments being sold and to watch the effective discount rate and fees.
Source: Consumer Financial Protection Bureau consumer guidance on selling a structured settlement or annuity payments.
Because approval is usually state-specific, the team checked court-based transfer standards qualitatively rather than assigning one nationwide timeline.
Many states require a judge to find the transfer is in the seller’s best interest and that the seller received required disclosures, but the exact wording and procedure vary by statute.
Readers should verify the current law in the state named in the settlement and in the transfer petition.
- Most important check: the net lump sum after every fee, not the headline offer.
- Most important legal check: whether a court order is required before payments can be reassigned.
- Most important safety check: compare the purchase agreement with the disclosure statement line by line before signing.
Caution: selling structured-settlement payments can reduce long-term financial security. Readers should not rely on a website summary alone; they should review the actual contract, disclosure statement, and state-court filing before acting.
Questions to ask before signing
Selling structured settlement payments can convert future income into cash now, but the contract terms matter more than the advertisement.
Before signing, ask questions that expose the real price, the legal steps, and what happens if the transfer is denied.
Most transfers need court approval under a state structured settlement protection act. Federal tax law also matters: under 26 U.S. Code Section 5891, a purchaser can face a 40% excise tax if the transfer does not meet the law’s approval rules.
| Fact to confirm | Number | Source | Why it matters |
| Federal excise tax on a non-qualified transfer | 40% | 26 U.S. Code Section 5891(a) | Ask whether the buyer will obtain the court order required for a qualified transfer. |
| Federal disclosure waiting period for many consumer credit transactions | 3 business days | Truth in Lending Act rescission rule, 15 U.S.C. Section 1635; 12 CFR 1026.23 | Ask whether any cancellation right applies. Structured settlement sales usually follow state law instead, so do not assume this protection exists. |
Ask for the discount rate and the dollar amount being sold. The contract should show the payments being assigned, their total face value, the gross advance, every fee, and the net amount paid to the seller.
Ask whether fees come out of the advance or are charged separately. Request every charge in writing, including legal, filing, processing, and courier fees. If the company will not provide a line-by-line breakdown, that is a warning sign.
Ask who bears the risk if the judge denies the transfer. A buyer should explain whether the seller owes any cancellation, application, or attorney costs after a denial. That answer should appear in the written agreement, not only in a phone call.
Ask whether selling these payments affects tax treatment, Medicaid eligibility, SSI, or future budgeting.
The Internal Revenue Service generally excludes qualifying personal-injury structured settlement payments from gross income under 26 U.S. Code Section 104(a)(2), but changing the payment stream can create planning risks.
- What exact payments are being sold, by date and amount?
- What is the discount rate, and is it fixed in the contract?
- What is the net amount after all fees?
- Who pays costs if the court rejects the transfer?
- Can the seller cancel, and by what deadline under state law?
- Will this sale affect benefits, taxes, or child support obligations?
Caution: do not sign based on a verbal summary. Compare the contract with the disclosure statement and the court petition, and check your state’s structured settlement law or a qualified attorney before acting.
Frequently Asked Questions
What does it mean to buy a structured settlement?
Buying a structured settlement usually means a factoring company purchases some or all of a payee’s future payment rights in exchange for a lump sum.
Under the federal Periodic Payment Settlement Act of 1982 and state structured settlement protection laws, most transfers must be reviewed and approved by a court, so a seller should not rely on advertising alone before signing.
Is court approval required to sell structured settlement payments?
In most cases, yes.
The National Conference of State Legislatures has reported that states enacted Structured Settlement Protection Acts to require judicial or administrative review, and the exact procedure, disclosures, and standards vary by state.
So the seller should check the current statute and court rules in the state named in the settlement documents.
How do companies decide what they will pay for future settlement payments?
Buyers usually discount the future payment stream to a present-value amount, then subtract fees or costs if permitted by law.
The U.S. Government Accountability Office has found in prior reviews of structured settlement transfers that discount rates and fees can materially reduce what sellers receive, so a seller should ask for the gross advance, discount rate, itemized fees.
And net payout in writing before agreeing.
Related Reading
- AIG Structured Settlements – The Truth You Didn't Know
- What Is A Structured Settlement?
- Structured Settlement Annuity Calculator
- What Is A Structured Annuity?
- Vanguard Immediate Annuity Rates
- Structured Settlement Broker
- Structured Settlement Annuity Companies
- Structured Settlement Buyer – What You Need to Know
- All Blog Guides