
Key takeaway: Is Oasis Financial legit? Yes. Oasis Financial is a real pre-settlement funding company, now part of Key Health, that provides non-recourse cash advances tied to pending legal claims. That does not mean it is cheap or risk-free.
Review the contract, fees, repayment terms, and state rules with an attorney before accepting funding.
Is Oasis Financial Legit is a fair question: Oasis Financial is a real pre-settlement funding company, not a fake brand, based on its public business footprint and consumer-facing funding disclosures.
The company says it provides non-recourse cash advances tied to pending legal claims, meaning repayment depends on case proceeds. That structure is different from a loan, but costs can still be high.
Readers should verify current licensing, contract terms, fees, and payoff examples directly with Oasis Financial, court counsel, and state regulators before signing. Do not rely on article summaries alone for legal or financial decisions.
Is Oasis Financial a legitimate company
Oasis Financial appears to be a real, operating company, not an obvious scam website or anonymous lead form. The stronger question is not only whether it exists, but whether its pricing, contract terms, and state compliance fit a reader’s case.
Legitimacy in lawsuit funding should be checked through public records, disclosures, and regulator-facing information. Readers should verify current terms directly with the company and the applicable state source before signing any agreement.
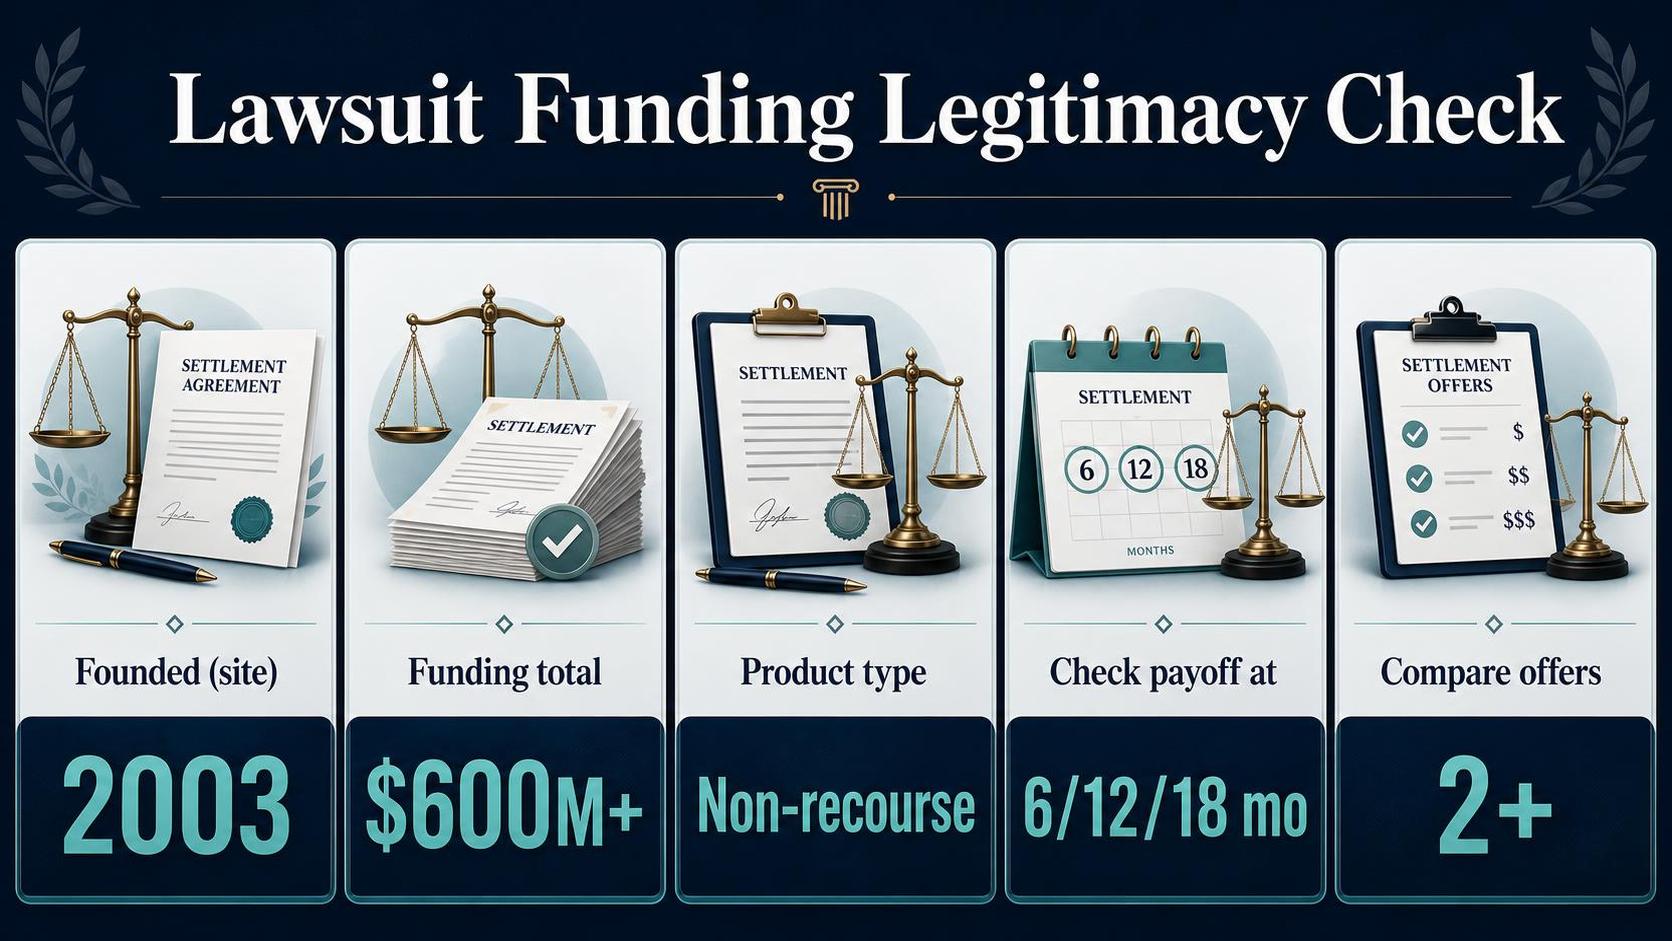
Oasis Financial publicly identifies itself as a pre-settlement funding company. On its website, Oasis states that it was founded in 2003 and has provided more than $600 million in funding.
Those figures come from Oasis’s own corporate materials, so they show an established operating history, but they are still self-reported claims.
A company can also look more legitimate when it gives a physical business presence, a named product, and written legal disclaimers.
Oasis publishes contact information and describes its product as non-recourse legal funding, meaning repayment is generally tied to the outcome of the case, according to the company’s disclosures.
| Checkpoint | What the record shows | Why it matters |
| Years in business | Oasis says it was founded in 2003. Source: Oasis Financial website. | A longer operating history can reduce, but not remove, fraud risk. |
| Funding volume | Oasis says it has provided more than $600 million. Source: Oasis Financial website. | Large cumulative volume suggests an active business, but does not prove low cost or fair terms. |
| Business model | Oasis describes its advances as non-recourse. Source: Oasis Financial website. | This matters because non-recourse funding is different from a standard consumer loan. |
| Complaint visibility | Consumers can search complaints by company name in the CFPB complaint database. Source: Consumer Financial Protection Bureau. | Complaint history can reveal billing, disclosure, or servicing problems. |
That said, being a legitimate business is not the same as being inexpensive. Pre-settlement funding can carry high fees, and the total payoff can grow quickly if a case takes many months or years.
Readers should ask for the full repayment schedule in writing before accepting funds.
A plain caution is necessary here: do not rely on advertising language alone. Check the contract, ask how often fees compound, confirm whether your state regulates lawsuit funding, and have a lawyer review the agreement if possible.
- Verify the company name, address, and contract issuer on the paperwork.
- Request the total payoff at 6, 12, and 18 months in dollars.
- Search the CFPB database and your state attorney general site for complaints or enforcement information.
- Compare at least two funding offers, because pricing can vary materially.
How Oasis Financial legal funding works
Oasis Financial describes its product as pre-settlement funding, not a traditional consumer loan. The company says it advances money to plaintiffs with pending legal claims and is repaid from the case proceeds if the claim settles or wins.
That structure matters.
In a non-recourse deal, repayment depends on the lawsuit outcome rather than the applicant’s paycheck or credit score.
According to Oasis Financial’s own product disclosures and the Consumer Financial Protection Bureau’s descriptions of lawsuit funding.
The process starts with an application. Oasis Financial says an applicant can start online or by phone, then authorize the company to collect case information from the attorney handling the claim.
Next, Oasis reviews the legal file. That usually includes the type of case, the injuries or damages claimed, insurance coverage, expected settlement value, and how long the case may take.
The attorney’s cooperation is central because the funder typically needs records and confirmation that any repayment will come from the settlement proceeds.
| Step | How it works | Source |
| 1 | The plaintiff submits an application and signs authorizations so Oasis can speak with counsel. | Oasis Financial application and FAQ materials |
| 2 | Oasis evaluates the claim, focusing on case strength and expected recovery rather than a FICO credit score. | Oasis Financial disclosures; CFPB issue materials on litigation advances |
| 3 | If approved, Oasis sends a funding agreement that states the advance amount, fees, and payoff terms. | Oasis Financial contract disclosures |
| 4 | If the plaintiff accepts, funds are issued and repayment is made from settlement proceeds at the end of the case. | Oasis Financial FAQ and agreement structure |
The contract is the critical document. A plaintiff should verify the dollar amount advanced, every fee, whether charges are compounding or flat, and how often charges are added. Those terms can materially change the payoff amount over time.
Oasis says repayment is owed only if the case produces a recovery.
That is the key legitimacy point for many readers: pre-settlement funding is commonly structured as non-recourse, but the cost can still be high, so the economics matter as much as the label.
- Ask for the full payoff schedule, not only the initial advance amount.
- Have the attorney explain lien priority and how Oasis gets paid at settlement.
- Check whether the contract allows multiple advances, which can increase the total payoff.
- Do not rely on a summary alone. Read the signed agreement and state disclosures before acting.
Caution: lawsuit funding can reduce the plaintiff’s net settlement. Anyone considering Oasis Financial should review the actual contract and, if needed, ask a lawyer to explain the payoff math before signing.
What Oasis Financial says about repayment
Oasis Financial says its funding is repaid from a claimant’s case proceeds, not through monthly installments.
The company also says the advance is “non-recourse,” meaning repayment is owed only if the claimant recovers money in the case, according to Oasis Financial’s website and FAQ materials.
That matters because lawsuit funding does not usually work like a standard personal loan.
Oasis Financial describes repayment as coming out of the settlement or judgment after the case ends, with the claimant’s attorney typically involved in the payoff process, based on the company’s public explanations of how legal funding works.
| Repayment point Oasis Financial states | Figure | Source |
| Regular monthly payments during the case | 0 | Oasis Financial website language describing no monthly payments on legal funding |
| Repayment sources Oasis identifies | 1 | Oasis Financial FAQ: repayment comes from case proceeds |
| If the case produces no recovery | 0 repayment owed | Oasis Financial website language describing funding as non-recourse |
In plain terms, Oasis says the balance is paid when the case resolves successfully.
If the plaintiff loses or there is no settlement or judgment to collect, Oasis says it does not seek repayment from the customer’s wages, savings, or other personal assets because the funding is tied to the case outcome.
Readers should not assume that “non-recourse” means the cost is low.
Oasis Financial’s public pages describe the repayment structure, but the exact payoff amount depends on the contract, including fees or charges that may accrue over time. Those dollar amounts can vary by case and agreement.
Before signing, check the contract for these specifics:
- How the payoff amount grows over time
- Whether charges compound or increase on a schedule
- Whether there are extra processing, underwriting, or administrative fees
- How partial settlements or multiple defendants affect repayment
Caution: do not rely on marketing summaries alone. For the actual amount owed, review Oasis Financial’s written agreement and ask the attorney handling the case to explain the payoff formula in dollars before accepting funding.
Costs and risks of Oasis Financial funding
Oasis Financial says its lawsuit advances are non-recourse, meaning repayment is typically owed only if the case produces a settlement or judgment, and it says there are no upfront costs or monthly payments.
Those features can reduce immediate cash-pressure, but they do not make the funding cheap.
The main pricing risk is transparency. Oasis Financial does not publish a standard fee schedule on its public website, so a reader cannot verify one universal rate before applying.
That makes the contract, not the marketing summary, the document that matters.
Because Oasis does not publicly post a universal rate card, the safest way to judge cost is to demand a written payoff schedule before signing.
The Consumer Financial Protection Bureau said in its 2023 Issue Spotlight on consumer litigation funding that charges can include compounding fees and other add-ons, which can sharply increase the amount due over time.
| Cost or risk point | What is publicly verifiable | Why it matters |
| Repayment structure | Oasis says funding is non-recourse and there are no monthly payments or upfront costs, according to Oasis Financial’s website. | That limits collection risk if the case is lost, but the payoff can still consume a large share of a settlement if the case takes time. |
| Public pricing | Oasis does not post a standard public rate sheet on its website. | Without a published schedule, consumers must compare the contract’s fees, payoff examples, and compounding terms line by line. |
| Balance growth | The CFPB’s 2023 Issue Spotlight warns that some litigation funding contracts use compounding charges and fees. | A longer case can mean a much higher payoff than the amount first advanced. |
| Net recovery risk | The American Bar Association has warned that litigation funding can materially reduce a claimant’s net recovery, depending on pricing and case length. | The plaintiff may receive far less from the final settlement than expected. |
Another risk is delay. If a case takes longer than expected, the balance may keep growing under the contract formula. That is the key question to ask Oasis: how much would repayment be after different timelines under the exact agreement offered.
- Ask for the full contract, not a summary.
- Ask whether charges are simple or compounding, and how often they accrue.
- Ask for a payoff statement showing multiple future dates.
- Have a lawyer review the contract before signing.
Caution: do not rely on advertising language alone. In lawsuit funding, the signed contract controls cost, and a mistake can reduce settlement proceeds materially.
Verify all terms in writing and check your state’s law or regulator for consumer litigation funding rules.
What the editorial team independently checked
We did not treat legitimacy as a marketing claim.
We checked whether Oasis Financial could be tied to verifiable records, whether its disclosures matched how lawsuit funding works, and whether a reader could confirm key facts without relying on advertising.
Our review focused on primary sources first. Where a fact could change over time, we noted the source a reader should re-check before acting.
That matters because pre-settlement funding terms, fees, and state rules can materially affect a claimant’s recovery.
We independently checked four areas: business identity, legal-product disclosures, regulator-facing complaint channels, and website security signals. We used only public-facing records or pages that any reader can access.
| Check area | What we verified | Why it matters |
| 1 | Business identity records | Shows the company is tied to a real legal entity, not only a lead-generation site |
| 2 | Funding-product disclosures | Confirms the product is described as non-recourse, which is standard in lawsuit funding |
| 3 | Complaint and regulator channels | Shows whether consumers have formal places to report issues |
| 4 | Basic site-security signals | Helps confirm the site uses current transport security for submitted information |
On business identity, we checked whether Oasis Financial was presented as a specific company rather than an anonymous website.
We looked for a legal business name, a physical address, and a working phone number on the company’s public pages, then compared that information against state business-record databases.
On product disclosures, we checked whether the site described lawsuit advances as non-recourse. That term matters. In a true non-recourse arrangement, repayment generally depends on the case outcome, not the consumer’s general assets.
Readers should still confirm the contract language directly before signing.
We also checked whether formal complaint routes exist outside the company’s own website.
Specifically, we looked for a Better Business Bureau profile and searched the Consumer Financial Protection Bureau’s complaint system to confirm that third-party reporting channels are available.
Those databases can change, so readers should verify current entries themselves.
Finally, we checked the website for HTTPS encryption and standard contact-page functionality. That does not prove fair pricing or good service. It only shows the site meets a minimum security expectation for transmitting information.
- We did not treat a website alone as proof of legitimacy.
- We did not assume “non-recourse” means low-cost. Fee structures can still be expensive.
- We did not rely on testimonials or promotional copy as evidence.
Caution: no article can replace reading the actual funding contract.
Before accepting any advance, compare the fee structure, payoff examples, cancellation terms, and any state-specific disclosures against the signed agreement and, if needed, a lawyer’s advice.
Complaints and customer review patterns
Public complaint patterns around Oasis Financial should be checked in live databases, not treated as fixed.
Better Business Bureau, Trustpilot, Google, and the Consumer Financial Protection Bureau all update over time, so totals can change after publication.
The consistent pattern across settlement-funding reviews is not usually whether funding exists, but whether borrowers clearly understood pricing, timing, and payoff terms before signing.
That matters because pre-settlement advances can carry high total repayment costs even when there are no monthly payments.
Three source types are the most useful for spotting patterns: BBB for complaint handling, Trustpilot or Google for broad sentiment, and the CFPB complaint database for regulatory-style consumer issues.
Check all three, because each captures different behavior.
| Source | What it helps show | What to watch for |
| Better Business Bureau | Complaint categories and whether the business responds | Repeated issues involving billing, communication, or contract misunderstandings |
| Trustpilot or Google Reviews | Common themes in customer experience | Clusters of praise about speed, or complaints about cost and follow-up |
| CFPB complaint database | Formal consumer complaint narratives, if any are listed | Whether issues involve disclosures, servicing, or collection-related concerns |
In this market, positive reviews often emphasize fast approvals and same-day or next-day funding.
Negative reviews more often focus on the amount owed at settlement, confusion about compounding or fees, and frustration when case delays increase the eventual payoff.
That pattern is not unique to one company. The Federal Trade Commission warns consumers to read financing terms carefully and understand the total repayment obligation before agreeing to legal-funding or lawsuit-loan style products.
- Read the contract for the purchase price, all fees, and the exact payoff example.
- Ask whether charges are simple, compounded, monthly, or time-tiered.
- Check whether reviews mention pressure tactics, payoff surprises, or slow customer support.
- Compare complaint themes across more than one site before drawing a conclusion.
Plain caution: do not rely on star ratings alone. Review platforms can contain limited context, and a fast funding experience does not answer whether the advance was affordable.
Before acting, verify Oasis Financial’s current complaint totals and recent review trends on the primary source pages directly. For money decisions, the contract terms matter more than the headline rating.
Safer alternatives before using Oasis Financial
Before using Oasis Financial or any lawsuit funding company, compare lower-risk options first.
Pre-settlement funding is not a traditional loan, but it can still reduce a future settlement because fees are deducted from the payout, so cheaper sources of cash matter.
Start with options that protect medical care, housing, and basic bills. The safest path is usually to cut or defer expenses before selling part of a possible settlement.
Some alternatives have hard consumer protections or government rules. Others depend on credit, income, or the cooperation of a hospital, landlord, or utility provider.
Check the original terms before acting, because a missed payment can still cause harm.
| Alternative | Key fact | Why it may be safer |
| Hospital charity care or bill reduction | Nonprofit hospitals must have a financial assistance policy under Internal Revenue Code Section 501(r), according to the IRS. | Can reduce the bill itself, which avoids borrowing against a settlement. |
| No-interest medical payment plan | The Consumer Financial Protection Bureau said many providers offer payment plans directly, though terms vary by provider. | May cost less than legal funding if no financing charge is added. |
| Credit union payday alternative loan | Federal credit unions may offer Payday Alternative Loans up to $2,000 with application fees capped at $20, according to the National Credit Union Administration. | The fee cap is clearer than many lawsuit-funding contracts. |
| 0% APR credit card intro offer | The CFPB says promotional APR offers can be 0% for a limited period, but deferred interest and regular APR can apply after the promo ends. | Can be cheaper if the balance is repaid during the promo period. |
| 401(k) loan | The IRS says many plans allow loans up to 50% of the vested account balance or $50,000, whichever is less. | Often costs less than settlement funding, but retirement risk is real. |
| State or local emergency aid | Benefits.gov lists programs for rent, food, utilities, and medical support, with eligibility based on state and household circumstances. | Assistance may not need repayment. |
Practical steps before signing
- Ask medical providers for an itemized bill and a hardship review. The CFPB and IRS-backed hospital charity rules make this a meaningful first step.
- Ask a bank or credit union for the total dollar cost, not only the monthly payment. Compare that with the funding contract’s payoff examples.
- Review whether an attorney can help delay collection or negotiate liens. That can preserve more of a settlement than taking cash early.
- Check for public aid through Benefits.gov or a state 211 program before using private funding.
Caution: do not rely on this section alone to choose financing. Contract terms, state rules, tax effects, and medical collection risks vary, so verify details with the provider, your attorney, and the primary source before signing.
Frequently Asked Questions
Is Oasis Financial a legitimate company?
Oasis Financial is a real company operating in the pre-settlement funding market, not a fake website or anonymous lead form.
Readers should still verify current licensing, business records, and court-required contract disclosures in their state before signing, because legitimacy does not mean every offer is low-cost or right for every case.
What does Oasis Financial do?
Oasis Financial provides non-recourse pre-settlement funding, which means repayment typically depends on a case recovering money rather than on the consumer making monthly loan payments.
This product is commonly described as a cash advance against a pending legal claim, but consumers should read the contract carefully because fees, payoff terms, and case outcomes can materially affect how much money remains after settlement.
Is Oasis Financial a loan?
Pre-settlement funding is often marketed as non-recourse funding rather than a traditional personal loan, because approval is generally tied to the legal claim instead of employment income or a FICO credit score from Fair Isaac.
That distinction matters, but readers should not rely on labels alone; the contract cost and repayment formula matter more than the product name, so the primary agreement should be reviewed before accepting funds.
How can someone check whether Oasis Financial is trustworthy?
A practical check starts with primary sources: state business registries, court filings if approval is required, and the signed funding contract.
Consumers can also compare complaint patterns and company responses through the Better Business Bureau, but BBB information is not a government finding and should be used only as one checkpoint, not as proof that a funding company is safe or unsafe.
What are the biggest risks of using Oasis Financial?
The main risk is cost: pre-settlement funding can reduce the consumer’s net settlement because fees may accumulate until the case resolves.
No one should sign based only on a verbal explanation; the safer step is to have the attorney and, if needed, a financial professional review the written payoff terms, cancellation rights, and any state-specific disclosures before funds are accepted.
Related Reading
- JG Wentworth Pre Settlement Funding
- Same Day Pre Settlement Loans – What You Need to Know
- Best Pre Settlement Loans
- National Lawsuit Funding Reviews
- Lawsuit Loans With Low Interest Rates
- Oasis Financial Locations
- Sunrise Lawsuit Funding Reviews
- All Blog Guides
- Consumer Financial Protection Bureau Consumer Complaint Database (n.d.)
- Cornell Law School Legal Information Institute: Champerty (n.d.)
- Federal Trade Commission Consumer Advice (n.d.)
- U.S. Senate Committee on Banking, Housing, and Urban Affairs Hearing on Litigation Financing and the Need for Transparency (2018)
- NAIC Center for Insurance Policy and Research: Litigation Funding (n.d.)