
At a glance: Structured Settlement Debt Collector: a debt collector generally cannot take over a structured settlement without a court order, and transfers of payment rights require judge approval under state structured-settlement protection laws.
However, creditors may have remedies depending on the debt, judgment, and state law. Do not rely on this alone; consult a licensed attorney.
Structured Settlement Debt Collector is a term for a collection agency or creditor pursuing unpaid debt from someone who receives structured settlement payments.
Those payments may be protected or restricted depending on the settlement terms, court order, state law and whether the money has already reached a bank account.
Collectors must follow federal debt-collection rules, including the Fair Debt Collection Practices Act, enforced by the Consumer Financial Protection Bureau and Federal Trade Commission.
A collector generally cannot automatically take future structured settlement payments without legal authority.
Do not rely on general information alone; review the settlement documents and speak with a qualified attorney before responding to collection threats.
What structured settlement debt collectors can do
Structured settlement payments are usually owed by an annuity issuer or assignment company, not by the injured person.
A debt collector generally cannot “take” those future payments without legal process, but it may try to collect a valid debt through permitted communication, litigation, or a court-ordered remedy.
Caution: Debt collection, exemption, and garnishment rules vary by state. A person facing collection should not rely on general information alone; they should check court papers, the annuity contract, and state law, and consider legal help.
- Contact the consumer about a debt. Under the federal Fair Debt Collection Practices Act, a third-party collector may call, send letters, or use electronic communications, but it cannot harass, lie, or use unfair practices.
- Send a validation notice. The Consumer Financial Protection Bureau says collectors generally must provide key debt information, including the creditor’s name and the amount claimed, either in the first communication or within five days after it.
- Report a debt to credit bureaus. A collector may report collection information if it complies with the Fair Credit Reporting Act and CFPB rules. Inaccurate reporting can be disputed with the credit bureau and the furnisher.
- File a lawsuit. A collector may sue to prove the debt and seek a judgment. The Federal Trade Commission warns consumers not to ignore a summons, because failing to respond can lead to a default judgment.
- Use post-judgment remedies. After a judgment, a creditor may seek garnishment, liens, or bank levies if state law allows. Whether structured settlement payments are exempt depends on the state, the settlement documents, and the payment type.
| Rule or limit | Specific fact | Source |
| Validation timing | Debt collectors generally must send written validation information within 5 days after the initial communication if it was not already provided. | 15 U.S.C. § 1692g; CFPB Regulation F materials |
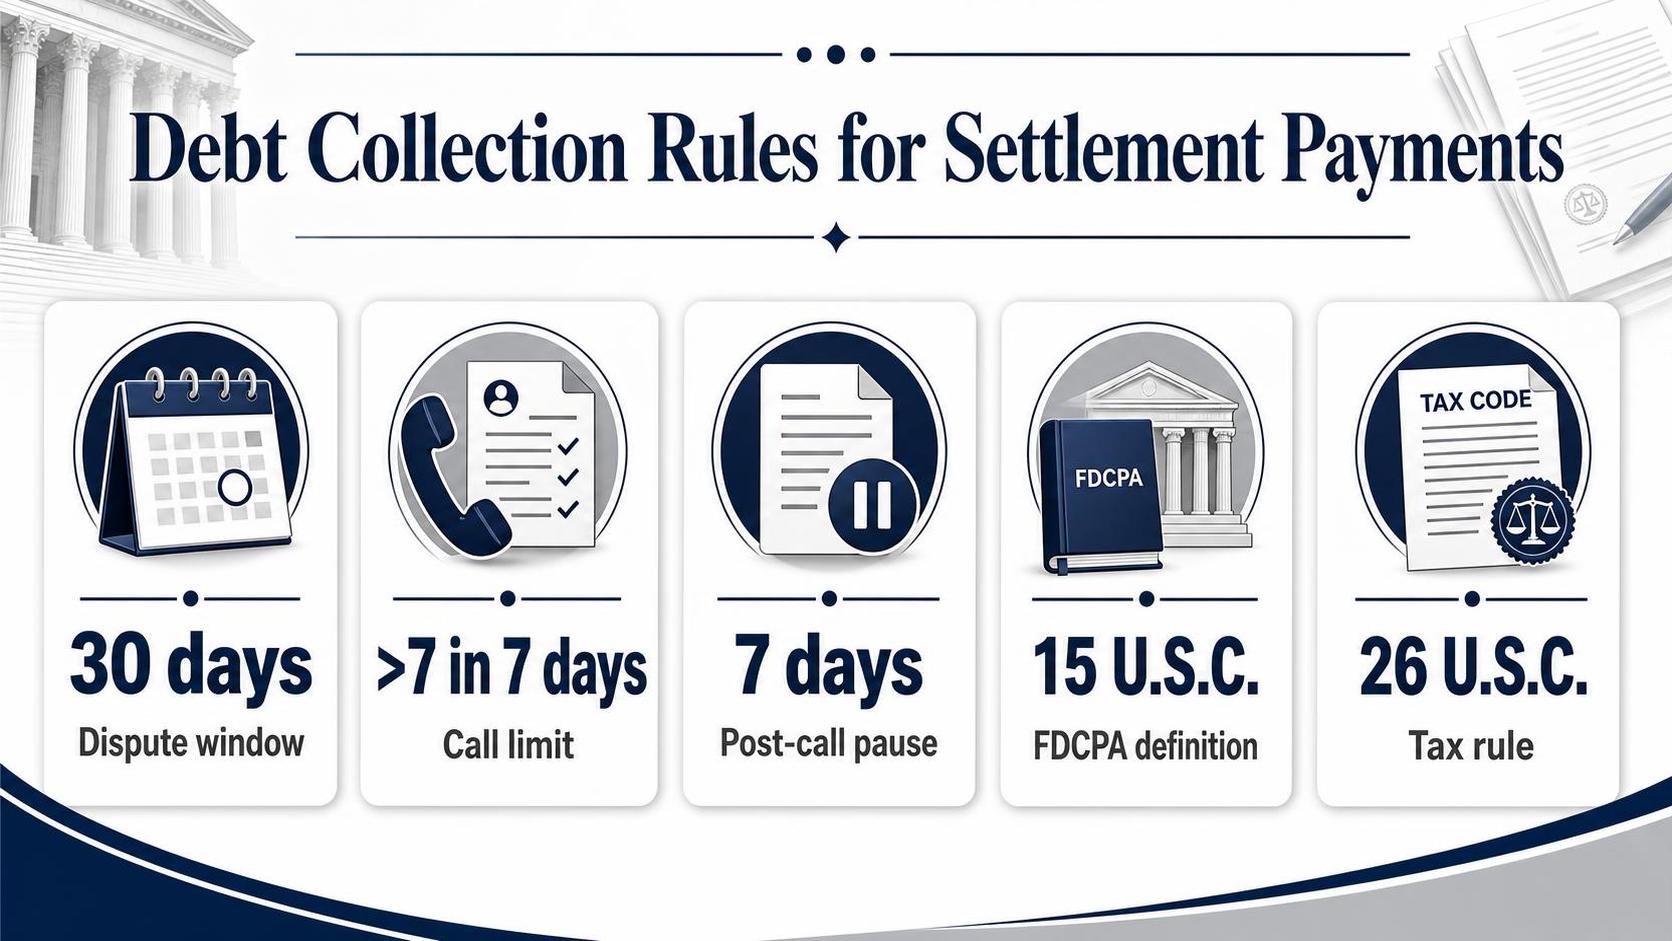
| Call-frequency presumption | CFPB Regulation F creates a presumption of a violation if a collector places more than 7 calls about a debt within 7 consecutive days, or within 7 days after a phone conversation about that debt. | CFPB Regulation F, 12 C.F.R. § 1006.14 |
| Wage garnishment federal cap | For ordinary consumer debts, federal law generally caps garnishment at the lesser of 25% of disposable earnings or the amount above 30 times the federal minimum wage. | Consumer Credit Protection Act, 15 U.S.C. § 1673 |
| Structured settlement transfer approval | A sale or transfer of structured settlement payment rights typically requires advance court approval to avoid federal excise-tax consequences. | Internal Revenue Code § 5891 |
A collector also may ask whether the consumer will voluntarily use settlement payments to pay a debt. That is different from having a legal right to intercept the annuity.
Many structured settlement contracts restrict assignment, and transfer statutes usually require court findings that a transfer is in the payee’s best interest.
Collectors cannot threaten arrest for an ordinary civil debt, falsely claim a payment is already garnished, or bypass a consumer’s attorney after knowing the person is represented.
If a collector claims structured settlement payments are attachable, the consumer should ask for the judgment, garnishment order, and the state-law basis.
Why a collector may contact you
A structured settlement debt collector may contact you because someone claims a debt is connected to your settlement payments, a transfer of payment rights, or an unrelated account.
Do not assume the collector is correct just because the person knows details about your annuity or settlement.
Structured settlement payments often come from an annuity issuer, but collection activity usually involves a separate claimed debt.
The Consumer Financial Protection Bureau says the federal Fair Debt Collection Practices Act covers third-party collectors collecting consumer debts, not original creditors collecting their own debts.
| Reason for contact | What it may mean | Source or rule to know |
| Validation of a claimed debt | The collector says you owe money and must identify the debt, creditor, and amount. | CFPB Regulation F requires validation information, generally in the first communication or within 5 days after it. |
| Disputed sale of payment rights | A factoring company or assignee may claim a transfer was approved, unpaid, reversed, or breached. | Internal Revenue Code Section 5891 imposes a 40% federal excise tax on certain structured settlement transfers without qualified court approval. |
| Overpayment or servicing error | An insurer, administrator, or assignee may allege payments were sent after a transfer, death, court order, or account change. | Check the annuity issuer, court order, and transfer documents directly before paying. |
| Unrelated consumer debt | The collector may be pursuing credit card, medical, loan, or judgment debt and may know you receive settlement payments. | FDCPA rules still apply if the collector is a covered third-party debt collector. |
A collector may also contact you after a structured settlement factoring transaction. State structured settlement protection acts generally require court approval before future payments can be transferred, but the details vary by state.
The National Association of Insurance Commissioners explains that structured settlements are commonly used to provide scheduled payments for personal injury claims.
Those payments can be valuable, so collectors, creditors, and buyers may focus on them.
- Ask for written validation. Under CFPB debt collection rules, validation information should include the debt amount, current creditor, and information about disputing the debt.
- Compare documents. Review the settlement agreement, annuity contract, court transfer order, and any assignment paperwork.
- Watch deadlines. The CFPB states consumers generally have 30 days after receiving validation information to dispute a debt and trigger verification duties.
- Do not share banking access. A legitimate collector should not need your online banking password or annuity login.
Caution: A collector’s claim can affect settlement income, credit, lawsuits, or bank accounts. Before paying, signing, or redirecting payments, verify the debt with the annuity issuer, the court file, and a licensed attorney in your state.
Your federal debt collection rights
Federal law gives consumers specific protections when a debt collector contacts them about a structured settlement-related debt, court judgment, loan, or other consumer obligation.
The main statute is the Fair Debt Collection Practices Act, enforced by the Consumer Financial Protection Bureau and the Federal Trade Commission.
These rights do not erase a valid debt, and they do not replace legal advice. A person facing a lawsuit, garnishment, or assignment dispute should check court papers immediately and speak with a licensed attorney in their state.
| FDCPA rule | Specific federal requirement | Source |
| Validation notice | A collector generally must send written debt-validation information within 5 days after the first communication, unless the information was already provided. | 15 U.S.C. § 1692g(a); CFPB Regulation F |
| Dispute window | The consumer has 30 days after receiving the validation notice to dispute the debt in writing and request verification. | 15 U.S.C. § 1692g(b) |
| Call-frequency presumption | Under CFPB Regulation F, more than 7 calls within 7 consecutive days about one debt, or a call within 7 days after a conversation, is presumed unlawful harassment. | CFPB Regulation F, 12 C.F.R. § 1006.14 |
| Private lawsuit deadline | A consumer generally has 1 year from the FDCPA violation to file a federal civil action. | 15 U.S.C. § 1692k(d) |
A debt collector may not use threats, obscene language, repeated harassing calls, or false statements about the amount or legal status of a debt.
The FDCPA also bars a collector from falsely claiming to be an attorney, government official, or credit bureau.
Collectors usually may not contact a consumer at unusual times or places. The FDCPA treats calls before 8 a.m. or after 9 p.m. local time as inconvenient unless the consumer agrees otherwise, according to 15 U.S.C. § 1692c(a)(1).
- Ask for validation: Request the creditor’s name, the amount claimed, and documents showing the collector’s authority to collect.
- Dispute in writing: If the debt is wrong, disputed, paid, discharged, or not recognized, send a written dispute within the 30-day validation period.
- Limit contact: A written cease-communication request generally requires the collector to stop most contact, except for limited notices allowed by law.
- Protect settlement payments: Do not assign, sell, or redirect structured settlement payments based only on a collector’s demand. Court approval and state structured settlement protection laws may apply.
The FDCPA mainly covers third-party debt collectors, not every original creditor. State laws may provide broader protections, shorter lawsuit deadlines, exemption rules for annuity payments, or licensing requirements.
Check the state attorney general, court rules, and primary statutes before relying on any collection demand.
Structured settlement payment assignment issues
Structured settlement payments are not ordinary receivables that can be casually assigned to a debt collector.
Most transfers require court approval, notice to interested parties, and compliance with federal tax rules and state structured settlement protection acts.
A plain caution: anyone facing collection pressure should not sign an assignment, power of attorney, or “payment direction” without legal advice. A defective transfer can create tax, court, and payment-routing problems.
Why assignment is legally difficult
Congress added Internal Revenue Code Section 5891 in 2002 to discourage unapproved factoring transactions.
The statute imposes a 40% excise tax on the factoring discount unless the transfer is approved in a “qualified order” by a state court or responsible administrative authority.
That federal rule does not make every transfer valid. It works alongside state law, the settlement agreement, the annuity contract, and any anti-assignment language.
An annuity issuer may refuse to redirect payments unless it receives a court order meeting statutory requirements.
| Issue | Specific rule or fact | Source |
| Federal tax penalty | 40% excise tax on the factoring discount for non-qualified structured settlement factoring transactions. | Internal Revenue Code Section 5891(a) |
| Court approval | A transfer must be approved in advance by a qualified order to avoid the federal excise tax. | Internal Revenue Code Section 5891(b) |
| Original tax exclusion | Damages received on account of personal physical injuries or physical sickness are generally excluded from gross income. | Internal Revenue Code Section 104(a)(2) |
| Fair Debt Collection Practices Act damages | A debt collector that violates the FDCPA may face actual damages, plus up to $1,000 in additional statutory damages for an individual action. | 15 U.S.C. Section 1692k(a)(2)(A) |
Collection problems that often arise
- Anti-assignment clauses: Settlement documents commonly restrict or prohibit assignment. A collector’s private agreement with the payee may not bind the annuity issuer.
- Wrong legal theory: A debt collector may be able to collect a valid debt, but that is different from owning future structured settlement payments.
- Notice defects: State protection acts typically require notice to the payee, insurer, annuity issuer, and other interested parties before a transfer hearing.
- Best-interest review: Courts commonly examine whether the transfer is in the payee’s best interest, including dependents’ welfare. State standards vary, so check the current state statute and court rules.
- Payment-splitting limits: Some annuity issuers resist partial assignments or frequent payment changes because they create administrative and tax-reporting risk.
Debt collectors also must avoid misleading threats.
The Consumer Financial Protection Bureau explains that the FDCPA generally bars false, deceptive, or misleading representations in debt collection, including misrepresenting the legal status of a debt.
The safest practical takeaway is narrow: a collector’s demand letter is not the same thing as a court-approved structured settlement transfer.
Before redirecting payments, verify the court order, state-law approval, annuity issuer acceptance, and any tax consequences with qualified counsel.
State protections for settlement recipients
State law can protect structured settlement recipients in two different ways: by requiring court approval before payments are sold, and by limiting what creditors or debt collectors can reach.
These protections vary sharply by state, so a recipient should verify the current statute or ask a licensed attorney before relying on an exemption.
At the federal level.
Internal Revenue Code §5891 imposes a 40% excise tax on a factoring company unless the transfer is approved in a “qualified order.” That order must come from a court or responsible administrative authority under an applicable state.
Structured settlement protection act.
| Protection | Example source | What it means for recipients |
| Court approval before a payment sale | Internal Revenue Code §5891; state structured settlement protection acts | A buyer generally cannot complete a transfer without a judge finding that the sale meets statutory standards, often including the recipient’s best interest. |
| Advance disclosure of discount terms | New York General Obligations Law §5-1703 | New York requires a written disclosure statement at least 10 days before the recipient signs a transfer agreement. |
| Notice before the hearing | California Insurance Code §10139.5 | California requires notice of the proposed transfer hearing to be filed and served at least 20 days before the hearing. |
| Exemption from creditor process | Florida Statutes §222.14 | Florida exempts proceeds of annuity contracts from attachment, garnishment, or legal process by creditors, subject to statutory limits and exceptions. |
| Support-based injury recovery exemption | California Code of Civil Procedure §704.150 | California exempts personal injury recoveries to the extent necessary for the support of the judgment debtor and dependents. |
These rules do not make every settlement payment untouchable. A debt collector with a judgment may try to garnish bank funds after payments are deposited, and the recipient may have to claim an exemption under state procedure.
Some obligations receive stronger collection rights. Child support, certain tax debts, criminal restitution, and federally backed debts may be treated differently from ordinary credit-card or medical-debt judgments.
State exemptions may not defeat these priority claims.
- Keep records: Retain the settlement agreement, annuity contract, court order, payment schedule, and bank statements showing the source of deposits.
- Do not ignore court papers: Exemption rights can be lost or delayed if a recipient misses objection deadlines.
- Check the primary source: Exemption amounts, notice periods, and court forms change, and county practice can differ within the same state.
Caution: A debt collector’s threat is not the same as a lawful garnishment order, but ignoring a lawsuit can lead to a default judgment.
Settlement recipients should get state-specific legal advice before moving money, signing a payment sale, or responding to a levy.
What Coin Abul independently reviewed
Coin Abul independently reviewed the legal and consumer-protection rules that matter when a debt collector contacts someone who receives structured settlement payments.
The review focused on federal debt-collection law, CFPB rules, tax consequences, and court-approval requirements for transfers.
This article is informational only. A collector, settlement buyer, or court notice can affect legal rights and future income, so readers should verify deadlines with the court, the CFPB, a state regulator, or a licensed attorney.
| Issue reviewed | Primary source | Key fact |
| Debt-collector notice rights | Fair Debt Collection Practices Act, 15 U.S.C. § 1692g | A debt collector generally must send a written validation notice within 5 days after the initial communication, unless the required information was already provided. |
| Disputing a debt | FDCPA, 15 U.S.C. § 1692g | The consumer has 30 days after receiving the validation notice to dispute the debt in writing and request verification. |
| Call timing limits | FDCPA, 15 U.S.C. § 1692c | Collectors generally may not call before 8 a.m. or after 9 p.m. in the consumer’s local time, unless the consumer agrees. |
| Call-frequency standard | CFPB Regulation F, 12 C.F.R. § 1006.14 | The CFPB’s rule creates a presumption of a violation if a collector places more than 7 calls about a debt within 7 consecutive days, or calls within 7 days after a phone conversation about that debt. |
| Structured-settlement transfer tax risk | Internal Revenue Code § 5891 | A transfer that lacks a qualified court order can trigger a 40% federal excise tax on the factoring discount. |
Coin Abul also reviewed how a structured settlement differs from ordinary wages or bank deposits. A settlement annuity is typically paid by an insurance company under a court-approved or contract-based payment schedule, not by an employer.
That distinction matters because a debt collector usually cannot simply “take” future structured settlement payments by demand letter.
Collection tools depend on a judgment, state exemption law, garnishment rules, and the payee’s transfer documents.
- Federal debt-collection conduct: The review checked the FDCPA and CFPB Regulation F for harassment, false statements, validation notices, time-barred-debt disclosures, and communication limits.
- Structured settlement transfer rules: The review checked the federal tax penalty in IRC § 5891 and the common requirement that a state court find a proposed transfer in the payee’s best interest.
- Consumer complaint sources: The review considered CFPB guidance and the CFPB Consumer Complaint Database as public sources for patterns involving debt collection and settlement-payment companies.
- State-law limits: State exemption, garnishment, and structured-settlement protection laws vary. Coin Abul did not treat any state rule as universal unless supported by the primary statute.
A plain caution: do not sign a transfer agreement, payment assignment, consent judgment, or debt-settlement authorization based only on a collector’s explanation.
Written documents can permanently reduce future settlement income and may be difficult to unwind after court approval.
When to contact a consumer attorney
Contact a consumer attorney quickly if a debt collector is pressuring someone to sell structured settlement payments, threatening a lawsuit, or contacting them in ways that feel abusive.
Structured settlement rights are often court-protected, and a bad decision can permanently reduce future income.
A lawyer is especially important when collection pressure overlaps with a proposed factoring transaction.
Under Internal Revenue Code Section 5891, a structured settlement transfer generally needs a qualified court order; otherwise, the transferee can face a 40% excise tax on the factoring discount.
Red flags that justify legal help
- Threats or harassment: The Fair Debt Collection Practices Act, enforced by the Federal Trade Commission and Consumer Financial Protection Bureau, bars harassment, false threats, and misleading statements by third-party debt collectors.
- Calls at improper times: The FDCPA generally prohibits collector calls before 8 a.m. or after 9 p.m. in the consumer’s local time, unless the consumer agrees.
- No written validation notice: Under the FDCPA, a collector must send written information about the debt within 5 days after the first communication, unless that information was already provided.
- Disputed debt ignored: If the consumer disputes the debt in writing within 30 days after receiving the validation notice, the collector must stop collection until it verifies the debt.
- Repeated call pressure: CFPB Regulation F creates a call-frequency presumption: more than 7 calls within 7 consecutive days, or a call within 7 days after a phone conversation about the debt, may violate the rule.
- Lawsuit papers arrived: Do not ignore a summons. Court deadlines can be short, and a default judgment may lead to garnishment, bank restraints, or liens depending on state law.
A plain caution: do not sell structured settlement payments, admit liability, or agree to a payment plan based only on collector pressure. Ask for documents, keep records, and get advice before signing anything that affects future payments.
Legal remedies may be available
If the collector violated federal law, an attorney can assess damages and defenses.
The FDCPA allows actual damages, statutory damages up to $1,000 in an individual action, and recovery of reasonable attorney’s fees and costs under 15 U.S.C. Section 1692k.
If calls were made with an autodialer, prerecorded voice, or after a stop request, the Telephone Consumer Protection Act may also matter.
The Federal Communications Commission describes TCPA penalties as $500 per violation, with possible trebling to $1,500 for willful or knowing violations.
State law can add protections, but rules vary. Some states regulate debt collectors, some regulate buyers of structured settlement payments, and every structured settlement transfer approval process is state-specific.
Check the state attorney general, court rules, and the original settlement documents.
Frequently Asked Questions
Can a debt collector take money from a structured settlement?
It depends on the type of debt, the settlement documents, and state law.
Structured settlement payments are often protected from assignment or garnishment, but exceptions may apply for obligations such as child support, tax debts, or court judgments.
Readers should not rely on general rules and should check the court order, annuity contract, and state law.
Can a debt collector force the sale of structured settlement payments?
A debt collector generally cannot force a payee to sell future structured settlement payments to a factoring company.
Under the federal Structured Settlement Protection Act framework reflected in state statutes, transfers usually require court approval, including a finding that the transfer is in the payee’s best interest.
What should a structured settlement recipient do if contacted by a debt collector?
The Consumer Financial Protection Bureau says consumers have the right to request debt validation information from a collector, including the amount owed and the creditor’s name.
A recipient should avoid sharing annuity account details or agreeing to payment terms until the debt is verified and, for legal threats, should consider speaking with a consumer attorney.
Are structured settlement payments protected from creditors in bankruptcy?
Bankruptcy protection depends on federal bankruptcy exemptions, state exemption laws, and whether the settlement arose from personal injury, workers’ compensation, or another claim.
Because exemptions are highly fact-specific and missing a deadline can cause financial harm, a structured settlement recipient should verify the rules with a qualified bankruptcy attorney before filing or responding to a creditor.
Can a debt collector call the annuity company that makes structured settlement payments?
A collector may try to locate assets, but the Fair Debt Collection Practices Act limits abusive, deceptive, or unfair collection conduct and restricts certain third-party communications.
If a collector pressures an annuity issuer, employer, family member, or court without proper authority, the recipient can document the contact and review complaint options with the CFPB, state attorney general, or a private attorney.
Related Reading
- Structured Settlement Annuity Companies
- Structured Settlement Loans – What You Need to Know
- Structured Settlement Broker
- AIG Structured Settlements – The Truth You Didn't Know
- Structured Settlement Buyer – What You Need to Know
- Structured Settlement Funding
- Cash For Structured Settlement Payments
- All Blog Guides
Pretty nce post. I just stumbled upon your blogg and wanted
tto mention that I hve truly enjoyed surfing arojnd your blg posts.
In any casee I willl be subscribinbg on yolur feewd annd I’m hopin yyou
write once more very soon!