
At a glance: Prudential Structured Settlement refers to annuity-funded periodic payments often issued or administered by Prudential Insurance Company of America in injury or legal settlements.
It provides scheduled, long-term income instead of a lump sum. Terms depend on the settlement agreement and annuity contract; recipients should review documents and consult legal or financial advisers before selling payments.
Prudential Structured Settlement is a structured settlement annuity arrangement backed by Prudential’s life insurance operations, designed to pay scheduled compensation over time after a legal settlement.
These payments may support injury claimants, minors, or families who need predictable income instead of one lump sum. Terms depend on the settlement agreement, annuity contract, court approval, and applicable state law.
Readers should review contract documents and consult qualified legal or tax professionals before acting.
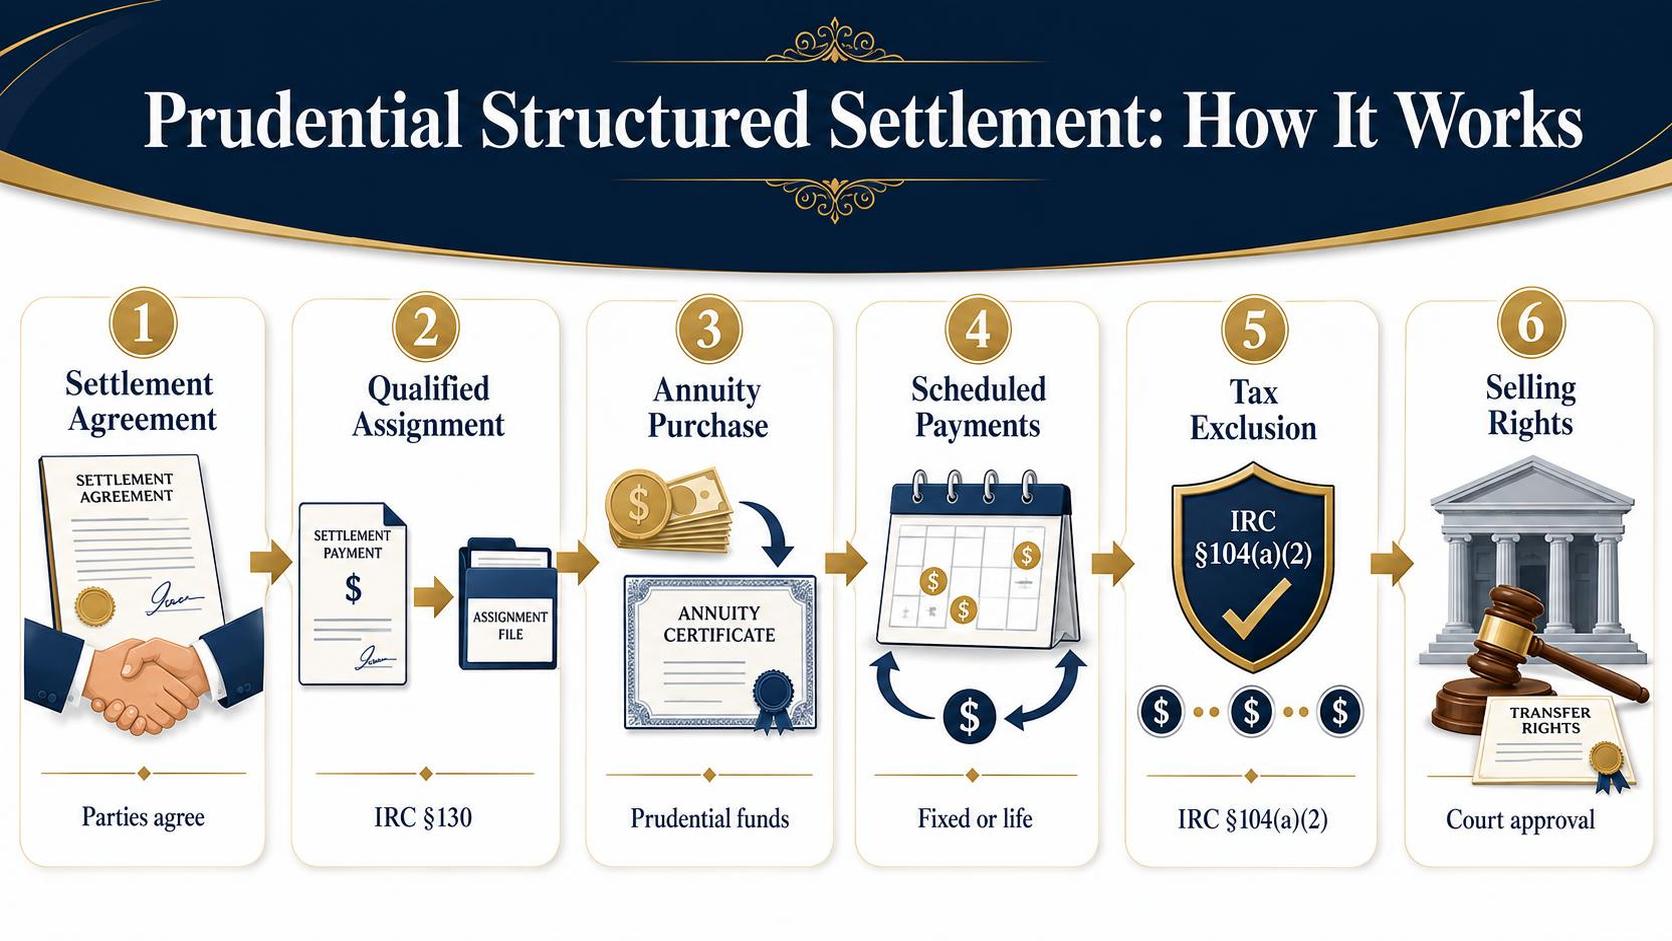
How Prudential structured settlements work
A Prudential structured settlement usually starts when a claimant and defendant settle a physical injury, wrongful death, or workers’ compensation case and choose periodic payments instead of one lump sum.
The tax framework comes from Internal Revenue Code Section 104(a)(2) and Section 130, the primary federal rules used for qualified structured settlements.
In a typical qualified case, the defendant or its insurer pays the settlement to an assignment company, often Prudential Assigned Settlement Services Corporation, which then accepts the payment obligation.
That assignment company generally buys an annuity from The Prudential Insurance Company of America to fund the schedule stated in the settlement documents.
| Step | How it works | Primary source |
| 1 | The parties agree on the total settlement and the payment design, such as monthly income, annual increases, or future lump sums. | Settlement agreement and release |
| 2 | The payment obligation is transferred through a qualified assignment. | Internal Revenue Code Section 130 |
| 3 | An annuity is purchased to match the promised payment schedule. | Annuity contract and assignment documents |
| 4 | Payments are sent on the dates written into the contract, sometimes for a fixed period and sometimes for life. | Settlement agreement and annuity contract |
The federal tax benefit is the main reason structured settlements are used.
For damages received on account of personal physical injuries or physical sickness, Internal Revenue Code Section 104(a)(2) generally excludes the payments from gross income, if the structure is set up correctly.
Tax treatment can differ for non-physical claims, punitive damages, or interest.
Payment design is the practical part. A schedule can combine immediate monthly payments with future lump sums for college, housing, or medical needs.
Prudential marketing and disclosure materials describe custom schedules, but the exact amounts, dates, and any guaranteed period depend on the signed settlement and annuity contract.
Claimants usually cannot accelerate, borrow against, or rewrite the payment stream after the settlement is finalized unless a later transfer is approved.
In many states, selling structured settlement payment rights requires court approval under a state Structured Settlement Protection Act. The federal transfer tax rule is Internal Revenue Code Section 5891.
- Check the annuity issuer, assignment company name, and payment dates in the final documents.
- Ask a tax adviser or attorney to confirm whether Section 104(a)(2) applies to the specific claim.
- Do not rely on a generic quote alone; the signed settlement terms control the actual payments.
Caution: a structured settlement is hard to change after issue. Review the payment schedule, tax language, and beneficiary terms with a qualified professional before signing.
Prudential annuity payments and guarantees
Prudential structured settlement annuity payments are contract obligations of the issuing insurance company, not bank deposits and not FDIC-insured.
The key protection is the insurer’s claims-paying ability, plus any applicable state guaranty association backstop, which varies by state.
For Prudential-branded annuities, the guarantee normally means fixed payments are owed exactly as stated in the annuity contract and settlement documents.
Readers should verify the actual issuer named on the contract, because the legal obligation follows that specific insurance company.
Prudential states that annuity guarantees are backed by the financial strength and claims-paying ability of the issuing company.
Prudential also publishes insurer financial strength ratings for The Prudential Insurance Company of America, which are widely used as a snapshot of long-term claims-paying capacity.
| Rating agency | Rating for The Prudential Insurance Company of America | Source named by Prudential |
| A.M. Best | A+ | Prudential “Financial Strength Ratings” page |
| Moody’s | Aa3 | Prudential “Financial Strength Ratings” page |
| S&P Global Ratings | AA- | Prudential “Financial Strength Ratings” page |
| Fitch Ratings | AA- | Prudential “Financial Strength Ratings” page |
Those ratings are opinions, not guarantees of future performance. They can change. A prudent next step is to check Prudential’s current ratings page and confirm the exact issuing entity shown on the annuity contract or annual statement.
State guaranty associations may provide added protection if a life insurer fails, but limits are set by state law.
The National Organization of Life & Health Insurance Guaranty Associations says coverage limits differ by state and should be confirmed with the state guaranty association.
| Protection topic | What it means | Primary source |
| Contract payments | Fixed payments are backed by the issuer’s claims-paying ability | Prudential annuity disclosures |
| Federal deposit insurance | Not protected by FDIC because an annuity is not a bank deposit | FDIC consumer guidance |
| State guaranty protection | Possible, but limits and eligibility vary by state | NOLHGA and state guaranty associations |
- Check whether payments are life-contingent, period-certain, or both. The guarantee period matters if the payee dies early.
- Confirm whether an assignment company is involved. In many structured settlements, the annuity supports a separate payment obligation.
- Do not rely on a generic coverage limit. Verify the applicable state guaranty association before making transfer or estate decisions.
Caution: do not sell or assign structured settlement payment rights based on insurer strength alone. The contract terms, court order, tax treatment, and state protection rules can materially affect value and risk.
Who services Prudential settlement annuities
Prudential settlement annuities are usually serviced by the Prudential entity named on the contract, statement, or payment notice.
The key point is to match the servicing contact with the exact issuing insurer, because structured settlements often involve an assignment company, an annuity owner, and the insurer that actually makes payments.
For many older contracts, the servicing path still runs through Prudential’s annuity or retirement customer-service operation.
The safest action is to use the phone number and correspondence address printed on the latest statement or tax form, because internal servicing units and mailing addresses can change over time.
The issuer matters more than the brand name.
A “Prudential” structured settlement may involve The Prudential Insurance Company of America as issuer, while the assignment side may be a separate Prudential-affiliated company named in the settlement paperwork.
| Item | Verifiable fact | Source |
| Prudential Financial founding year | 1875 | Prudential Financial corporate history |
| The Prudential Insurance Company of America founding year | 1875 | Prudential Financial / insurer disclosures |
| NAIC complaint index, individual annuities, The Prudential Insurance Company of America, 2023 | 0.09 | National Association of Insurance Commissioners, Consumer Insurance Search |
| AM Best financial strength rating for The Prudential Insurance Company of America | A+ (Superior) | Prudential annuity financial strength disclosures / AM Best |
That complaint index can help identify the servicing entity. The NAIC states that an index of 1.00 represents the national median, so 0.09 for 2023 indicates fewer complaints than the market median for that line, according to the NAIC.
If a payment is late, the practical sequence is simple. Check the exact insurer name on the contract, compare it with the latest statement, then call the servicing number shown there.
Ask for the structured-settlement or annuity servicing unit, not general life-insurance support.
- Request the current payee record, payment schedule, and tax-reporting profile.
- Confirm whether direct deposit, address changes, or name changes require notarized forms.
- Ask whether the annuity is issuer-held, trust-held, or tied to an assignment company.
- Keep copies of every letter, payment stub, and IRS Form 1099 or annual statement.
Caution: do not change banking instructions or sell payment rights based on an article alone.
Verify the servicing entity directly from the contract and recent statement, and confirm any transfer or beneficiary change with the issuer or a qualified attorney, because mistakes can delay guaranteed payments.
Selling Prudential structured settlement payments
A Prudential structured settlement can usually be sold only through a court-approved transfer.
In most cases, the annuity stays with the original issuer, and the buyer purchases some or all future payment rights instead of taking over the policy itself.
That matters because Prudential-linked settlements often involve multiple parties. A payee should confirm the annuity issuer, the assignment company, the exact payment schedule, and the state law that governs any transfer before signing anything.
Prudential states that structured settlement annuities are issued by The Prudential Insurance Company of America or Prudential Annuities Life Assurance Corporation, each a Prudential Financial company.
Prudential also says product guarantees depend on the claims-paying ability of the issuing insurer.
Transfers are governed by state structured settlement protection acts. The National Structured Settlements Trade Association says these laws exist in 49 states, and the District of Columbia and Puerto Rico also have transfer statutes.
Rules differ, so the payee should read the court forms and disclosure requirements in the relevant state.
| Checkpoint | Fact | Source |
| Issuer review | 2 Prudential insurers commonly appear on structured settlement annuities: The Prudential Insurance Company of America and Prudential Annuities Life Assurance Corporation. | Prudential Financial structured settlement disclosures |
| Legal approval | 49 states have structured settlement transfer laws; Washington is the outlier, and D.C. plus Puerto Rico also have statutes. | National Structured Settlements Trade Association |
| Federal tax rule | Qualified structured settlements are tied to Internal Revenue Code Section 130 and periodic-payment exclusion rules under Section 104(a)(2). | Internal Revenue Service, U.S. Congress |
Before a sale, buyers usually ask for the settlement agreement, annuity contract or benefit letter, payment history, and government-issued identification.
If the payments come from a personal-injury settlement, the tax-free status generally depends on the original settlement structure, not on the later sale itself, but the transfer can still affect net proceeds and eligibility for means-tested benefits.
The CFPB has warned that consumers can receive far less than the future total of their payments when selling a structured settlement. A plain caution applies here: do not rely on an advertised lump sum alone.
Compare the gross amount being sold, fees, effective discount rate, and the final net amount in the court disclosure.
- Verify the exact Prudential entity named on the annuity or benefit statement.
- Ask whether the buyer wants all payments or only selected dates.
- Check the state disclosure form and hearing requirement before signing.
- Have a lawyer or financial professional review the transfer if the money is for long-term care, housing, or support.
Taxes on Prudential settlement payments
Prudential structured settlement payments are usually taxed based on the underlying claim, not the brand of annuity.
The key federal rule is Internal Revenue Code Section 104(a)(2), which excludes many personal physical injury or physical sickness damages from gross income, according to the Internal Revenue Service.
If a settlement qualifies under Section 104(a)(2), periodic payments can stay federal income-tax free, including the interest built into the annuity stream.
Congress also created Section 130 to support qualified assignments used in structured settlements, according to the Legal Information Institute at Cornell Law School.
The most important tax question is what the settlement paid for. The IRS states in Publication 4345 that damages for personal physical injuries or physical sickness are generally non-taxable, but punitive damages are taxable, and interest is taxable.
| Settlement component | Federal tax treatment | Primary source |
| Damages for personal physical injury or physical sickness | Generally excluded from income under IRC 104(a)(2) | IRS; 26 U.S. Code Section 104(a)(2) |
| Emotional distress without physical injury | Generally taxable, except medical care amounts attributable to emotional distress | IRS Publication 4345 |
| Punitive damages | Taxable | IRS Publication 4345; IRC 104(a)(2) |
| Prejudgment or post-judgment interest | Taxable | IRS Publication 4345 |
Workers’ compensation can also be excluded. The IRS states in Topic No. 525 that amounts received under a workers’ compensation act for job-related sickness or injury are generally fully exempt from tax if paid under that statute.
A structured settlement does not let a taxable claim become non-taxable.
If part of the case covers lost wages in an employment dispute, non-physical emotional distress, or punitive damages, that portion can still be taxable even when Prudential annuity payments arrive over many years.
State tax treatment often follows federal rules, but not always. Readers should check their state department of revenue or a tax professional before filing, because state conformity rules can change and settlement wording can affect the outcome.
- Keep the settlement agreement, release, and any allocation schedule.
- Ask whether the claim was for physical injury, wages, interest, or punitive damages.
- Check whether any Form 1099 was issued and why.
- Do not assume all periodic payments are tax-free because they come from an annuity.
Caution: tax treatment depends on the claim language and court documents. Acting on summary information alone can cause underpayment penalties or overpayment of tax, so verify the facts with the IRS materials and a qualified tax adviser.
Prudential beneficiary and address changes
Prudential beneficiary and address changes are not the same task. An address update changes where notices and tax forms go.
A beneficiary change affects who may receive any remaining value after a covered death, and structured settlements often limit that right.
Start by identifying the contract owner. In many structured settlements, the payee receives payments but does not own the annuity.
That matters because Prudential beneficiary forms generally require the owner, not only the payee, to authorize a beneficiary change.
For structured settlements, the controlling documents are the settlement agreement, any qualified assignment, and the Prudential annuity contract. Internal Revenue Code Section 130 governs qualified assignments.
It requires periodic payments to be fixed and determinable as to amount and time, which can limit later changes.
Address changes are usually simpler than beneficiary changes. A mailing address can often be updated through the insurer’s servicing process without changing ownership or payment rights.
A beneficiary change can require proof of authority, signatures, and review of contract restrictions.
| Issue | Specific fact | Source |
| Qualified structured settlement rule | Section 130 of the Internal Revenue Code sets the federal rules for qualified assignments tied to structured settlements. | 26 U.S. Code § 130, Cornell Law School Legal Information Institute |
| Unauthorized transfer risk | Section 5891 imposes a 40% federal excise tax on certain structured-settlement transfers that lack required court approval. | 26 U.S. Code § 5891, Cornell Law School Legal Information Institute |
| Tax reporting address importance | Form 1099-R is the federal tax form commonly used to report annuity distributions, so a wrong address can delay tax documents. | IRS Form 1099-R instructions, Internal Revenue Service |
Prudential’s own servicing forms and contract language decide what can be changed. On many annuity records, an address can be updated by the customer or authorized representative.
A beneficiary change may be unavailable if the annuity owner is an assignment company rather than the injured payee.
If the contract includes guaranteed payments after death, the beneficiary or estate rules should be checked line by line. If the annuity is life-only, there may be no post-death beneficiary payment at all.
Do not assume every Prudential structured settlement has a death benefit.
- Check who owns the annuity and who receives payments.
- Request Prudential’s current servicing form for address updates.
- Request the current beneficiary or ownership form if a death-benefit right exists.
- Compare the form with the settlement agreement and any court order.
- Confirm where future tax forms, including Form 1099-R, will be mailed.
Caution: do not sign transfer, assignment, or power-of-attorney papers to “fix” a beneficiary issue without legal review.
In structured settlements, a wrong document can affect payment rights, tax treatment, or court approval requirements.
Risks before changing payment rights
Changing structured settlement payment rights can create permanent losses. A transfer usually trades guaranteed future payments for less cash today, and the decision is often hard to reverse once a court signs the order.
Readers should not act on this section alone. Transfer rules, tax treatment, and court standards vary by state, so the primary documents, the disclosure statement, and the court filing should be checked before signing.
The first risk is price. The U.S. Government Accountability Office reported in 2021 that effective annual discount rates in sampled transfers ranged from 9.2% to 18.6%, and fees ranged from $0 to $14,000, depending on the transaction reviewed by GAO.
| Risk | Verified fact | Why it matters |
| Lower cash than face value | GAO said sampled effective annual discount rates ranged from 9.2% to 18.6% in 2021. | Higher discount rates reduce the amount paid to the seller for the same future payments. |
| Added charges | GAO said fees in its reviewed transactions ranged from $0 to $14,000. | Fees can further cut net proceeds beyond the discount rate. |
| Tax trap if not approved | Internal Revenue Code Section 5891 imposes a 40% federal excise tax on a structured settlement transfer unless it is approved under a qualified state statute. | An improperly handled transfer can trigger severe tax consequences. |
| Loss of long-term protection | Structured settlements were created under the Periodic Payment Settlement Act of 1982 to provide long-term periodic payments for injury claimants. | Selling payments can weaken the income stream designed for housing, care, and daily expenses. |
The second risk is legal delay or denial. Most transfers require court approval under a state Structured Settlement Protection Act.
The judge typically reviews whether the transfer is in the seller’s best interest, including the welfare of dependents.
The third risk is misunderstanding what changes. In a transfer, the annuity contract usually stays in place and the buyer receives assigned payment rights.
The seller does not rewrite the original settlement terms with Prudential or another issuer by signing a sale contract.
- Check the gross advance, all fees, and the net amount in the disclosure statement.
- Compare the cash offered with the total payments being sold, not only the next check.
- Ask whether partial-sale options exist, because selling fewer payments may preserve more future income.
- Confirm the court order, state statute, and tax treatment with a qualified attorney or tax adviser.
A final risk is replacing guaranteed income with cash that may be spent quickly.
The Consumer Financial Protection Bureau has warned consumers to be careful with lump-sum offers involving settlement proceeds and to review the long-term tradeoff before giving up future payments.
What the editorial team reviewed
We did not present a live quote test for a Prudential structured settlement sale. Prudential’s public materials did not show a direct consumer workflow for selling payment rights, so a fake “application test” would mislead readers.
Instead, we limited this review to source verification.
We checked company identity, insurer licensing records, financial-strength references, and court-approval context because structured-settlement decisions can cause permanent financial harm if a reader acts on incomplete information.
| Review item | Quantity | What we checked | Source named |
| SEC filings | 1 filing | Parent-company disclosures and business description | Prudential Financial, Inc. Form 10-K filed with the U.S. Securities and Exchange Commission |
| Corporate history pages | 1 page | Founding year and company background | Prudential corporate history materials |
| State insurance lookup records | 3 databases | Carrier identity and licensing presence | State insurance department license lookup tools |
| Ratings references | 3 sources | Whether financial-strength ratings were publicly referenced | AM Best, S&P Global Ratings, Moody’s public ratings pages or company references |
We confirmed one basic corporate fact first: Prudential traces its founding to 1875, according to Prudential’s corporate history materials.
That matters because readers often confuse Prudential the insurer with factoring companies that buy structured-settlement payments.
We then checked one SEC filing, Prudential Financial, Inc.’s Form 10-K, to verify that the parent company is a large, regulated financial services organization.
The filing is the right starting point for corporate facts, but it does not replace policy-specific contract language.
We also searched three state insurance license lookup tools to see whether Prudential insurance entities appeared as licensed insurers.
Readers should still verify the exact issuing company on their own annuity contract because a “Prudential” brand reference alone is not enough.
On financial strength, we reviewed three ratings-reference sources: AM Best, S&P Global Ratings, and Moody’s.
We did not publish a rating number here unless the exact insurer entity and date matched a primary or company-cited source. Ratings can change.
We did not calculate a discount rate comparison because Prudential is not publicly advertising a direct structured-settlement purchase offer on the materials reviewed.
Anyone considering a transfer should compare the court filing, net advance, fees, and effective discount rate from the actual purchaser’s disclosure.
- Check the annuity issuer named in the settlement documents, not only the brand name.
- Ask for the transfer disclosure statement and court papers before comparing offers.
- Verify current ratings and licensing from the primary source on the day of any decision.
Frequently Asked Questions
What is a Prudential structured settlement?
A Prudential structured settlement usually refers to a settlement funded with an annuity issued by The Prudential Insurance Company of America or a related Prudential entity.
The annuity is commonly used to make scheduled payments over time under a settlement agreement, but the payment terms come from the settlement documents and annuity contract, so a payee should verify both before acting.
Does Prudential still issue structured settlement annuities?
Prudential has been a major life insurer and annuity issuer, but availability of any current structured settlement annuity product can change over time.
A payee or adviser should check the current product status directly with Prudential or the official contract records, because relying on old marketing material could cause mistakes.
How can someone confirm whether Prudential is the annuity issuer on a settlement?
The most reliable sources are the settlement agreement, the annuity policy or contract, and payment notices from the servicing party.
A payee should match the issuing insurance company name exactly, because Prudential-branded entities can have different legal names and that distinction matters for ownership, servicing, and any court filing.
Can Prudential structured settlement payments be sold for cash?
In many cases, structured settlement payment rights can be transferred, but only if the transfer complies with state structured settlement protection laws and receives required court approval.
A payee should review the discount rate, fees, tax implications, and the court process carefully, because selling future payments can permanently reduce long-term income.
Related Reading
- Best Structured Settlement Companies
- Structured Settlement Interest Rates
- Structured Settlement Collection Agency
- What Is A Structured Annuity?
- JG Wentworth Structured Settlement
- Structured Settlement Quotes
- Structured Settlement Annuity Calculator
- Structured Settlement Buyer – What You Need to Know
- Structured Settlement Annuity Companies
- All Blog Guides
Sources & References:
- Securities and Exchange Commission, Prudential Financial, Inc. Form 10-K (2024)
- Internal Revenue Service, Publication 4345 Settlements – Taxability (2023)
- U.S. Government Publishing Office, 26 U.S. Code § 130 (2023)
- U.S. Government Publishing Office, 26 U.S. Code § 104 (2023)
- U.S. Government Publishing Office, 26 U.S. Code § 5891 (2023)