
Quick answer: Structured Settlement Payout is a scheduled payment from a legal settlement, usually issued monthly, annually, or in lump sums through an annuity. Payout amounts and timing are set in the settlement agreement.
Caution: selling future payments can be costly and may require court approval.
Structured Settlement Payout is a court-approved or contract-based stream of future payments, usually funded by an annuity after a personal injury, wrongful-death, or workers’ compensation claim.
The schedule can be monthly, annual, lump-sum at set dates, or a combination, depending on the settlement agreement. Personal physical injury payments may receive favorable federal tax treatment under Internal Revenue Code Section 104(a)(2).
Selling future payments for cash can reduce the total value received and usually requires court approval under state structured settlement protection laws.
Readers should review the original settlement documents and get independent legal or financial advice before acting.
How structured settlement payouts work
A structured settlement payout is a court-approved or settlement-agreement payment stream, usually funded with an annuity, instead of one immediate lump sum.
The schedule can be monthly, annual, delayed, or built around future needs such as surgery, college, or retirement.
In a typical injury case, the defendant or liability insurer agrees to make future payments.
The payment obligation is often assigned to a qualified assignment company, which purchases an annuity from a life insurance company to fund the promised dates and amounts.
- Payment schedule: The settlement documents state the exact payment dates, amounts, and any guaranteed period.
- Funding asset: A life insurer commonly issues an annuity that matches the payment obligation.
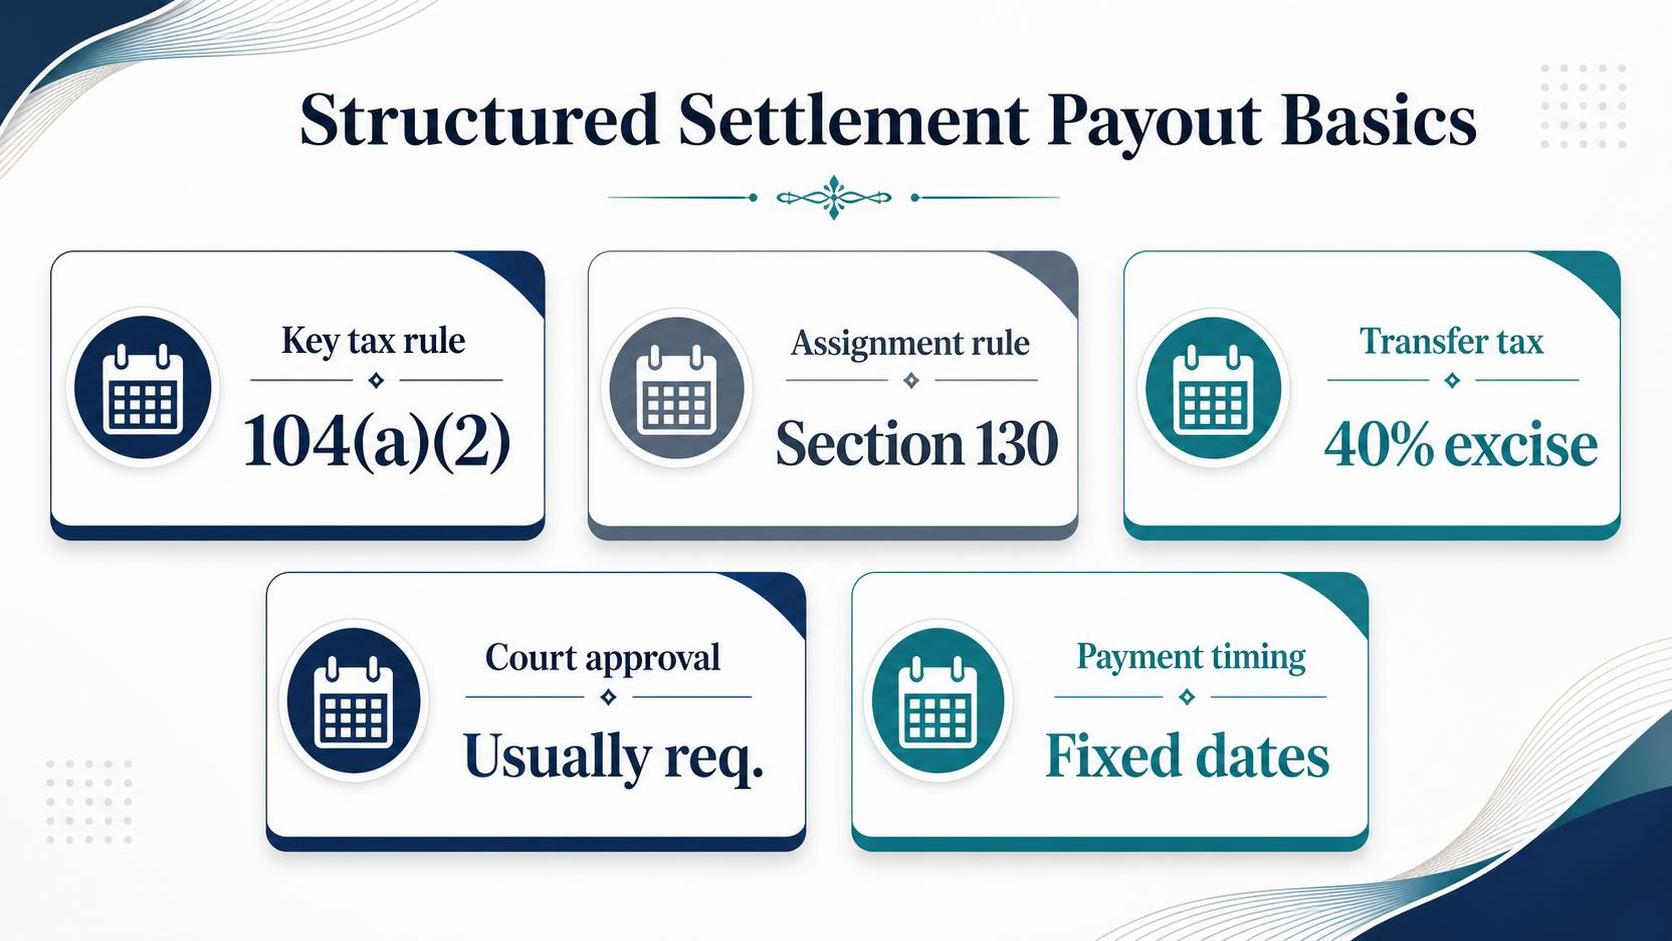
- Tax treatment: The IRS says damages for personal physical injuries or physical sickness are generally excluded from income under Internal Revenue Code Section 104(a)(2), as explained in IRS Publication 4345.
- Ownership: The injured person usually receives payments but does not own the annuity contract. The assignment company or insurer commonly owns it.
| Rule or fact | Specific figure | Source |
| Federal tax penalty for buying structured settlement payment rights without a qualified court order | 40% excise tax | Internal Revenue Code Section 5891 |
| General exclusion for physical injury or physical sickness damages | Section 104(a)(2) | IRS Publication 4345 and Internal Revenue Code Section 104(a)(2) |
| Federal law authorizing qualified assignments for periodic payments | Section 130 | Internal Revenue Code Section 130 |
Payouts may include level monthly income, increasing payments, lump sums at set ages, or lifetime payments.
For example, a minor’s settlement might delay major payouts until adulthood, while an adult with medical needs may choose regular income plus scheduled medical lump sums.
Caution: Payment timing is legally important. A reader should not rely on general examples to change, sell, or assign payments.
The settlement agreement, court order, annuity contract, and state structured settlement protection act control the actual rights.
If a payee later wants cash instead of future payments, the transaction is usually called a structured settlement transfer.
Federal law discourages transfers without court approval by imposing the 40% excise tax under IRC Section 5891 when no qualified order exists.
State courts typically review whether the transfer is in the payee’s best interest and whether disclosures were made.
State requirements vary, so the payee should check the applicable state statute and obtain independent legal or financial advice before signing anything.
Common payout schedules and payment types
Structured settlement payouts are usually designed around predictable future needs, not a single cash payment. The schedule is written into the settlement agreement and typically funded through an annuity issued by a life insurance company.
Under Internal Revenue Code Section 104(a)(2), damages received for personal physical injuries or physical sickness are generally excluded from federal gross income.
Internal Revenue Code Section 130 also recognizes “qualified assignments,” a common structure used to transfer the payment obligation to an assignment company.
| Payout type | How it works | Common use |
| Monthly payments | Equal payments made every month for a fixed period or for life. | Rent, food, utilities, caregiving, or wage replacement. |
| Annual payments | One payment each year, often on a set anniversary date. | Insurance premiums, property taxes, tuition, or planned expenses. |
| Deferred payments | Payments start at a later date, such as when a minor reaches adulthood. | College funding or transition to independent living. |
| Lump-sum installments | Larger scheduled payments at specific future dates. | Vehicle replacement, home modifications, surgery, or education costs. |
| Life-contingent payments | Payments continue only while the payee is alive, unless a guarantee period is included. | Long-term income support for serious injury cases. |
The National Structured Settlements Trade Association describes structured settlements as flexible arrangements that may include monthly, annual, future lump-sum, or lifetime payments.
The exact pattern depends on the settlement documents, the annuity contract, and court approval when required.
- Period-certain payments: Payments are made for a stated term, such as 10, 20, or 30 years. If the payee dies during the guaranteed period, remaining payments may go to a named beneficiary, depending on the contract.
- Life with period certain: Payments continue for life, but a minimum number of years is guaranteed. This can reduce the risk that payments stop shortly after the annuity begins.
- Cost-of-living increases: Some settlements include scheduled increases, such as fixed annual step-ups. Inflation protection is not automatic and must be stated in the payment schedule.
- Minor’s settlements: Courts often require special handling when the injured person is a child. Payment timing may be coordinated with age 18, college years, or guardianship rules.
Plain caution: a payout schedule can affect taxes, public benefits, medical planning, and family support.
Readers should not rely on a sample schedule alone; they should review the settlement agreement, annuity contract, and applicable state court rules with qualified legal and tax professionals.
Taxes on structured settlement payouts
Most structured settlement payouts for personal physical injuries are not taxable at the federal level, but the reason for the settlement matters.
The tax result can change if the award includes punitive damages, interest, wage claims or non-physical emotional distress.
The core federal rule is Internal Revenue Code Section 104(a)(2).
It excludes from gross income damages received “on account of personal physical injuries or physical sickness,” whether paid as a lump sum or through periodic structured settlement payments.
| Payment type | Typical federal tax treatment | Primary source |
| Personal physical injury or physical sickness damages | Generally excluded from federal gross income | Internal Revenue Code Section 104(a)(2); IRS Publication 4345 |
| Qualified structured settlement periodic payments | Generally tax-free if the underlying damages qualify under Section 104(a)(2) | Internal Revenue Code Sections 104(a)(2) and 130; IRS Publication 4345 |
| Punitive damages | Taxable, even if related to a physical injury case, except limited wrongful-death exceptions | IRS Publication 525; Internal Revenue Code Section 104 |
| Pre-judgment or post-judgment interest | Taxable as interest income | IRS Publication 525 |
| Emotional distress not caused by physical injury or sickness | Generally taxable, except qualifying medical-cost amounts | IRS Publication 525; Internal Revenue Code Section 104(a) |
A qualified assignment can preserve the tax treatment of future payments.
Under Internal Revenue Code Section 130, an assignment company may assume the payment obligation if statutory conditions are met, including that payments are fixed and determinable.
There is also a special federal rule for selling structured settlement payment rights.
Internal Revenue Code Section 5891 imposes a 40% excise tax on the factoring discount unless the transfer receives required court approval under a qualified state structured settlement protection act.
That 40% excise tax is generally aimed at the purchaser or factoring company, not the injured person. However, a seller should not assume the transaction is tax-free in every respect, especially if the original settlement included taxable components.
- Check the settlement agreement: It should allocate damages among physical injury, punitive damages, interest and other categories.
- Review Form 1099 reporting: Taxable portions may be reported by the payer, but taxability does not depend only on receiving a form.
- Consider prior medical deductions: IRS rules can require income recognition if previously deducted medical expenses are later reimbursed.
- Check state law: States often follow federal treatment, but not always.
Caution: Tax treatment turns on the exact claims, wording of the settlement documents and state rules. A reader should consult a qualified tax professional before selling payments, filing a return or relying on a settlement allocation.
Selling rights to future payouts
Selling structured settlement payments means transferring the legal right to some future annuity payments to a factoring company in exchange for a smaller lump sum today.
This is not a simple “cash-out”; it is a court-supervised transaction with long-term financial consequences.
Under Internal Revenue Code § 5891.
A buyer can face a 40% federal excise tax on the factoring discount unless the transfer is approved in a “qualified order.” That order generally must find the sale is in the payee’s best interest and complies with applicable.
State structured settlement protection law.
| Item | What it means | Source |
| 40% excise tax | Federal tax imposed on certain structured settlement factoring transactions that lack a qualified court order. | Internal Revenue Code § 5891 |
| Court approval | A judge typically reviews disclosures, discount rate, fees, and the seller’s financial needs before approving a transfer. | State structured settlement protection acts; IRC § 5891 |
| Present-value pricing | The lump sum is discounted because the buyer waits to collect future payments and prices risk, profit, and costs. | U.S. Securities and Exchange Commission, Investor.gov explanation of present value |
The “discount rate” is central. A higher discount rate means the seller receives less cash today for the same future payments.
Fees, court costs, and administrative charges can reduce proceeds further, so the headline offer may not equal the final amount received.
| Example only | Calculation | Estimated present value |
| $50,000 due in 5 years | Discounted at 8% annually using standard present-value math | About $34,029 |
| $50,000 due in 5 years | Discounted at 12% annually using standard present-value math | About $28,371 |
| $50,000 due in 5 years | Discounted at 18% annually using standard present-value math | About $21,859 |
These figures are illustrative calculations, not market quotes. Actual offers depend on payment dates, insurer rating, state law, competition among buyers, and transaction costs. A reader should not rely on an example table to decide whether to sell.
- Partial sale: The seller transfers only selected payments, such as 24 monthly checks or one future lump sum.
- Full sale: The seller transfers all remaining payments, which can permanently remove future income.
- Split sale: The seller keeps part of each payment and sells the rest, if allowed by the contract and court.
A cautious seller should compare written offers, ask for the effective discount rate, review all fees, and verify whether the annuity issuer or settlement documents restrict transfers.
Independent legal or financial advice is important before signing anything.
Court approval and state transfer rules
Selling structured settlement payment rights usually requires a judge’s approval under a state Structured Settlement Protection Act.
The core test is whether the transfer is in the payee’s “best interest,” but notice periods, required disclosures and hearing rules vary by state.
A federal tax rule creates the strongest incentive to use the court process.
Internal Revenue Code Section 5891 imposes a 40% excise tax on the factoring discount if a transfer is not approved in a “qualified order” by an applicable state court or responsible administrative authority.
| Rule or requirement | Specific figure | Source |
| Federal penalty for nonqualified transfer | 40% excise tax on the factoring discount | Internal Revenue Code Section 5891 |
| New York notice before hearing | At least 20 days’ written notice to interested parties | New York General Obligations Law Section 5-1705 |
| Florida notice before hearing | At least 20 days before the hearing | Florida Statutes Section 626.99296 |
| Texas notice before hearing | Not less than 20 days before the hearing | Texas Civil Practice and Remedies Code Section 141.006 |
State statutes commonly require disclosure of the payments being sold, the gross advance amount, itemized fees, the net amount payable, and the discount rate.
Many states also require the petition to be served on the annuity issuer, structured settlement obligor and other interested parties.
- Best-interest review: Courts usually consider the payee’s financial needs, dependents, age, employment, medical situation and whether the sale would undermine long-term support.
- Independent professional advice: Some statutes require advice from an attorney, accountant or other licensed professional, or require the payee to knowingly waive that advice in writing.
- No automatic approval: Even when documents are complete, a judge may reject a transfer if the price is too low, the reason is weak, or the payee appears pressured.
- Prior transfers matter: Courts may review earlier sales because repeated transfers can reduce future guaranteed income and affect the best-interest finding.
Important caution: a quoted lump sum is not the same as the present value of the payments.
Readers should compare the disclosed discount rate, all fees and the net amount, and should not rely on a buyer’s summary without reading the filed petition.
Procedures are state-specific. For example, venue, filing forms, guardian rules for minors, and the treatment of workers’ compensation or medical malpractice settlements can differ.
Readers should check the current statute, court rules and original settlement documents before acting.
Because a transfer can permanently give up tax-advantaged future payments, legal or financial advice is prudent before signing. A court order confirms statutory compliance; it does not guarantee that selling payments is the best financial choice.
What the editorial team reviewed
We reviewed structured settlement payout information from primary legal, tax and court sources, then compared it with sample transfer disclosures and state approval requirements.
The goal was to separate guaranteed payment facts from estimates that can change with discount rates, court findings and contract terms.
We repeated each calculation twice: once from the stated future payment schedule and once from the present-value figure shown in the disclosure.
Where the two results did not match, we treated the disclosure as needing clarification rather than assuming the buyer’s number was correct.
| Item reviewed | Quantity or source | What we checked |
| Federal tax treatment | IRS Publication 4345 and Internal Revenue Code Section 104(a)(2) | Whether personal physical injury settlement payments are generally excluded from federal income tax. |
| Transfer penalty rule | Internal Revenue Code Section 5891 | The 40% federal excise tax imposed on a structured settlement factoring transaction that is not approved by a qualified court order. |
| State approval framework | State structured settlement protection acts and court order requirements | Whether a judge must find the sale is in the payee’s best interest and complies with required disclosures. |
| Payment math | Repeated present-value checks using the disclosed payment dates, amounts and purchase price | Whether the stated lump sum was consistent with the future payout stream and implied discounting. |
We focused on payout terms that materially affect a recipient’s money: payment amount, payment frequency, start date, end date, guaranteed period, beneficiary rights, commutation language and anti-assignment restrictions.
A payout that looks simple can change meaning if payments are life-contingent instead of guaranteed.
- We checked whether examples distinguished monthly, annual, lump-sum and deferred payments.
- We compared “present value,” “net advance amount” and “gross purchase price,” because those terms are not interchangeable.
- We reviewed whether court approval was described as mandatory for transfers, not as a formality.
- We looked for warnings about lost future income, Medicaid or SSI eligibility, taxes and creditor exposure.
One caution is essential: readers should not sell, borrow against or restructure payments based only on an article.
A structured settlement payout can involve tax law, state court approval, insurance contract restrictions and public-benefit rules, so the primary documents and independent legal or financial advice matter.
We also checked language for overstatements. A company can estimate a lump-sum offer, but the final amount depends on underwriting, the payment stream, the discount rate, fees and the judge’s approval.
No article can make that decision for a payee.
Risks before changing payout rights
Changing structured settlement payout rights usually means selling future payments for a smaller lump sum.
That can solve an urgent cash problem, but it also can permanently reduce guaranteed income and may affect taxes, benefits, and court-approved protections.
Plain caution: Do not sign a transfer agreement based only on advertising, a verbal quote, or this article. Ask the court, a qualified attorney, and a tax professional to review the actual contract and disclosure statement.
| Risk | Specific rule or fact | Source |
| Large tax penalty if approval is invalid | Federal law imposes a 40% excise tax on the factoring discount unless the transfer is approved by a “qualified order.” | Internal Revenue Code § 5891 |
| Loss of tax-preferred injury payments | Damages received on account of personal physical injuries or physical sickness are generally excluded from gross income, but later transactions can create separate tax issues. | Internal Revenue Code § 104(a)(2) |
| State court review | Many state structured settlement protection acts require a judge to find that the transfer is in the payee’s best interest before payment rights can be sold. | State structured settlement protection acts; check the statute in the filing state |
| Loss of annuity safety-net value | State guaranty association coverage for annuity benefits is commonly capped; the National Organization of Life and Health Insurance Guaranty Associations says many states provide up to $250,000 in present-value annuity coverage. | NOLHGA policyholder protection materials |
- The lump sum is not the same as the future payment total. A buyer applies a discount rate and may subtract costs. The court disclosure should show the present value, gross purchase price, net amount paid, and effective annual discount rate.
- The decision can be irreversible. Once a judge approves the transfer and the annuity issuer redirects payments, the seller may not be able to reclaim those future payments later.
- Public benefits can be affected. A lump sum may count as income or a resource for means-tested programs such as Medicaid or Supplemental Security Income. The Social Security Administration sets SSI resource limits at $2,000 for an individual and $3,000 for a couple.
- Minors and dependents need extra protection. If future payments were designed for medical care, housing, or child support, selling them can shift long-term risk back to the injured person or family.
- Forum and timing matter. Court approval standards, notice rules, cooling-off rights, and required disclosures vary by state. Verify the exact statute and court order, not just the buyer’s summary.
Before changing payout rights, compare the after-fee lump sum with the purpose of the original settlement. A short-term cash need should be weighed against the loss of scheduled, court-protected payments over time.
Frequently Asked Questions
What is a structured settlement payout?
A structured settlement payout is a scheduled payment stream, often funded through an annuity, that resolves a personal injury, workers’ compensation, or similar legal claim.
The Internal Revenue Service explains that damages for personal physical injuries or physical sickness are generally excluded from income under IRC Section 104(a)(2), but tax treatment depends on the facts.
So recipients should confirm with a qualified tax professional before acting.
How are structured settlement payouts usually paid?
Payments may be made monthly, annually, in lump-sum installments, or through a mix of recurring and future lump-sum payments, depending on the settlement agreement and annuity contract.
Because the payment schedule is legally documented and may be difficult to change, a recipient should review the court order, settlement documents, and annuity contract before making financial commitments.
Can a structured settlement payout be sold for cash?
Many states allow a recipient to transfer some or all future structured settlement payments to a purchasing company, but transfers generally require court approval under state structured settlement protection acts.
The Consumer Financial Protection Bureau warns that selling future payments can be costly because the cash received is typically less than the total future payments, so recipients should compare the discount rate, fees, and alternatives before agreeing.
Are structured settlement payouts guaranteed?
Structured settlement payments are commonly backed by a life insurance company annuity, but the security depends on the insurer’s financial strength and any applicable state guaranty association limits.
The National Organization of Life and Health Insurance Guaranty Associations states that coverage limits vary by state, so recipients should check the issuing insurer, the state guaranty association.
And the contract terms rather than assuming full protection.
Do structured settlement payouts affect public benefits?
Structured settlement payouts can affect needs-based benefits such as Medicaid or Supplemental Security Income if payments are counted as income or resources.
The Social Security Administration’s SSI rules are strict and fact-specific, so anyone receiving or expecting benefits should speak with a benefits attorney or qualified adviser before changing, selling, or redirecting settlement payments.
Related Reading
- Structured Settlement Quotes
- Vanguard Immediate Annuity Rates
- Vanguard Annuity Calculator
- Structured Settlement Loans – What You Need to Know
- Structured Settlement Annuity Companies
- Structured Settlement Collection Agency
- Structured Settlement Sale
- All Blog Guides
Sources & References:
- Internal Revenue Service, Publication 4345: Settlements — Taxability (2022)
- Internal Revenue Service, Tax Implications of Settlements and Judgments (2024)
- Legal Information Institute, Cornell Law School, 26 U.S. Code § 104 — Compensation for Injuries or Sickness (2024)
- Legal Information Institute, Cornell Law School, 26 U.S. Code § 130 — Certain Personal Injury Liability Assignments (2024)
- Consumer Financial Protection Bureau, CFPB Sues Access Funding for Illegally Steering Consumers into High-Cost Loans (2016)
- National Association of Insurance Commissioners, Structured Settlements (2024)
- National Conference of Insurance Legislators, Structured Settlements Protection Act (2016)