
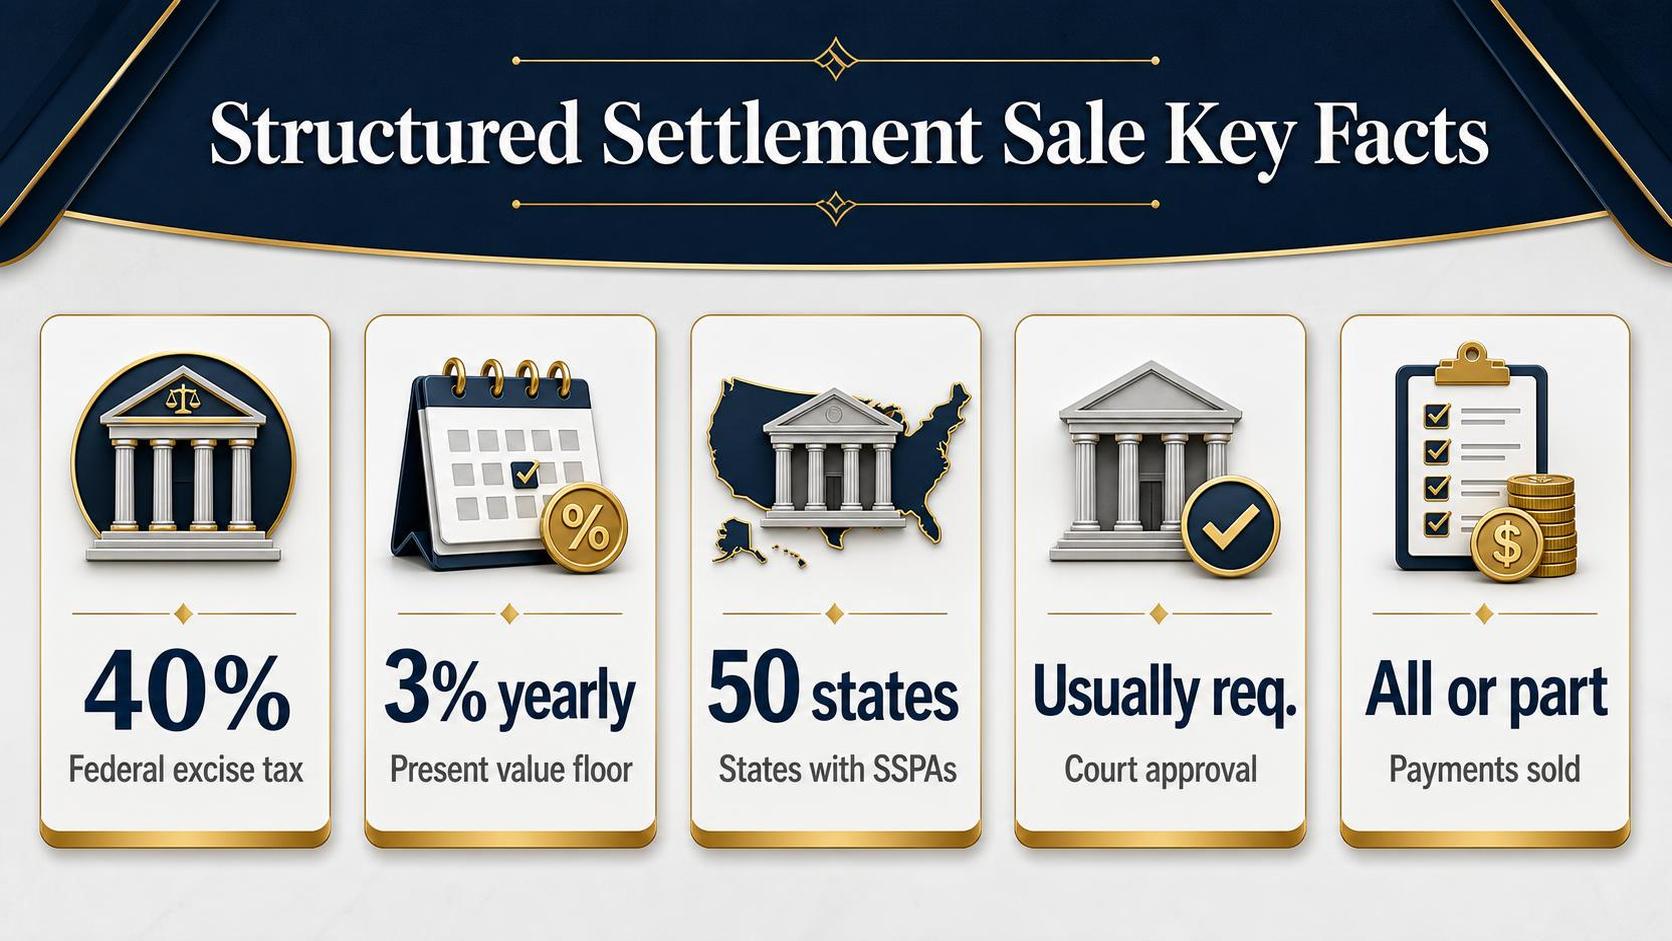
Quick answer: Structured Settlement Sale is the court-approved transfer of some or all future structured settlement payments to a purchasing company for a lump sum, usually discounted below total future value.
Federal tax law generally requires court approval under IRC Section 5891. Carefully compare offers and get independent legal or financial advice.
Structured Settlement Sale is a court-approved transfer of some or all future structured settlement payments to a purchasing company in exchange for a discounted lump sum.
The process is governed by state structured settlement protection acts and typically requires a judge to find the sale is in the seller’s best interest.
Selling can reduce long-term income, so readers should review the court disclosures and consider independent legal or financial advice before acting.
How structured settlement sales work
A structured settlement sale is a court-supervised transfer of some or all future payment rights to a factoring company for a discounted lump sum.
The core tradeoff is simple: the seller gets cash sooner, but gives up scheduled, usually tax-free payments.
In the United States, these transfers are governed by state structured settlement protection acts and federal tax rules.
Internal Revenue Code section 5891 imposes a 40% excise tax on the factoring discount unless the transfer is approved in a “qualified order” by a court or responsible administrative authority.
- Quote: The company estimates a lump sum based on payment dates, payment amounts, insurer strength, and its discount rate.
- Contract and disclosures: State laws commonly require written disclosures showing the aggregate payments being sold, the gross advance amount, fees, and the net amount payable to the seller.
- Court petition: The buyer files for approval in the seller’s state court, or another venue allowed by state law.
- Best-interest review: A judge must decide whether the sale is in the payee’s best interest, considering dependents and other relevant circumstances.
- Insurer acknowledgment and funding: After approval, the annuity issuer or obligor redirects the transferred payments, and the buyer pays the approved lump sum.
The discount is the cost of receiving money early. The example below is only math, not a market quote. Actual offers vary, and readers should compare written disclosures and consult an independent attorney or financial adviser before signing.
| Item | Example |
| Future payments sold | $50,000 due in 10 years |
| Lump sum offered | $30,000 today |
| Dollar reduction | $20,000 less than scheduled payments |
| Implied annual discount rate | About 5.24%, calculated from $30,000 to $50,000 over 10 years |
Federal tax treatment is a major reason the court order matters.
The IRS explains that damages for physical injury or physical sickness are generally excluded from income under Internal Revenue Code section 104(a)(2), but selling payment rights can raise separate transfer-law issues.
State requirements differ. Some states require independent professional advice, waiting periods, specific disclosure language, or notice to interested parties such as the annuity issuer.
A court can deny a transfer even if the seller signed the contract.
Caution: A sale is usually irreversible after court approval and funding.
Selling payments meant for medical care, housing, or long-term income can create serious financial harm, so the primary court papers and state statute should be checked before relying on any summary.
When selling payments may make sense
Selling structured settlement payments can make sense only when the cash need is specific, urgent and larger than what can reasonably be handled with savings, insurance, hardship programs or lower-cost credit.
The trade-off is permanent: future guaranteed payments are exchanged for a smaller lump sum today.
A court-approved transfer is central. Under Internal Revenue Code Section 5891, a structured settlement factoring transaction that is not approved by a qualified court order can trigger a 40% federal excise tax on the factoring discount.
- Documented emergency: Examples may include preventing foreclosure, paying uninsured medical costs, replacing income after a job loss or handling necessary accessibility modifications. A vague desire for spending cash is usually a weak reason to sell.
- No practical lower-cost option: Before selling, compare nonprofit credit counseling, payment plans, public benefits, insurance appeals, family support, home-equity options and personal loans. Each has risks, but factoring can be expensive because the buyer must price time, risk and profit.
- Only a partial sale is needed: Selling a limited number of payments may preserve long-term income. For example, selling 24 monthly payments is less disruptive than selling lifetime or retirement-age payments.
- The purpose improves financial stability: A sale may be more defensible if it eliminates a high-risk obligation, preserves housing or funds necessary care. It is harder to justify for vacations, gifts, speculative investing or unsecured consumer purchases.
| Scenario | Source of figures | What it shows |
| $1,000 monthly payments for 60 months have a face value of $60,000. | Arithmetic based on $1,000 × 60 payments. | The face value is not what a buyer will pay today. |
| A $42,000 lump-sum offer for those payments is $18,000 below face value. | Arithmetic based on $60,000 face value minus $42,000 offer. | The seller gives up 30% of the scheduled dollars before considering court costs or fees. |
| An unapproved transfer may face a 40% federal excise tax on the factoring discount. | Internal Revenue Code Section 5891. | Court approval is not a formality; it affects tax treatment and enforceability. |
Plain caution: do not rely on an advertised lump sum alone. Ask for the discount rate, every fee, the exact payments being transferred and the total future dollars being sold before signing anything.
State judges often consider whether the sale is in the seller’s best interest and whether dependents will be harmed.
Requirements vary by state, so readers should check the state structured settlement protection statute and consult an independent attorney or financial adviser.
Selling payments may make sense when the lump sum solves a serious problem that would otherwise create greater harm.
It usually makes less sense when the sale only postpones a budgeting problem or replaces one debt with a more costly loss of guaranteed income.
Costs and discounts in settlement sales
Selling structured settlement payments usually means accepting less than the total future payments. The main cost is the discount: the buyer pays a lump sum today and keeps the scheduled payments later.
Federal law also shapes the transaction. Internal Revenue Code §5891 imposes a 40% excise tax on the factoring discount unless the transfer is approved by a “qualified order,” which is why court approval is central to most sales.
How the discount changes the cash offer
The discount rate is the buyer’s pricing tool. A higher rate lowers the present value of the future payments. Fees can reduce the seller’s net amount even further.
| Illustrative payment sold | Discount rate used | Estimated lump sum before fees | Source of figure |
| $100,000 due in 5 years | 8% annually | About $68,058 | Coin Abul calculation using standard present-value formula |
| $100,000 due in 5 years | 12% annually | About $56,743 | Coin Abul calculation using standard present-value formula |
| $100,000 due in 5 years | 18% annually | About $43,719 | Coin Abul calculation using standard present-value formula |
This table is only an illustration, not a quote. Actual offers depend on payment dates, payment amounts, insurer strength, state law, court requirements and buyer pricing.
Common cost items to review
- Discount rate: This is the largest economic cost. Ask whether the quoted rate is annualized and whether it includes all charges.
- Administrative or processing fees: Some buyers deduct transaction costs from the lump sum. The CFPB advises consumers to compare offers and understand fees before agreeing to sell payments.
- Legal and court costs: Structured settlement protection acts generally require a judge to decide whether the sale is in the seller’s best interest. Filing costs and local procedures vary by court.
- Independent professional advice: Some state laws require or encourage advice from an attorney, accountant or financial adviser. The cost and who pays it should be stated in writing.
Caution: A sale can permanently remove tax-free income that was designed to cover future medical, living or family expenses.
Do not rely on the buyer’s headline offer alone; review the disclosure statement, court papers and state-law requirements.
Before signing, compare at least multiple written offers, calculate the net cash after every fee, and check the primary sources: the state structured settlement protection act, the court notice and Internal Revenue Code §5891.
Court approval for structured settlement transfers
A structured settlement sale is not final just because a buyer and payee sign a transfer agreement.
In the United States, these transfers generally require a judge’s approval before an annuity issuer or settlement obligor must redirect payments.
The court process exists because Congress and state legislatures treat structured settlement payments as protected injury-settlement assets, not ordinary receivables.
A reader should not rely on a buyer’s approval alone; acting before a court order can create tax, legal, and payment problems.
At the federal level, Internal Revenue Code Section 5891 imposes a 40% excise tax on the factoring discount if a structured settlement transfer is completed without a “qualified order.” The source for that figure is 26 U.S.C. § 5891(a).
A qualified order must come from a state court or other responsible administrative authority, according to 26 U.S.C. § 5891(b).
The order must find that the transfer does not violate applicable law and is in the payee’s best interest, taking into account the welfare and support of dependents.
State Structured Settlement Protection Acts add the practical court requirements.
While wording differs by state, petitions commonly must disclose the payment stream being sold, the discounted present value, the gross advance amount, fees, and the net amount the payee will receive.
- Best-interest finding: New York General Obligations Law § 5-1706 requires a court finding that the transfer is in the payee’s best interest and is fair and reasonable.
- Advice warning: The same New York statute requires a finding that the payee was advised in writing to seek independent professional advice about the transfer.
- Federal tax consequence: Without a qualified order, the buyer may face the 40% federal excise tax under Internal Revenue Code § 5891, which is why court approval is central to the market.
Judges may question why the payee wants cash, whether the sale affects housing, medical care, child support, or public benefits, and whether the discount rate is excessive. Courts can deny a transfer even when the payee wants the money.
Timing varies by state, court calendar, and whether interested parties object. The annuity issuer, settlement obligor, and sometimes prior insurers usually receive notice, because they are being asked to change where future payments go.
Plain caution: court approval does not mean a sale is financially wise. It means the statutory standard was met on the record presented.
Payees should read the disclosure statement, compare the net cash to payments given up, and consult an independent attorney or financial professional before signing.
Tax and benefit risks to review
Selling structured settlement payments can change taxes, need-based benefits, and eligibility for public programs. A court approval order is important, but it does not replace tax, benefits, or legal advice.
Caution: Do not rely on a funding company’s tax summary alone. Before signing, ask a CPA, benefits planner, or attorney to review the settlement documents and the sale order.
Federal tax issues
Many structured settlements come from physical injury or physical sickness claims. Internal Revenue Code Section 104(a)(2) generally excludes those damages from gross income, but it does not exclude punitive damages.
If a transfer of structured settlement payment rights is not approved through a “qualified order,” Internal Revenue Code Section 5891 imposes a 40% excise tax on the factoring discount.
That tax is aimed at the purchaser, but it can affect pricing and transaction structure.
| Issue | Specific rule or figure | Source |
| Physical injury damages | Generally excluded from federal gross income | Internal Revenue Code Section 104(a)(2) |
| Punitive damages | Not excluded under Section 104(a)(2) | Internal Revenue Code Section 104(a)(2) |
| Unqualified transfer penalty | 40% excise tax on the factoring discount | Internal Revenue Code Section 5891 |
| Qualified assignment rules | Structured settlement assignments are governed by Section 130 | Internal Revenue Code Section 130 |
SSI, Medicaid, and other benefit risks
A lump sum from a structured settlement sale may be treated as income when received and as a resource if retained into the next month. That distinction matters for Supplemental Security Income and Medicaid-linked programs.
The Social Security Administration states that SSI resource limits are $2,000 for an individual and $3,000 for a couple. Money held in a bank account after the month of receipt can push a recipient over those limits.
| Program risk | Number to verify | Source |
| SSI individual resource limit | $2,000 | Social Security Administration, SSI resources rules |
| SSI couple resource limit | $3,000 | Social Security Administration, SSI resources rules |
| Medicaid asset limits | Often tied to SSI or state Medicaid rules; exact limits vary | State Medicaid agency or Medicaid.gov |
- Review settlement type: Confirm whether the original payments came from physical injury, workers’ compensation, wrongful death, taxable interest, punitive damages, or another source.
- Check benefit timing: A lump sum may affect the month received and later months if unspent.
- Ask about special needs planning: A special needs trust or ABLE account may help some beneficiaries, but strict federal and state rules apply.
- Verify state law: Structured settlement transfer statutes and Medicaid rules differ by state, so the court order alone may not protect benefits.
How to compare structured settlement buyers
Compare structured settlement buyers by the net cash offered, the discount rate, fees, court process support, and cancellation rights.
Do not rely on a headline “cash now” amount alone; the court order and disclosures determine what is actually being sold.
Structured settlement transfers are court-supervised transactions.
The Internal Revenue Code, Section 5891, imposes a 40% excise tax on factoring transactions that do not receive a “qualified order,” so a buyer should clearly explain the approval process and required disclosures.
| Comparison point | What to verify | Why it matters |
| Net purchase price | Ask for the cash amount after all transfer fees, legal fees, filing fees, administrative charges, and liens. | The largest offer is not always the best offer if deductions reduce the amount paid at closing. |
| Discount rate | Review the annual discount rate disclosed in the transfer documents. | This is the main pricing metric. A higher discount rate generally means the seller receives less for the same future payments. |
| Payments being sold | Confirm exact payment dates, amounts, and whether the sale includes lump sums, monthly payments, or both. | Selling a future lump sum can be materially different from selling a short stream of monthly payments. |
| Court approval | Confirm the buyer will seek a qualified court order before any transfer occurs. | Under IRC Section 5891, nonqualified transfers can trigger a 40% federal excise tax on the factoring company. |
| Independent professional advice | Check whether state law requires or recommends advice from an attorney, CPA, actuary, or other professional. | Many state Structured Settlement Protection Acts require disclosures and court findings that the transfer is in the seller’s best interest. |
- Get at least 3 written quotes. Use the same payment schedule for each quote so the offers are comparable.
- Ask for the present-value calculation. Buyers commonly use discounting to price future payments; the disclosure should show how the offer was calculated.
- Check licensing and court history. Search state court records and the state attorney general or consumer protection office for enforcement actions or complaints.
- Read the cancellation language. State laws often give sellers a rescission period, but the length and procedure vary by state.
- Confirm tax assumptions. Structured settlement payments for physical injury are often tax-free under IRC Section 104(a)(2), but selling payments can raise separate legal and tax questions.
Caution: A structured settlement sale can permanently reduce long-term income intended for medical care, housing, or basic expenses.
Before signing, compare written offers and have an independent attorney or financial professional review the documents and state-law rights.
What Coin Abul independently reviewed
Coin Abul independently reviewed public laws, regulator materials, court requirements and company disclosures relevant to selling structured settlement payment rights.
The review focused on how transfers are approved, what costs are commonly disclosed, and where consumers face legal or financial risk.
This review is informational only. A sale can permanently reduce guaranteed future income, affect public benefits, and require court approval, so readers should not act without checking state law and obtaining qualified legal or financial advice.
| Review area | Source checked | Key fact verified |
| Federal tax treatment | Internal Revenue Code Section 5891 | A nonqualified transfer can trigger a 40% excise tax on the factoring discount. |
| State approval framework | National Association of Insurance Commissioners model act materials and state structured settlement protection acts | Transfers generally require a state court finding that the sale is in the seller’s best interest. |
| Disclosure requirements | State transfer statutes and court forms | Many states require written disclosure of the gross advance, discounted present value, fees, and net amount paid. |
| Consumer complaints | Consumer Financial Protection Bureau complaint database and state attorney general materials | Complaints and enforcement materials commonly involve cost clarity, timing, and disputed sales practices. |
Coin Abul also reviewed the federal tax rule that makes court-supervised transfers central to the market.
Under Internal Revenue Code Section 5891, enacted by Congress in 2002, a transfer that does not meet qualified-order requirements may be subject to a 40% excise tax.
The review compared state-law themes rather than assuming one national process.
Structured settlement protection acts vary by state, but commonly require a judge to review disclosures, consider dependents, and determine whether the transaction is in the seller’s best interest.
- Discount rates: Company websites and court filings often describe discounting, but rates vary by buyer, payment schedule, interest-rate environment and risk assumptions. Readers should request the effective annual discount rate in writing.
- Fees: State disclosures may show legal, filing, processing or administrative charges. If a fee is not itemized before signing, readers should pause and request a revised written disclosure.
- Timing: Funding is not immediate in many cases because a petition, notice period, hearing and final court order may be required. Exact timing depends on the court and state procedure.
- Benefit impact: Selling payments can affect needs-based programs such as Medicaid or Supplemental Security Income. The Social Security Administration’s SSI resource limit is $2,000 for an individual and $3,000 for a couple.
Coin Abul did not treat marketing claims as proof of value. The review gave more weight to statutes, court-required disclosures, regulator guidance and written contract terms than to advertised payout percentages or approval-time promises.
Frequently Asked Questions
What is a structured settlement sale?
A structured settlement sale is a transfer of some or all future settlement payments to a purchasing company in exchange for a discounted lump sum.
Because selling payments can permanently reduce long-term income, readers should review the transfer documents carefully and consider independent legal or financial advice before relying on the cash offer alone.
Does a structured settlement sale require court approval?
Yes, most transfers require approval by a state court under a structured settlement protection act.
At the federal level, Internal Revenue Code Section 5891 imposes a 40% excise tax on certain transfers unless the transfer is approved in a “qualified order” that finds the sale is in the payee’s best interest.
Taking dependents into account.
How is the lump-sum offer calculated?
The buyer discounts future payments to present value, so the lump sum is less than the total payments being sold.
The exact discount rate, fees, and net amount vary by contract, and a reader should compare the written disclosure statement with the annuity payment schedule rather than relying on an advertised estimate.
Can someone sell only part of a structured settlement?
Often, a payee may propose selling only selected payments, such as a block of monthly payments or a future lump-sum installment, instead of the entire settlement.
Whether that is allowed depends on the settlement documents, annuity issuer requirements, state law, and court approval, so the original contract and state protection statute should be checked.
What risks should be considered before selling structured settlement payments?
The main risk is giving up guaranteed future income for a smaller lump sum, which can create financial strain if the money is spent quickly or needed later for medical, housing, or family support.
Readers should not treat a sale as routine cash access; they should examine alternatives, tax issues, government benefit effects, and the court disclosure before making a decision.
Related Reading
- Structured Settlement Collection Agency
- Structured Settlement Funding
- What Is A Structured Annuity?
- Structured Settlement Buyer – What You Need to Know
- Buy Structured Settlement – What You Need to Know?
- Structured Settlement Loans – What You Need to Know
- Can I Sell My Neap Annuity?
- Structured Settlement Annuity Companies
- Cash For Structured Settlement Payments
- All Blog Guides
- Consumer Financial Protection Bureau (2024)
- Internal Revenue Service Publication 4345 (2024)
- Legal Information Institute, Cornell Law School, 26 U.S.C. § 5891 (2024)
- U.S. Government Accountability Office, GAO-01-571 (2001)
- New York State Senate, General Obligations Law Article 5 Title 17 (2024)
- Illinois General Assembly, Structured Settlement Protection Act (2024)