
Quick answer: Why Are New Car Prices So High: new cars cost more because automakers built fewer low-priced models, added expensive technology, and faced higher labor, materials, and financing costs.
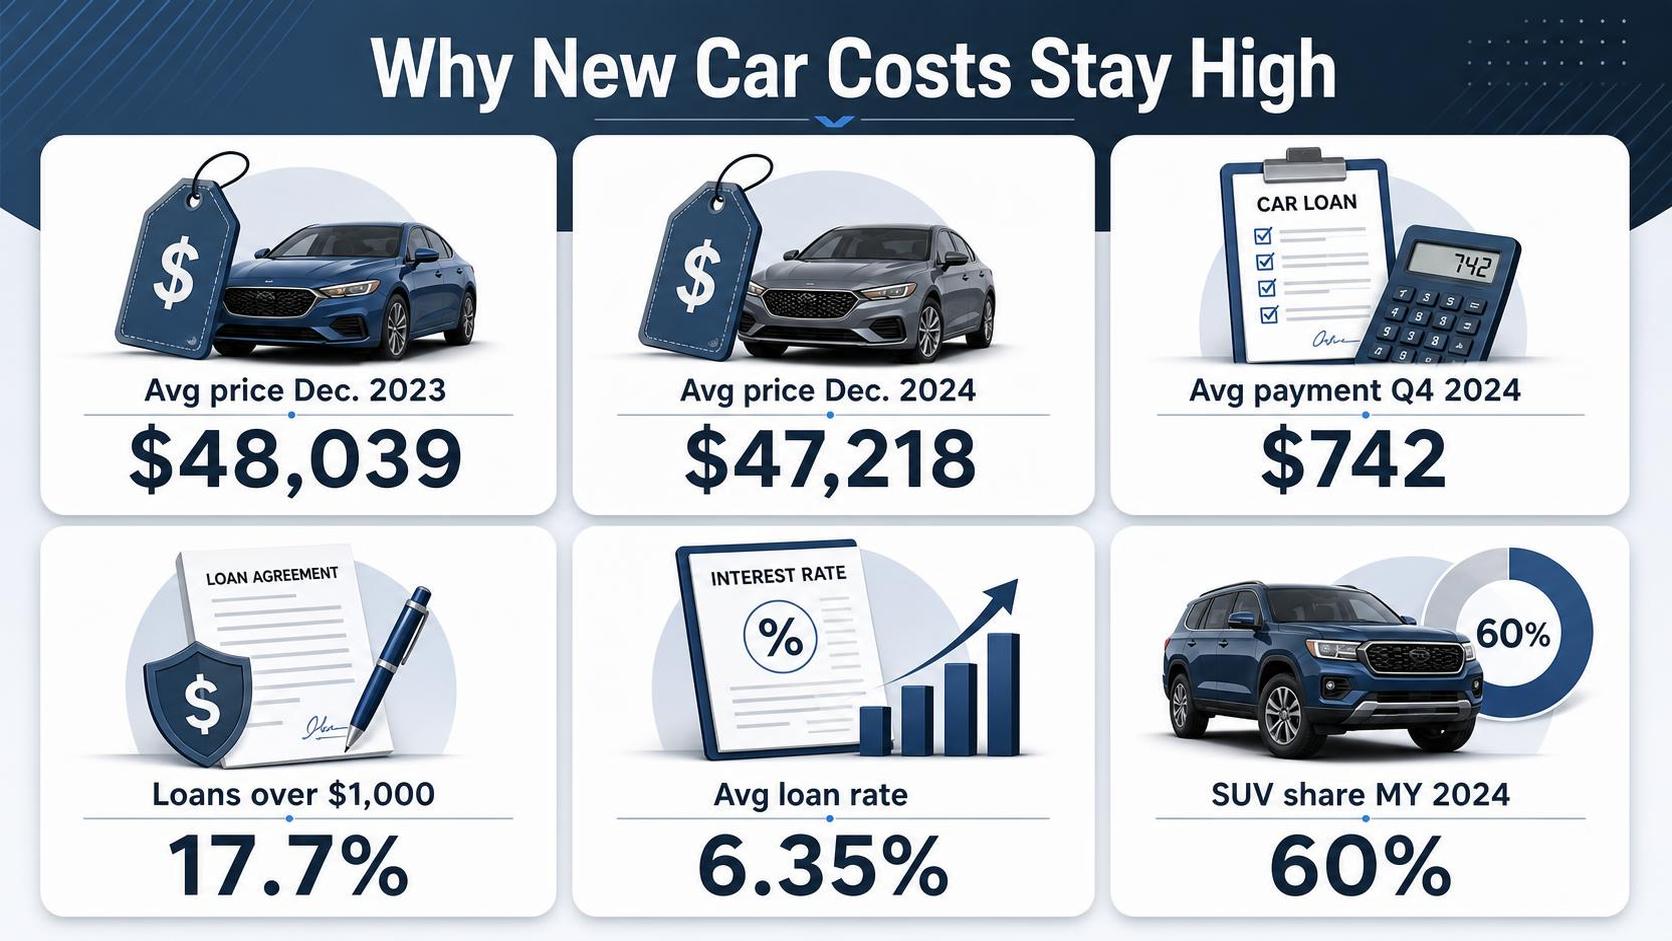
Kelley Blue Book reported the average U.S. new-vehicle transaction price was $48,644 in June 2024, keeping affordability strained.
Why Are New Car Prices So High is answered by costly supply, technology and financing: Kelley Blue Book put the average U.S. new-vehicle transaction price at $48,644 in June 2024, while Cox Automotive said incentives remained below pre-pandemic norms.
For budgeting, the payment is not the price: financing $40,000 for 60 months at 7% APR costs about $47,522 before taxes and fees. Prices often soften near model-year changeovers and year-end.
Used, waiting, or repairing may be safer if debt strains essentials; check lender disclosures before signing.
Why new car prices remain high
New-car prices remain high because the market reset upward during the pandemic and has not fully reversed.
Kelley Blue Book, a Cox Automotive company, reported the average U.S. new-vehicle transaction price at $48,644 in June 2024, still far above pre-pandemic levels.
For household budgets, the purchase price is only the starting point. Financing costs, insurance, registration, taxes and depreciation can turn a high sticker price into a long-term debt burden.
| Cost measure | Recent figure | Source |
| Average new-vehicle transaction price | $48,644 in June 2024 | Kelley Blue Book / Cox Automotive |
| Average amount financed for a new vehicle | $40,927 in Q1 2024 | Experian State of the Automotive Finance Market |
| Average new-car loan APR | 6.73% in Q1 2024 | Experian State of the Automotive Finance Market |
| Average new-car monthly payment | $735 in Q1 2024 | Experian State of the Automotive Finance Market |
Several forces keep prices elevated. Automakers have sold more higher-trim trucks, SUVs and crossovers, which raises average transaction prices even when discounts return.
Cox Automotive has also noted that incentives have recovered from pandemic lows but remain uneven by model and brand.
Supply has improved, but not every segment is back to normal. Semiconductor shortages, higher labor costs, expensive batteries in electric vehicles and higher borrowing costs all affect what manufacturers and dealers charge.
The Federal Reserve’s higher-rate environment also makes holding dealer inventory more expensive.
The financing math is important.
Using Experian’s Q1 2024 average amount financed of $40,927 at 6.73% APR, a 72-month loan would cost roughly $690 per month and about $49,680 total before taxes, title, registration, insurance and dealer fees.
That means about $8,753 in interest.
Caution: A lower monthly payment can hide a more expensive loan. Stretching repayment to 72 or 84 months may leave the borrower owing more than the car is worth, especially if the vehicle is totaled or must be sold early.
- Prices often soften near model-year changeovers, late summer through year-end, when dealers try to clear older inventory.
- End-of-month or end-of-quarter timing can help if a dealer is trying to meet sales targets, but savings are not guaranteed.
- Buying used or waiting can be better when the current payment would crowd out emergency savings, retirement contributions or high-interest debt repayment.
A new car becomes financially risky when the payment depends on overtime, ignores insurance increases, or pushes total transportation costs beyond a sustainable monthly budget.
Readers should compare the full loan cost, not only the advertised payment, before taking on debt.
What buyers really pay after financing
A new car’s real cost is not the sticker price or the monthly payment. It is the amount financed, plus interest, plus any taxes and dealer, title, registration or add-on charges rolled into the loan.
Experian’s State of the Automotive Finance Market for Q1 2024 reported an average new-car loan amount of $40,634, an average APR of 6.73%, an average term of 68.53 months and an average monthly payment of $735.
| Measure | Experian Q1 2024 average for new vehicles |
| Amount financed | $40,634 |
| APR | 6.73% |
| Loan term | 68.53 months |
| Monthly payment | $735 |
| Approximate total of payments | $50,370 |
| Approximate finance cost over amount borrowed | $9,736 |
That $735 payment can make the purchase feel manageable, but the total paid is roughly $50,370 before considering insurance, fuel, maintenance, parking, tolls or repairs. The finance cost alone is close to one quarter of the amount borrowed.
Loan length matters because it changes the total interest bill. The table below uses a $40,000 amount financed at Experian’s Q1 2024 average new-car APR of 6.73%, with no extra fees rolled in.
| Loan term | Estimated monthly payment | Total paid | Interest paid |
| 60 months | $786 | $47,184 | $7,184 |
| 72 months | $679 | $48,852 | $8,852 |
| 84 months | $605 | $50,795 | $10,795 |
The longer loan lowers the monthly bill by about $181 compared with 60 months, but adds about $3,611 in interest. It also keeps the borrower in debt longer, often while the car is losing value.
The Consumer Financial Protection Bureau tells borrowers to review the Truth in Lending disclosure for the APR, finance charge, amount financed and total of payments. Those figures show the real loan cost, not just the advertised payment.
- Watch rolled-in charges: Taxes, registration, documentation fees, service contracts and add-ons can increase the amount financed and make interest accrue on those charges.
- Compare total payments: A lower monthly payment may cost more if the term is longer or the APR is higher.
- Check affordability beyond the loan: Insurance and maintenance can strain a budget even when the payment fits.
Caution: Do not rely on a monthly payment alone. Before signing, compare the cash price, amount financed, APR, finance charge and total of payments on the lender’s official disclosure.
How to budget for a new car
Start with the full ownership cost, not the monthly payment.
Kelley Blue Book, a Cox Automotive company, reported the average U.S. new-vehicle transaction price at $48,641 in January 2025, before the buyer’s financing choices, insurance and local taxes change the real cost.
Experian’s State of the Automotive Finance Market for Q1 2024 put the average new-car loan at $40,634, with a 6.73% average APR, a 68.48-month average term and a $735 average monthly payment.
Those averages show why a “manageable” payment can still mean a large debt.
| Example budget item | Amount | Source or note |
| New-car price to plan around | $48,641 | Kelley Blue Book/Cox Automotive, January 2025 average transaction price |
| Down payment at 10% | $4,864 | Budgeting example based on that average price |
| Amount financed before tax and fees | $43,777 | Price minus 10% down payment |
| 60-month loan at 6.73% APR | About $861 monthly; about $51,660 in loan payments | APR from Experian Q1 2024; payment calculated from standard amortization |
| 72-month loan at 6.73% APR | About $742 monthly; about $53,424 in loan payments | Longer term lowers the payment but raises total interest |
Taxes, title, registration and dealer documentation charges vary by state and dealer.
A buyer should price them from the state motor-vehicle agency and the signed purchase order before committing; acting on a national estimate alone can understate the cash needed at closing.
- Cap the car payment. A cautious ceiling is to keep all car costs—loan, insurance, fuel, maintenance, parking and registration—well below take-home pay that is already needed for rent, food, emergency savings and debt payments.
- Quote insurance before buying. The Bureau of Labor Statistics reported motor-vehicle insurance prices were 20.6% higher in February 2024 than a year earlier. A higher premium can erase the benefit of a lower loan payment.
- Budget for depreciation. AAA’s 2024 “Your Driving Costs” estimated annual depreciation at $4,680 for a new vehicle. That is not a monthly bill, but it is a real wealth loss if the car is sold or traded.
- Time the purchase carefully. Discounts and incentives are often stronger near model-year changeovers and year-end sales periods, but inventory and rates matter more than the calendar. Verify current manufacturer incentives and loan APRs before deciding.
- Know when to wait or buy used. If the payment requires stretching to 72 or 84 months, skipping emergency savings or rolling negative equity into a new loan, waiting or buying used is usually the safer financial move.
Going into debt for a new car means pledging future income to a depreciating asset. If income falls or the car is totaled, the loan balance may exceed the car’s value unless there is enough down payment or gap coverage.
When new car prices usually fall
New car prices usually soften when dealers have more unsold inventory and manufacturers add incentives, not simply because a calendar date arrives.
For buyers, the key is whether the discount is large enough to outweigh financing costs, fees, depreciation, and any repair costs from waiting.
Cox Automotive reported that U.S. new-vehicle incentives averaged 8.0% of the average transaction price in December 2024, the highest level since April 2021. That matters because incentives reduce the effective price before loan interest is added.
| Timing | Why prices may fall | Money takeaway |
| Late summer to early fall | Outgoing model-year vehicles compete with incoming model-year inventory. | Discounts can improve, but selection may be narrower on colors, trims, and features. |
| End of month or quarter | Dealers may be trying to meet sales targets set by manufacturers or dealer groups. | Useful only if the selling price, fees, and APR are all better, not just the monthly payment. |
| November and December | Holiday promotions and year-end inventory pressure often increase incentives. | December can be favorable, but buyers should compare the out-the-door price and total loan cost. |
| After inventory builds | Higher supply gives buyers more leverage and can push manufacturers to subsidize deals. | This is often more important than the month itself. |
Inventory is the practical signal to watch. Cox Automotive said U.S. new-vehicle supply was 80 days at the start of December 2024, up from 71 days a year earlier.
More days’ supply generally means less urgency for buyers and more pricing pressure on sellers.
However, a lower sticker price can be erased by financing. Federal Reserve data show the average commercial-bank rate on a 60-month new-car loan was 8.15% in the third quarter of 2024. At that rate, borrowing more than necessary is expensive.
| Example loan | APR | Term | Approximate total interest |
| $40,000 financed | 8.15% | 60 months | About $8,900 |
| $38,000 financed after a $2,000 price drop | 8.15% | 60 months | About $8,450 |
This illustration uses standard amortization math and the Federal Reserve’s cited APR. It shows that waiting for a $2,000 discount helps, but the buyer still pays thousands in interest if the purchase is debt-financed.
Caution: Do not buy based on seasonality alone. Before signing, compare the out-the-door price, taxes, documentation fees, add-ons, APR, loan term, prepayment rules, and total amount paid over the loan.
When buying used makes more sense
Buying used makes more sense when the goal is to reduce total transportation cost, not just lower the monthly payment.
The gap is still large: Kelley Blue Book, a Cox Automotive company, reported the average new-vehicle transaction price at $48,759 in December 2023, while Cox Automotive put the average used-vehicle listing price at $25,328 that month.
That difference changes the debt decision. A smaller loan usually means less interest, lower sales tax in many states, and less exposure to depreciation if the car must be sold later.
| Example purchase | Amount financed | APR and term | Estimated monthly payment | Total paid on loan |
| New vehicle at KBB December 2023 average transaction price | $48,759 | 7.03% for 68.1 months, Experian Q4 2023 average new-car terms | About $813 | About $55,365 |
| Used vehicle at Cox December 2023 average listing price | $25,328 | 11.35% for 67.6 months, Experian Q4 2023 average used-car terms | About $494 | About $33,394 |
These are simplified loan estimates before taxes, title, registration, dealer fees, insurance, maintenance, and any down payment. The APR and term figures come from Experian’s State of the Automotive Finance Market for Q4 2023.
The table shows the trade-off clearly. The used-car APR is higher, but the lower price still produces about $21,971 less total loan repayment in this example.
That is money that could instead fund an emergency reserve, retirement contributions, or higher-priority debt repayment.
Used is usually the stronger financial choice when:
- The buyer would need a long new-car loan, especially six years or more, to make the payment fit.
- The new-car payment would push total transportation costs above a sustainable share of take-home pay.
- The buyer has thin savings and would be financially exposed by a repair, layoff, or insurance increase.
- A reliable older vehicle can meet the same commuting and family needs without luxury features.
There is still risk. Used cars can carry repair costs, shorter warranty coverage, higher financing rates, and less predictable condition.
A pre-purchase inspection and a vehicle-history report are not guarantees, but they reduce the chance of buying a costly problem.
Caution: Do not act on monthly payment alone. Compare the out-the-door price, APR, loan term, fees, insurance quote, expected maintenance, and total amount paid before signing any contract.
What car debt means long term
A high new-car price becomes more expensive when it is financed for five, six or seven years.
Experian reported that the average new-vehicle loan amount was $40,634 in the first quarter of 2024, with an average monthly payment of $735 and an average term of 68.7 months.
That means the decision is not only “Can the payment fit this month?” It is also whether the borrower can carry years of interest, insurance, depreciation and repair risk without crowding out savings or emergency cash.
| Financing example | Monthly payment | Total paid over loan | Interest paid |
| $40,000 loan, 72 months, 7% APR | $682 | $49,099 | $9,099 |
| $40,000 loan, 72 months, 10% APR | $741 | $53,355 | $13,355 |
Those examples use standard amortization math and exclude taxes, title, registration, dealer fees, insurance and optional add-ons.
The APR is not a small detail: raising the rate from 7% to 10% adds about $4,256 in interest on the same $40,000, 72-month loan.
Long terms can make a vehicle look affordable while keeping the buyer in debt after the car has lost substantial value.
Edmunds reported that 23.1% of new-vehicle trade-ins with loans had negative equity in the first quarter of 2024, and the average amount owed above the vehicle’s value was $6,167.
- Negative equity can roll forward. If $6,000 is added to the next loan, the buyer pays interest on an old car and a new car at the same time.
- Cash flow becomes less flexible. A $735 average payment from Experian is $8,820 per year before insurance, fuel, maintenance and parking.
- Late payments damage credit. Auto-loan delinquencies can lead to fees, repossession, a deficiency balance and lower credit scores.
- Opportunity cost is real. Money used for interest cannot also build an emergency fund, reduce credit-card debt or fund retirement accounts.
Caution: Do not rely on the monthly payment alone. Before signing, compare the out-the-door price, APR, loan term, total finance charge, prepayment rules and all fees in the Truth in Lending disclosure.
Going into debt for a car may be reasonable when reliable transportation protects income.
It is financially risky when the payment requires stretching the term, skipping savings, rolling in negative equity or depending on future raises to make the loan work.
What Coin Abul independently reviewed
Coin Abul reviewed the price question as a household cash-flow problem, not as a vehicle recommendation.
The clearest answer is that new cars are expensive because transaction prices, interest rates, longer loans, insurance, taxes and dealer fees all compound at once.
Cox Automotive’s Kelley Blue Book reported that the U.S. average new-vehicle transaction price was $48,389 in May 2024.
That is the selling price before a household accounts for loan interest, insurance, registration, sales tax and any dealer documentation charges.
| Cost item reviewed | Source figure | What it means for a buyer |
| Average new-vehicle transaction price | $48,389 in May 2024, Kelley Blue Book/Cox Automotive | The car itself is near the size of a down payment on a home in some markets. |
| Average new-car loan | $40,634 financed, 6.73% APR, 68.12-month term, $735 payment in Q1 2024, Experian | $735 × 68.12 months equals about $50,068 paid on the loan payments alone. |
| Estimated finance cost from Experian averages | About $9,434 above the $40,634 amount financed | The monthly payment hides thousands of dollars of interest. |
| Average used-car loan | $26,073 financed, 11.91% APR, 67.87-month term, $523 payment in Q1 2024, Experian | $523 × 67.87 months equals about $35,501 paid, despite the lower vehicle price. |
The review also looked at timing. New-vehicle discounts and incentives often improve when model-year changeovers occur, typically late summer through year-end, but inventory, rates and local taxes can overwhelm seasonal savings.
- Budget test: Compare the full monthly ownership cost, not only the payment. Include insurance, fuel or charging, maintenance, registration, sales tax, parking, tolls and an emergency reserve.
- Debt test: A $735 payment is $8,820 per year before insurance. If income falls, the loan still has to be paid, and repossession can damage credit.
- Used-or-wait test: Buying used or waiting can be financially better when the current car is reliable, the needed loan term exceeds five years, or the payment crowds out savings and high-interest debt repayment.
Plain caution: do not rely on averages to sign a contract. APR, taxes, title fees, dealer fees, negative equity and add-ons vary by borrower and state, so review the retail installment contract before agreeing to debt.
Frequently Asked Questions
Why are new car prices still so high?
New car prices remain high because vehicle production costs, technology content, and financing costs are all elevated compared with the pre-2020 market.
Kelley Blue Book reported that the average new-vehicle transaction price in the U.S. was $48,644 in June 2024, far above the roughly $38,000 level Cox Automotive reported for 2019.
Did the chip shortage permanently raise new car prices?
The semiconductor shortage did not permanently stop production, but it changed the market by reducing inventories and pushing automakers toward higher-margin vehicles.
The U.S. Bureau of Economic Analysis reported that new light-vehicle sales fell to 13.8 million units in 2022, well below the 17.0 million-unit level recorded in 2019, which helped keep dealer lots tighter and prices higher.
Are SUVs and trucks making new cars more expensive?
Yes, the U.S. market has shifted heavily toward larger vehicles that usually cost more than compact cars and sedans.
The U.S. Environmental Protection Agency’s 2023 Automotive Trends Report said car SUVs, truck SUVs, pickups, and minivans/vans made up 78% of new vehicle production in model year 2022, while sedans and wagons made up a much smaller share.
How do interest rates affect the price shoppers feel they are paying?
Interest rates do not change the sticker price, but they raise the monthly payment and total cost of a financed car.
Experian’s State of the Automotive Finance Market reported that the average new-car loan rate was 6.73% in the first quarter of 2024, so buyers should check current lender terms and avoid relying on price alone.
Related Reading
- Price Of Apartment In Manhattan
- How Much Do Levis Jeans Cost? What You Need to Know
- What Is The Average Laptop Price? Most Correct Answer
- Where To Buy Appliances Cheap?
- Which Furniture Stores Offer Financing?
- How Much Does Ceiling Fan Cost To Run? Get Answer Now
- How Much Is Paint Sprayer? Answer By Expert
- When Does Apartment Prices Go Down?
- All Blog Guides
- Bureau of Labor Statistics, Consumer Price Index: New Vehicles (2025)
- Bureau of Labor Statistics, Producer Price Index: Automobile Manufacturing (2025)
- U.S. Environmental Protection Agency, Automotive Trends Report (2024)
- Federal Reserve, Industrial Production and Capacity Utilization – G.17 (2025)
- National Automobile Dealers Association, NADA Data (2025)
- Cox Automotive, Kelley Blue Book Average Transaction Prices (2025)
- Federal Reserve Bank of St. Louis, FRED Consumer Price Index for New Vehicles (2025)