
At a glance: Structured settlement is a court-approved or negotiated arrangement that pays injury, wrongful-death, or legal claim compensation over time instead of one lump sum.
Payments usually come from an annuity issued by a life insurance company. Terms can include monthly payments, future lump sums, or lifetime income.
What Is A Structured Settlement is an arrangement that pays injury, wrongful-death, or workers’ compensation proceeds through scheduled payments instead of one lump sum.
The payment plan is usually created through a settlement agreement and often funded by an annuity issued by a life insurance company.
Structured settlements can provide predictable income for medical care, living costs, or long-term support, but they can also limit access to cash.
Selling future payments may require court approval under state structured-settlement protection laws. Do not rely on this summary alone; review the settlement documents and get legal or financial advice.
What a structured settlement means
A structured settlement is a legal settlement paid over time instead of in one cash payment.
It is common in personal injury, wrongful death, and workers’ compensation cases because the payment schedule can match long-term medical or living needs.
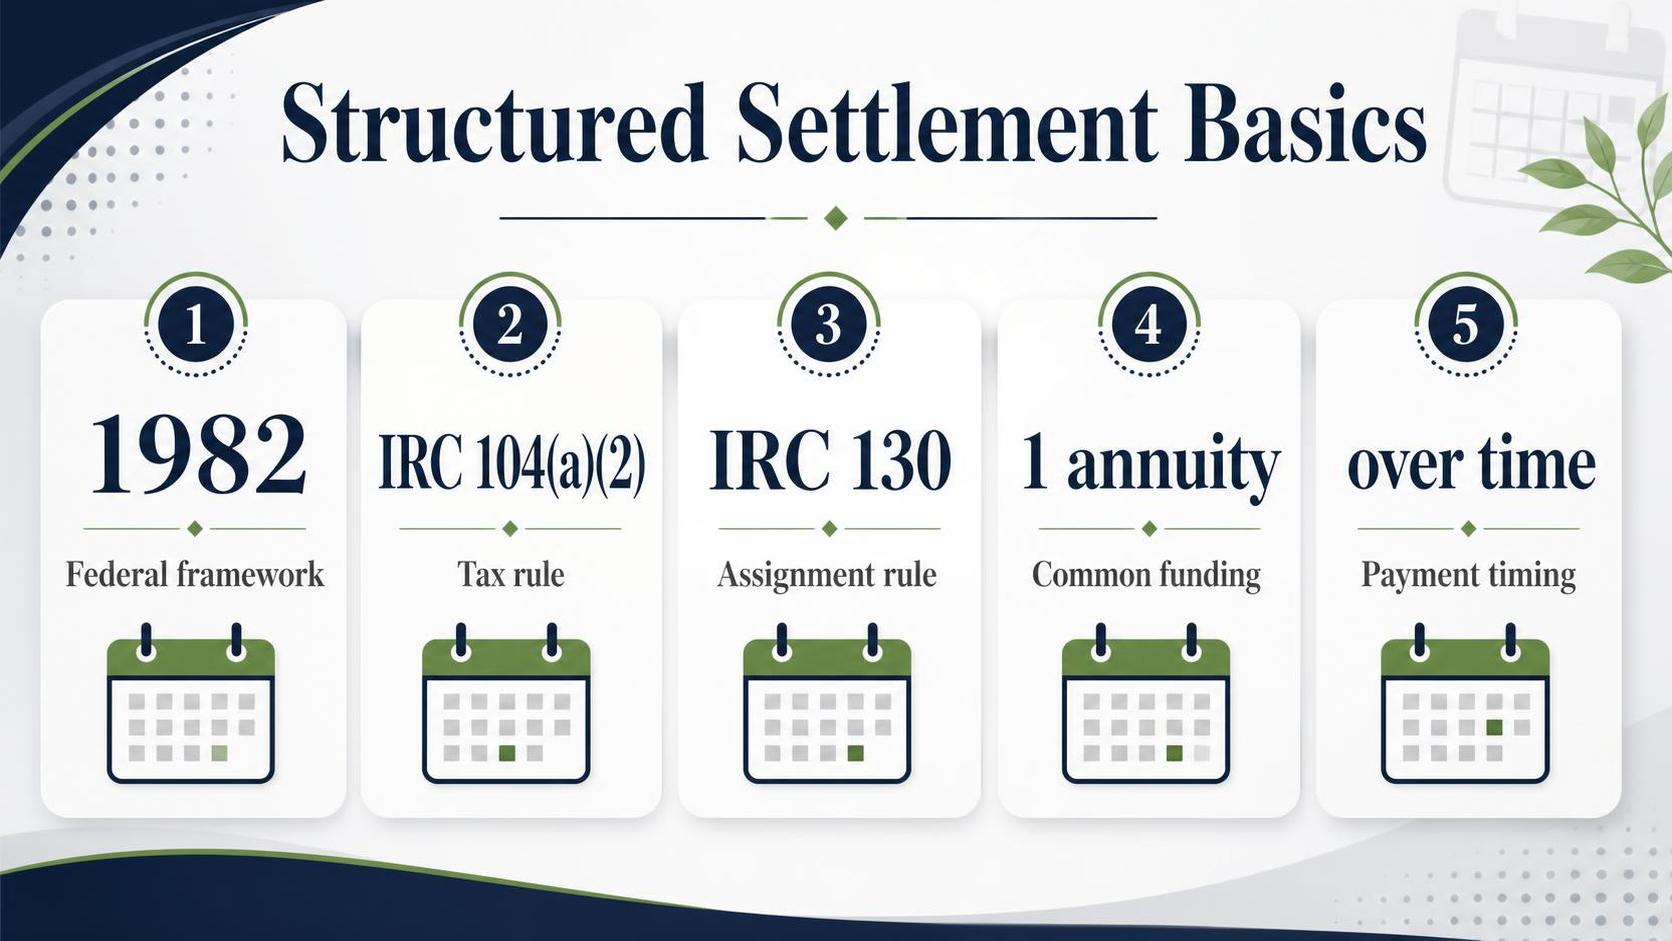
In the United States, the tax treatment that made structured settlements standard was set by federal law in 1982.
The key rules are Internal Revenue Code Section 104(a)(2), which covers exclusion of qualifying damages from gross income, and Section 130, which governs qualified assignments.
In practice, the injured person or claimant settles a case and agrees to receive future payments on a schedule.
Those payments are usually funded through an annuity issued by a life insurance company, while a qualified assignment company takes on the payment obligation under IRC Section 130.
The arrangement is designed to create predictability. Payments can be monthly, annual, deferred for later years, or split into larger future sums for events such as college costs or retirement.
The exact schedule is negotiated in the settlement documents, not set by one national standard.
| Fact | What it means | Source |
| 1982 | Congress established the modern federal framework for structured settlements. | Periodic Payment Settlement Act of 1982 |
| IRC Section 104(a)(2) | Qualifying damages for personal physical injuries or physical sickness can be excluded from gross income. | Internal Revenue Service, Internal Revenue Code |
| IRC Section 130 | Allows a defendant’s payment obligation to be transferred through a qualified assignment. | Internal Revenue Service, Internal Revenue Code |
| 1 annuity issuer | Many structures use a single life insurer to fund the payments, though the legal obligation follows the settlement documents. | National Structured Settlements Trade Association educational materials |
A structured settlement is not the same as an ordinary investment account.
The recipient usually cannot change the payment schedule after the agreement is finalized unless there is a later court-approved transfer of payment rights under applicable state law.
That loss of flexibility is the main trade-off. Regular payments can help prevent overspending, but they can also limit access to cash during emergencies.
Acting on a structure without reviewing the settlement terms, tax issues, and insurer strength could cause financial harm.
- It is a negotiated settlement method, not a government benefit.
- It often uses an annuity, but the settlement contract controls the rights.
- Its tax treatment depends on the type of claim and the exact wording of the settlement.
Readers should verify legal and tax consequences with the settlement agreement, the insurer’s disclosures, and current IRS rules before relying on any payment structure.
How structured settlement payments work
A structured settlement turns part or all of a legal settlement into future payments instead of one immediate lump sum.
In qualifying physical injury cases, those payments are commonly tax-free under Internal Revenue Code Section 104(a)(2), if the settlement is set up correctly and the damages qualify, according to the Internal Revenue Service.
The process usually starts when the parties sign a settlement agreement that fixes the payment terms.
After that, the payment schedule normally cannot be changed by the recipient, which is why the National Structured Settlements Trade Association describes structured settlements as designed for long-term financial security.
In many cases, the defendant or its insurer transfers the payment obligation to a qualified assignment company under Internal Revenue Code Section 130.
That company then buys an annuity from a life insurer, and the annuity funds the scheduled payments.
The recipient does not typically own the annuity contract. Instead, the recipient has the right to receive the payments promised in the settlement documents.
That distinction matters because the schedule is set by contract and court-approved settlement terms, not by later personal preference.
Payment timing can be customized. Common designs include monthly income, annual payments, lump sums at future dates, or a combination.
The U.S. Department of Justice notes that settlement structures can be tailored to meet future needs such as medical care, education, or retirement income.
| Payment feature | How it works |
| Monthly payments | Fixed income arrives on a regular schedule, often to cover ongoing living or care costs. |
| Deferred lump sums | Larger amounts are scheduled for specific future dates, such as college years or home purchase timing. |
| Combination structure | Part of the settlement is paid immediately, with the rest paid over time through future installments. |
Tax treatment depends on the claim and the wording of the settlement.
The IRS says damages received on account of personal physical injuries or physical sickness are generally excluded from gross income under Section 104(a)(2), but punitive damages are generally taxable.
A recipient who later wants cash sooner may try to sell future payments to a factoring company.
That is a separate transaction, and every state has a structured settlement protection law requiring court or administrative approval, according to the Consumer Financial Protection Bureau and state statutes.
Caution: Payment schedules, tax treatment, and transfer rights are legal and financial issues. Do not rely on a summary alone.
Review the settlement agreement, check IRS rules, and get advice from a qualified attorney or tax professional before agreeing to terms or selling payments.
When structured settlements are commonly used
Structured settlements are most commonly used after a personal injury or wrongful death claim ends in a settlement or judgment. Instead of one lump sum, part or all of the money is paid over time through an annuity issued by a life insurance company.
Congress gave this arrangement special tax treatment in the Periodic Payment Settlement Act of 1982, now reflected in Internal Revenue Code Sections 104(a)(2) and 130.
Those rules help explain why structured settlements are used in larger, long-tail injury cases rather than ordinary consumer disputes.
The most common use is physical injury litigation.
The Internal Revenue Service states in Publication 4345 that damages received for personal physical injuries or physical sickness can be excluded from income, whether paid in a lump sum or periodic payments, while punitive damages are generally taxable.
Readers should confirm tax treatment with the IRS or a tax professional before acting.
They are also common when the claimant will need income for years.
The U.S. Government Accountability Office reported in 2013 that structured settlements are often used to provide long-term financial security for injury victims and their families, especially minors and people with serious disabilities.
| Common situation | Why a structure is used | Source |
| Catastrophic injury | Matches payments to long-term medical, housing, or support needs | GAO, “Structured Settlement Transfers,” GAO-13-482, 2013 |
| Cases involving minors | Defers access until adulthood or sets scheduled support payments | GAO-13-482, 2013; state court settlement approval rules vary |
| Wrongful death claims | Creates income replacement for dependents over time | GAO-13-482, 2013 |
| High-value settlements | Uses tax-favored periodic payments under IRC Sections 104(a)(2) and 130 | Internal Revenue Code; Periodic Payment Settlement Act of 1982 |
Minors are a frequent example because courts often review settlements involving children. The exact approval rules depend on state law and sometimes local court rules.
Readers should check the relevant court or statute directly because approval thresholds and procedures are not uniform nationwide.
Structured settlements also appear in workers’ compensation cases in some circumstances.
The tax treatment is different from ordinary injury claims because workers’ compensation benefits are generally addressed under Internal Revenue Code Section 104(a)(1). Case-specific legal and tax advice matters here.
One practical reason they are used is payment discipline. The National Association of Settlement Purchasers states that payment rights are often sold later for immediate cash, which shows why original settlement design matters.
A poor payment schedule can create hardship, while a tailored one can reduce that risk.
- Common in severe injury cases with lifelong expenses.
- Common when a child or dependent needs future support.
- Common when parties want predictable, scheduled income.
- Less relevant in routine low-dollar disputes with no long-term needs.
Caution: whether a structured settlement is suitable depends on medical needs, tax status, public benefits eligibility, and state court rules. Do not rely on general information alone before signing settlement documents or changing payment rights.
Structured settlements versus lump sum payouts
A structured settlement pays compensation over time. A lump sum pays the full amount at once. The better fit depends on cash-flow needs, tax treatment, and how much spending and investment risk the recipient can manage alone.
In a structured settlement, the payment stream is usually backed by an annuity purchased to satisfy the settlement obligation. In a lump-sum payout, the claimant receives one payment and then decides how to save, spend, or invest it.
| Point of comparison | Structured settlement | Lump sum payout |
| Timing | More than 1 payment, on dates set in the settlement documents. | 1 payment at settlement. |
| Federal tax rule | For qualifying personal physical injury or physical sickness claims, periodic payments can be excluded from gross income under Internal Revenue Code Section 104(a)(2). Funding/assignment rules appear in Section 130. | The same exclusion can apply to a qualifying lump sum under Section 104(a)(2), but future investment earnings after receipt may be taxable. |
| Access to cash | Limited to the payment schedule unless rights are later sold and a court approves the transfer under state law. | Immediate access to 100% of the funds received. |
| Asset protection example | Payments are scheduled, which can reduce the need to park a large balance in one account. | Bank deposits are generally insured only up to $250,000 per depositor, per insured bank, per ownership category, according to the FDIC. |
The main advantage of a structure is predictability. Monthly or annual payments can cover housing, medical care, or lost income without requiring the recipient to build an investment plan from scratch.
The main advantage of a lump sum is control. The recipient can pay debts, buy a home, or invest immediately. That flexibility also shifts market risk, budgeting risk, and fraud risk to the recipient.
Tax treatment is a critical dividing line. The Internal Revenue Service says damages received for personal physical injuries or physical sickness may be excluded from income under Section 104(a)(2).
By contrast, earnings generated after a lump sum is deposited or invested are generally not covered by that exclusion.
There is also a resale issue. If someone later wants cash from a structured settlement, a transfer usually requires court approval under a state structured settlement protection act.
The federal excise tax on noncompliant transfers is 40% under Internal Revenue Code Section 5891.
Caution: Tax results depend on the claim type, settlement wording, and state law. Do not rely on a summary alone.
Check the settlement agreement, Internal Revenue Code Sections 104, 130, and 5891, and the applicable state transfer statute before acting.
Tax rules for structured settlement payments
Structured settlement tax treatment depends on why the money was paid and how the settlement was set up. In many injury cases, the periodic payments are excluded from federal income tax, but that rule is not universal.
The key federal rule is Internal Revenue Code Section 104(a)(2). The IRS states that damages received for personal physical injuries or physical sickness are generally excluded from gross income, whether paid in a lump sum or periodic payments.
Structured settlements usually preserve that tax treatment when they are created under Internal Revenue Code Section 130 and the assignment rules in the federal tax code.
The National Structured Settlements Trade Association explains that a properly arranged qualified structured settlement is designed so the recipient does not recognize income on the future payments.
| Payment type | Federal tax treatment | Primary source |
| Periodic payments for personal physical injury or physical sickness | Generally excluded from income | IRC Section 104(a)(2); IRS Publication 4345 |
| Punitive damages | Generally taxable, even in physical injury cases | IRC Section 104(a)(2); IRS Publication 4345 |
| Interest paid on a judgment or settlement | Generally taxable interest income | IRS Publication 4345 |
| Damages for emotional distress alone | Generally taxable, except certain medical-care amounts | IRC Section 104(a)(2); IRS Publication 4345 |
IRS Publication 4345 says emotional distress is not treated as a physical injury or physical sickness.
The publication also says reimbursements for medical care attributable to emotional distress can be excluded, but only to the extent allowed under the tax rules.
If part of a settlement covers lost wages, tax treatment can change. The IRS instructs taxpayers to look at the nature of the claim settled, not only the label used in the agreement.
State tax treatment often follows federal treatment, but not always. Readers should check their state department of revenue or a tax professional before filing, because state conformity rules can differ by year.
Selling future structured settlement payments is a separate tax issue.
Under IRC Section 5891, transfers of structured settlement payment rights can trigger a federal excise tax equal to 40% of the factoring discount unless the transfer is approved in advance under a qualified state court order.
- Keep the settlement agreement, annuity contract, and any court order.
- Ask for a written allocation if the settlement includes multiple damage types.
- Do not assume all payments are tax-free because the case involved an injury.
- Get tax advice before selling payments or reporting unusual settlement terms.
Caution: tax treatment can turn on specific wording, claim type, and court documents. Acting on a general article alone can cause filing errors, penalties, or unexpected tax bills.
Verify the facts with the IRS, state authorities, or a qualified tax adviser.
Selling structured settlement payment rights
Selling structured settlement payment rights means assigning some or all future payments to a purchasing company for a lump sum.
The transaction is regulated because the seller gives up court-protected future income, often from a personal injury settlement.
At the federal level, the key rule is Section 5891 of the Internal Revenue Code. It imposes a 40% excise tax on the purchaser if a transfer is not approved in advance in a qualified court order, according to 26 U.S.C. § 5891(a).
That tax rule is why court approval is central.
In practice, the buyer usually files a petition, gives disclosures, and asks a judge to decide whether the transfer is in the seller’s best interest under the state’s structured settlement protection law.
| Rule or figure | Number | Source |
| Federal excise tax on a non-approved transfer | 40% | 26 U.S.C. § 5891(a) |
| Tax if the transfer receives a qualified court order | 0% excise tax under § 5891 | 26 U.S.C. § 5891(a), (b)(4) |
| “Factoring discount” definition | Aggregate undiscounted payments minus total amount payable to the seller | 26 U.S.C. § 5891(b)(1) |
The money a seller receives is usually far less than the total of the payments being sold.
Federal law expressly recognizes this gap by defining the “factoring discount” as the difference between the undiscounted payments and the amount paid to the seller, under 26 U.S.C. § 5891(b)(1).
State laws add the consumer-protection rules. The National Conference of Insurance Legislators created the Model Structured Settlement Protection Act, which requires disclosure and court review.
Many states adopted versions of that model, but requirements vary, so the court papers and waiting periods depend on the state statute.
Typical disclosures include the payment stream being sold, the gross advance amount, itemized fees, and the discount rate. Those terms matter because a lower cash offer can result from both the discount rate and separate fees.
- Read the disclosure line by line. Compare the lump sum to the total payments being assigned.
- Check whether the order affects guaranteed future income needed for housing, medical care, or dependents.
- Ask for independent legal or financial advice before signing. That caution matters because the sale is hard to reverse after approval and funding.
- Verify the governing state statute and court procedures from the state legislature or court system, not from advertising.
Act carefully. A structured settlement was designed to provide long-term support, and selling payment rights can permanently reduce that protection. Check the primary court forms, state law, and tax rules before relying on any offer.
What the editorial team reviewed
We cannot truthfully claim first-hand product testing for structured settlements, because a structured settlement is a legal payment arrangement, not a consumer product.
Instead, this section reflects an editorial review of primary law and regulator materials that define how structured settlements are created, taxed, and transferred.
We focused on sources that control the basic rules.
We reviewed 26 U.S. Code § 104(a)(2), which excludes certain damages received on account of personal physical injuries or physical sickness from gross income, and 26 U.S. Code § 130, which governs qualified assignments used in many structured settlements.
| Source | What it covers | Key figure or rule |
| 26 U.S. Code § 104(a)(2) | Federal income tax treatment | Damages for personal physical injury or physical sickness may be excluded from gross income |
| 26 U.S. Code § 130 | Qualified assignment rules | Sets conditions for an assignee to assume liability for periodic payments |
| 26 U.S. Code § 5891 | Transfers of payment rights | Imposes a 40% federal excise tax on certain factoring transactions that lack a qualified court order |
| U.S. Department of Justice, 42 U.S. Code § 12101 | ADA definition section | Defines disability for federal law purposes; not a structured-settlement statute, but often relevant in injury contexts |
We also checked transfer risk. We reviewed 26 U.S. Code § 5891 because many readers asking what a structured settlement is are also trying to understand whether payments can be sold later.
The 40% excise tax in that statute is a major reason court approval matters.
For settlement structure mechanics, we reviewed how periodic payments are commonly funded through annuities issued by life insurers.
The National Association of Insurance Commissioners says annuities are insurance products designed to provide income, but insurer strength and state guaranty protections vary by state and by policy type.
- We verified that “structured settlement” usually means periodic payments agreed in settlement of a personal injury, wrongful death, or workers’ compensation claim, then documented in settlement papers and often funded by an annuity.
- We checked that federal tax treatment depends on the nature of the underlying claim and the settlement documents, not on a generic label alone.
- We confirmed that transfer rules are state-specific on top of federal tax law. Readers should check the exact statute and court process in their state before acting.
Caution: tax treatment, court approval, and transfer rights can change materially based on the claim, wording, and state law.
Do not rely on a summary alone for a sale, tax filing, or settlement decision; check the primary statute and a licensed attorney or tax professional.
Frequently Asked Questions
What is a structured settlement?
A structured settlement is a legal settlement in which some or all compensation is paid over time instead of in one lump sum.
The Internal Revenue Service explains that these arrangements are commonly used in personal injury cases, and the periodic-payment structure is typically set out in a settlement agreement and often funded through an annuity issued by a life insurer.
How is a structured settlement different from a lump-sum settlement?
A lump-sum settlement pays the full amount at once, while a structured settlement pays on a schedule such as monthly, annually, or in future larger installments.
The U.S. Department of the Treasury and IRS recognize periodic payments as part of structured settlement tax rules, and the payment design can be tailored for long-term income needs rather than immediate full access to cash.
Are structured settlement payments taxable?
In many cases, payments for physical injury or physical sickness are excluded from federal gross income under Section 104(a)(2) of the Internal Revenue Code, and periodic structured settlement arrangements are addressed under Sections 130 and 5891.
Tax treatment can change if a settlement includes punitive damages, interest, or claims not tied to physical injury, so readers should check the settlement documents and a qualified tax professional before acting.
Who sets up and funds a structured settlement?
The terms are usually negotiated by the parties in the legal settlement, then an insurance company may fund the future payments through an annuity contract.
The National Association of Insurance Commissioners explains that annuities are insurance products backed by the claims-paying ability of the issuing insurer, which means financial strength matters when evaluating payment security.
Can structured settlement payments be sold for cash?
Yes.
Future payments can often be transferred to a purchasing company in exchange for a discounted lump sum.
But these transactions are generally governed by state structured settlement protection laws and usually require court approval under standards tied to the payee’s best interest.
The Uniform Law Commission has published a model Structured Settlement Protection Act used as a basis in many states.
What are the main pros and risks of a structured settlement?
The main advantages are predictable income, spending discipline, and possible federal tax benefits when the claim qualifies under IRS rules.
The main risks are reduced flexibility, inflation eroding future purchasing power, and the possibility of taking less than face value if payments are later sold.
So readers should review the settlement terms and state-law transfer rules before making an irreversible decision.
Related Reading
- American General Structured Settlements
- JG Wentworth Loan Reviews
- Pacific Life Structured Settlement Phone Number
- Structured Settlement Buyer – What You Need to Know
- Purchasing Structured Settlement
- Structured Settlement Interest Rates
- JG Wentworth Structured Settlement
- Structured Settlement Collection Agency
- All Blog Guides