
Key takeaway: Purchasing Structured Settlement means a funding company buys some or all future structured settlement payments in exchange for a discounted lump sum.
The sale usually requires court approval under state structured settlement protection laws. Compare quotes, fees, discount rates, and legal terms before agreeing. Seek independent legal or financial advice.
Purchasing Structured Settlement is the court-approved sale of future settlement payments for a discounted lump sum. The buyer pays less than the payment stream’s face value because it assumes timing, legal, and collection risk.
Federal tax rules under IRC Section 5891 impose a 40% excise tax unless a qualified court order approves the transfer. State structured settlement protection acts also require disclosures and a judge’s best-interest review.
Readers should compare discount rates, fees, and alternatives before signing. Selling payments can permanently reduce long-term income, and acting on general information alone can cause financial harm.
Check the court order, state statute, and independent legal or financial advice.
How purchasing structured settlement payments works
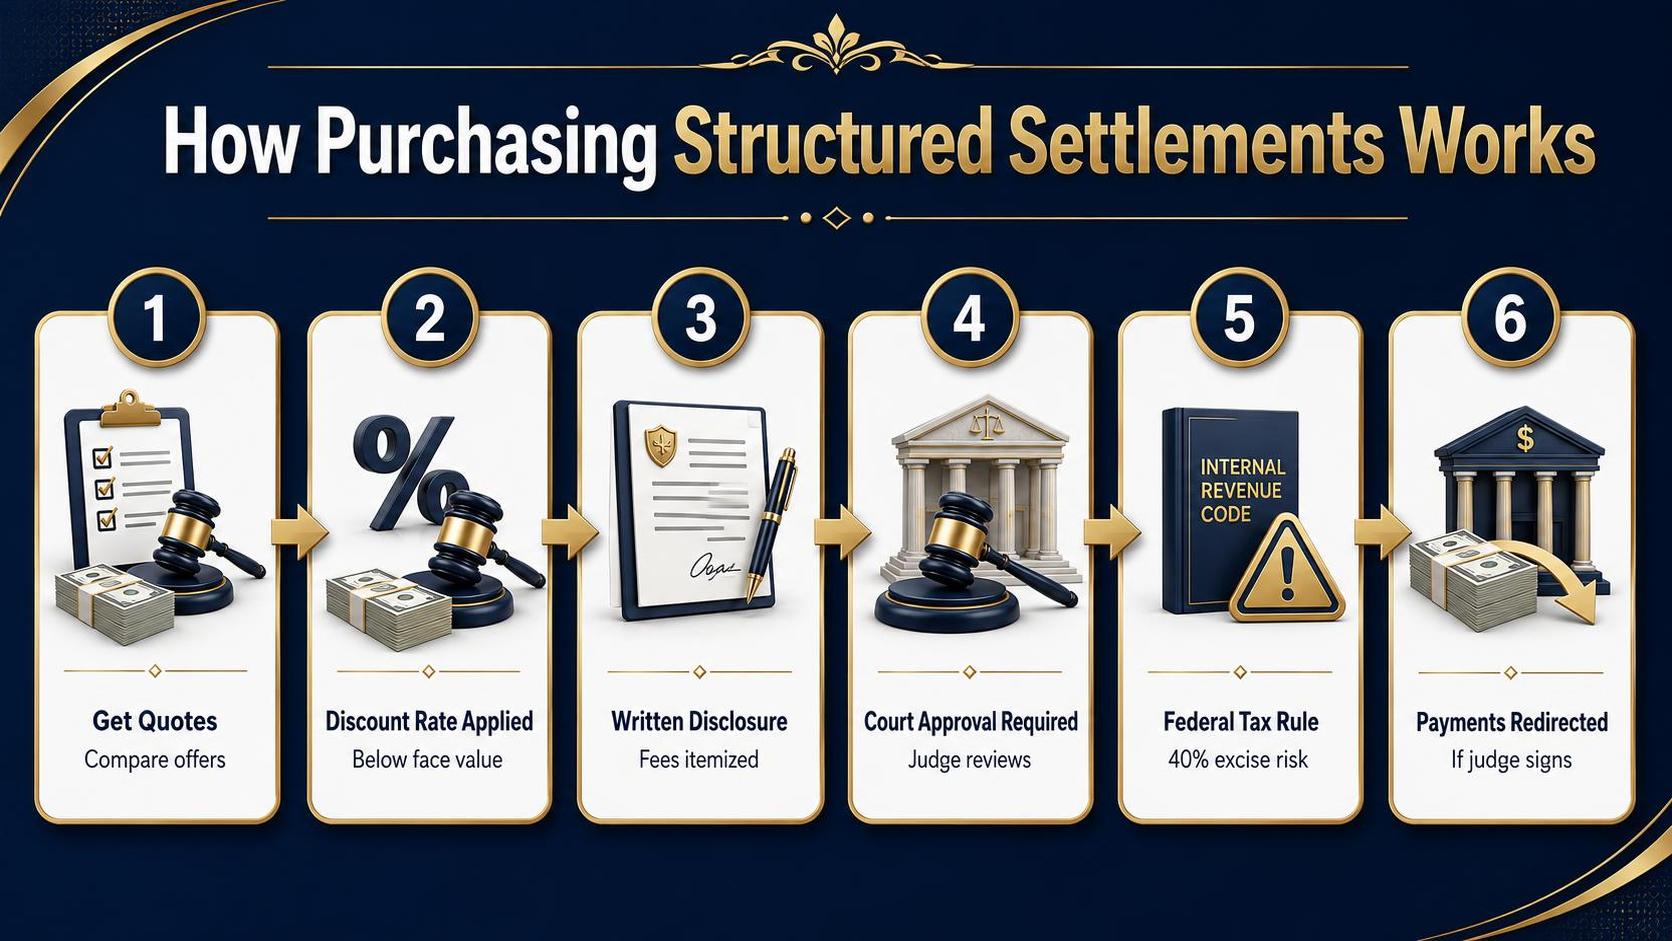
Purchasing structured settlement payments means a buyer pays cash now in exchange for some or all future payments from an existing settlement annuity.
The transaction is regulated because these payments often come from personal-injury settlements that receive special tax treatment under federal law.
The core rule is simple: a company does not buy the annuity itself.
It buys the payee’s right to receive specified future payments, then asks a court to approve the transfer under state structured settlement protection laws and federal tax rules.
The process usually starts with the payee requesting a quote for either a full transfer or a partial transfer. A partial transfer might assign only certain monthly payments or a set number of years, leaving the rest of the settlement unchanged.
The cash offer is lower than the total face value of the payments because the buyer applies a discount rate and deducts transaction costs.
Those charges vary by deal, so readers should review the written disclosure and compare multiple offers before signing.
| Rule or figure | What it means in practice | Primary source |
| 40% federal excise tax | If a transfer does not meet the definition of a “qualified order,” the purchaser can face a tax equal to 40% of the factoring discount. | 26 U.S. Code § 5891, Cornell Legal Information Institute |
| Tax exclusion for qualifying injury payments | Damages received on account of personal physical injuries or physical sickness are generally excluded from gross income. | 26 U.S. Code § 104(a)(2), Cornell Legal Information Institute |
| Qualified funding assignment rules | Structured settlement payment obligations are commonly funded through a qualified assignment to an annuity issuer. | 26 U.S. Code § 130, Cornell Legal Information Institute |
Before approval, the buyer must give a disclosure statement showing the amounts being sold, the payment schedule, the gross advance amount, itemized fees, and the net amount payable.
State law controls the exact form, and the court reviews whether the transfer is in the seller’s best interest.
If the judge signs the order, the annuity issuer and obligation owner are directed to send the assigned payments to the buyer. If the judge denies the transfer, the payments stay with the original payee and the sale does not close.
Caution: Selling structured settlement payments can permanently reduce long-term income. Do not rely on a quote alone.
Read the disclosure, confirm the court process in the applicable state statute, and consider advice from an attorney or tax professional before acting.
Who can legally sell payment rights
Only the person or entity that legally owns the structured settlement payment rights can sell them.
In most cases, that is the original payee named in the settlement or annuity documents, but the transfer is not effective unless a court approves it under state law.
Federal tax law strongly discourages private transfers without judicial review.
Under 26 U.S.C. § 5891, any structured settlement factoring transaction that lacks a “qualified order” can trigger a 40% federal excise tax on the factoring company, which is why court approval is central.
The usual seller is an adult payee who receives periodic payments from a personal injury, wrongful death, or workers’ compensation settlement. The right being sold is not the annuity itself in most transactions.
It is the right to receive specific future payments.
In nearly every state, the transfer must satisfy that state’s Structured Settlement Protection Act, often called an SSPA.
The National Conference of State Legislatures says 49 states have enacted transfer statutes, and the remaining state, Wisconsin, regulates transfers through a separate notice-and-approval process.
| Rule | Specific fact | Source |
| Federal tax consequence | 40% excise tax applies if there is no qualified order under 26 U.S.C. § 5891 | Internal Revenue Code, 26 U.S.C. § 5891 |
| State coverage | 49 states enacted structured settlement transfer statutes | National Conference of State Legislatures, Structured Settlements Transfer Statutes |
| Outlier state | Wisconsin uses a different notice-and-approval framework instead of a standard transfer statute | National Conference of State Legislatures, Structured Settlements Transfer Statutes |
Some people cannot sell on their own, even if they are the beneficiary of the payments.
A minor, an incapacitated adult, or a person subject to guardianship usually needs a court-appointed representative and additional court findings before any transfer can proceed.
Estates, trusts, or assignees may also hold payment rights in limited situations. Whether they can sell depends on the settlement documents, the annuity contract, any anti-assignment language, and state law.
Courts often examine those documents closely before approving a transfer.
- The seller must have legal ownership of the specific payments being transferred.
- The seller must receive statutory disclosures before signing, including discount-rate and net-payment information required by state law.
- A judge must find the transfer is in the seller’s best interest, often considering dependents.
Caution: eligibility to sell is document-specific and state-specific. Do not rely on a general article to transfer payment rights. Check the settlement agreement, the annuity documents, and the applicable court statute before taking action.
Court approval and state protection laws
A structured settlement transfer usually is not valid with a signed contract alone. Federal tax law and state protection statutes typically require advance approval by a court or other authorized decision-maker before future payments can be sold.
The key federal rule is 26 U.S.C. § 5891. It imposes a 40% excise tax on a structured settlement factoring transaction unless the transfer is approved in a qualified order under an applicable state Structured Settlement Protection Act.
That federal tax penalty matters because it pushes buyers to use the state court process. The judge usually reviews the discount, fees, hardship facts, and whether the sale fits the payee’s best interest and any dependents’ welfare.
Most state statutes require a written disclosure before signing. Those disclosures commonly show the amounts being sold, the discounted present value, the gross advance, itemized fees, and the effective discount rate.
The exact wording and timing come from state law, not from the purchasing company.
| Rule or state example | Specific number | Source |
| Federal excise tax if no qualified order applies | 40% | 26 U.S.C. § 5891(a) |
| New York disclosure timing before signing | At least 10 days | New York General Obligations Law § 5-1703 |
| California disclosure timing before signing | At least 10 days | California Insurance Code § 10136 |
| Texas disclosure timing before signing | At least 3 days | Texas Civil Practice and Remedies Code § 141.003 |
Approval standards also vary by state.
Many statutes require findings that the transfer is fair and reasonable, that the payee received independent professional advice or knowingly waived it in writing, and that the transfer does not violate another court order.
Some courts scrutinize transfers involving minors, workers’ compensation settlements, or Medicaid and SSI eligibility more closely. Selling payment rights can change means-tested benefit status or leave too little income later.
A judge may deny a transfer even if the payee wants immediate cash.
- Read the disclosure line by line and compare the gross advance with the total payments being sold.
- Check the current statute in the payee’s state because notice periods and hearing procedures differ.
- Ask a qualified lawyer or accountant about tax, benefits, and family-support consequences before signing.
Caution: state statutes are amended, and local court practice can differ from the statute’s text. A reader should verify the current law in the relevant state code and, where needed, get legal advice before acting.
Discount rates, fees, and net proceeds
The headline offer is not the amount a seller keeps. A structured settlement buyer starts with the future payment stream, applies a discount rate, then subtracts any disclosed charges to reach net proceeds.
That distinction matters. A small change in the discount rate can move the cash offer by thousands of dollars, especially when payments are far in the future.
The discount rate is the core pricing variable. It converts future payments into a present cash value. The farther away the payments are, the more sensitive the offer becomes to the rate used.
Federal law also shapes the process. Internal Revenue Code Section 5891 imposes a 40% federal excise tax on a purchaser that acquires structured settlement payment rights without a qualified court-approved transfer.
That is one reason transfer companies seek court approval.
Itemized deductions vary by transaction and state. Disclosures may show the gross advance, then list administrative, processing, legal, or closing charges if permitted.
The figure to focus on is the net amount payable to the seller after every deduction.
The table below is an illustration, not a market quote. It uses standard present-value math on one $100,000 payment due in 10 years, with no extra fees added, to show how rate changes affect proceeds.
| Assumption | Figure | Source |
| Future payment | $100,000 | Illustration only |
| Time until payment | 10 years | Illustration only |
| Present value at 8% discount rate | $46,319 | Author calculation using standard present-value formula |
| Present value at 12% discount rate | $32,197 | Author calculation using standard present-value formula |
| Present value at 16% discount rate | $22,710 | Author calculation using standard present-value formula |
| Difference between 8% and 16% | $23,609 less cash | Author calculation from figures above |
That example shows why net proceeds deserve more attention than the advertised lump sum. If fees are added after the discount rate is applied, the seller’s actual take-home amount falls again.
Plain caution: do not approve a sale based only on the cash headline. Compare the court disclosure line by line, ask for the effective discount rate, and verify every fee in writing.
If a disclosure is unclear, check the state transfer statute or court filing before signing.
- Ask for the gross advance amount.
- Ask for every fee to be separately itemized.
- Ask for the final net proceeds figure.
- Ask how the offer changes if only part of the payment stream is sold.
Tax issues before selling future payments
Before selling a structured settlement, the main tax question is what kind of payments are being sold and why those payments were tax-free in the first place.
The federal rules are favorable in some cases, but the tax result can change if the original settlement included taxable elements or if the lump sum is later invested.
A seller should read the settlement agreement, annuity contract, and any court papers before signing a transfer. Acting on a quote alone can cause harm, because tax treatment depends on the original claim, not only on the sale price.
Under Internal Revenue Code Section 104(a)(2), damages received on account of personal physical injuries or physical sickness are generally excluded from gross income, according to the Internal Revenue Service.
Structured settlement payments funded through a qualified assignment under IRC Section 130 can preserve that exclusion, according to the IRS and the U.S. Code.
That does not mean every structured settlement payment is tax-free. The IRS states that punitive damages are generally taxable, and interest can also be taxable.
If the original settlement included taxable components, selling those future payments does not erase that tax character.
| Issue | Tax treatment | Source |
| Compensatory damages for personal physical injury | Generally excluded from federal gross income under IRC 104(a)(2) | Internal Revenue Service; 26 U.S. Code § 104 |
| Qualified assignment funding a structured settlement | Can support tax-free periodic payments if statutory requirements are met | 26 U.S. Code § 130 |
| Punitive damages | Generally taxable | Internal Revenue Service; 26 U.S. Code § 104(c) |
| Transfer without required court approval | 40% federal excise tax applies to the factoring discount | 26 U.S. Code § 5891 |
The 40% excise tax in IRC Section 5891 is imposed on the purchaser, not directly on the payee, if a transfer does not receive a qualified court order.
Still, that rule matters to sellers because compliant approval is usually essential to complete the transaction lawfully.
Another issue is what happens after the sale. Even if the original payments were tax-free, earnings on the lump sum are not automatically tax-free.
For example, bank interest is generally taxable under IRS rules, and investment gains may create capital gains tax depending on the asset sold.
- Ask for the exact tax language from the original settlement documents.
- Check whether any payment stream includes punitive damages, interest, or wage-related claims.
- Confirm that the transfer will be approved under the applicable state structured settlement transfer law and IRC Section 5891.
- Have a CPA or tax lawyer review any Form 1099 issued after the sale.
Tax outcomes can turn on small facts. Readers should verify the primary documents and get individualized tax advice before selling future payments.
Comparing structured settlement purchasing companies
Comparing structured settlement purchasers starts with facts a seller can verify: company history, disclosures, and whether the buyer explains the court-approval process.
Price matters most, but a low quote can still be costly if the contract hides fees or uses a steep discount rate.
No major purchaser publishes a universal rate that applies to every case.
The actual offer depends on the payment stream, insurer strength, state law, and how much of the settlement is being sold, so readers should demand a written, itemized quote before signing.
| Company | Founded | What to verify |
| J.G. Wentworth | 1991, according to the J.G. Wentworth company history page | Ask for the discount rate, gross advance, net advance, and any administrative or legal deductions in writing |
| Peachtree Financial Solutions | 1996, according to the Peachtree Financial Solutions company information page | Confirm whether the quote is for a full sale or a partial sale, because selling only selected payments can preserve more future income |
| Stone Street Capital | 1989, according to the Stone Street Capital company profile | Check who prepares the transfer documents and whether the company explains state court timelines clearly |
| Fairfield Funding | 1993, according to the Fairfield Funding about page | Verify whether the company provides a no-obligation quote and a clear closing statement before the hearing |
Use the table as a screening tool, not a final ranking. A longer operating history can show experience, but it does not prove that one quote is cheaper than another.
When comparing offers, focus on the net amount paid to the seller, not the advertised cash figure. The Federal Trade Commission says consumers should review the effective discount rate and all fees before agreeing to sell future payments.
- Get at least three written quotes. A multi-bid comparison is one of the simplest ways to test whether the net payout is competitive.
- Ask whether the sale is full or partial. A partial transfer may reduce long-term harm by leaving some future payments intact.
- Read the disclosure statement line by line. Many states require court approval, and the judge may ask whether the transfer is in the seller’s best interest.
- Do not rely on speed alone. Funding timelines vary because court calendars, notice rules, and insurer responses differ by state.
Caution: selling a structured settlement is usually irreversible after court approval and closing. Readers should compare contracts carefully and, where required or helpful, review the deal with an attorney or financial professional before acting.
What Coin Abul independently reviewed
Coin Abul reviewed the rules, costs, and disclosure standards that affect a structured settlement sale. The review focused on primary sources: state transfer laws, federal tax rules, court-approval requirements, and insurer solvency regulation.
This topic can affect long-term income and tax treatment. Readers should not rely on a summary alone; they should verify terms in the transfer agreement, the court filing, and the annuity issuer’s documents before signing.
The review checked whether a purchaser explains the discount rate, fees, payment schedule, and net amount in writing. Those items matter because sellers compare the cash offered today against the value of future payments they give up.
| Item reviewed | Specific fact | Source |
| Federal tax rule | A qualified structured settlement assignment is governed by Internal Revenue Code Section 130, and transfer excise-tax rules appear in Section 5891. | Internal Revenue Service, U.S. Code via Congress |
| State-law coverage | Structured settlement transfer statutes are in force across states and typically require court or responsible administrative approval before a transfer becomes effective. | National Conference of State Legislatures; state statutes |
| Model disclosure timing | The National Conference of Insurance Legislators model act requires a separate disclosure statement and states a minimum 3-day period before the payee signs a transfer agreement. | NCOIL Model Structured Settlement Protection Act |
| Insurer backstop limits | State guaranty-association protection is limited by state law and often differs by annuity contract type and residence. | National Organization of Life & Health Insurance Guaranty Associations |
Coin Abul also reviewed how judges apply the “best interest” standard. In many states, the court must find that the transfer is in the seller’s best interest and does not contravene a statute or prior court order.
The review compared disclosure practices against the NCOIL model and actual state statutes. It checked whether companies clearly identify the gross advance, itemized fees, effective discount rate, and the aggregate amount of payments being sold.
Because the annuity usually remains with the original issuer, the review also considered issuer strength and guaranty limits. A purchaser’s offer price is separate from the annuity carrier’s claims-paying ability.
- Primary laws reviewed included Internal Revenue Code Sections 130 and 5891.
- State transfer acts were checked for approval, disclosure, and independent-advice provisions.
- Guaranty-association materials were reviewed to confirm that protection caps are state-specific, not universal.
- Consumer-risk points were reviewed from court decisions and state disclosures, especially loss of future income and high effective discounting.
Plain caution: selling a structured settlement can permanently reduce future income.
Before acting, compare the net proceeds to the full payment stream, ask for the discount rate in writing, and confirm state-law rights with the court documents or a qualified attorney.
Alternatives to selling settlement payments
Selling structured settlement payments can produce cash fast, but it permanently trades away future income and usually requires a court review under state structured settlement protection laws.
Before giving up payments, compare options that may solve a short-term cash problem with less long-term damage.
Use primary documents before acting. Loan costs, tax effects, and eligibility rules vary by lender, plan document, insurer, hospital, and state law.
Some alternatives work best when the need is temporary, such as a medical bill, rent gap, or car repair. Others can help reduce the amount that must be raised, which may let a payee avoid selling any payments at all.
| Alternative | Verified facts | Why it may cost less than a sale |
| Credit union payday alternative loan | Federal credit unions may offer PALs I from $200 to $1,000 for 1 to 6 months, and PALs II from $200 to $2,000 for 1 to 12 months. The APR is capped at 28%, and an application fee may not exceed $20. Source: National Credit Union Administration rule 12 CFR 701.21. | The dollar cost can be smaller than surrendering years of future settlement income, especially for short-term needs. |
| 401(k) loan, if available | The IRS says many plans allow borrowing the lesser of $50,000 or 50% of the vested account balance. Repayment terms and availability depend on the plan. Source: Internal Revenue Service retirement plan loan rules. | No court transfer is required, and the borrowing limit is defined by federal tax rules rather than a purchaser’s discount rate. |
| Hospital financial assistance or payment plan | Tax-exempt hospitals must have a written financial assistance policy and limit charges for eligible patients under Internal Revenue Code Section 501(r). Source: Internal Revenue Service. | A reduced bill or no-interest payment plan can lower the cash need directly, instead of selling future payments. |
Other practical steps can reduce pressure before a sale decision:
- Ask providers for itemized bills and hardship review. Billing errors and charity-care screening can change the balance owed.
- Negotiate a payment plan with the landlord, utility, or medical provider. A delayed due date may solve a timing problem without new debt.
- Check public benefits. The Federal Reserve’s 2023 Survey of Household Economics and Decisionmaking found 37% of adults would borrow, sell something, or miss a payment for a $400 emergency, which shows many households qualify for assistance when cash is tight.
Caution: borrowing against retirement, using home equity, or taking any high-rate loan can create new risks, including taxes, foreclosure, or collection.
Read the contract, confirm total repayment, and get legal or tax advice before replacing one long-term asset with another obligation.
Frequently Asked Questions
What does purchasing a structured settlement mean?
Purchasing a structured settlement usually means a factoring company buys some or all of a person’s future settlement payments in exchange for a lump sum today.
These transactions are commonly subject to state structured settlement protection laws and court approval, so a seller should review the transfer terms carefully and confirm the exact approval rules in the relevant state before acting.
How is the lump-sum offer on a structured settlement calculated?
The buyer typically discounts the future payment stream to a present value, then applies fees, costs, and its required return.
The exact amount can vary widely by payment schedule, timing, and company terms, so a seller should request a written breakdown and compare it against the original annuity and settlement documents before signing.
Does a court have to approve the sale of structured settlement payments?
In many cases, yes: transfers are often reviewed under state structured settlement protection acts to determine whether the sale is in the payee’s best interest.
Because approval standards and procedures differ by state, a seller should check the applicable statute or court rules and consider independent legal or financial advice before relying on any company’s summary.
Can someone sell only part of a structured settlement instead of the whole agreement?
Yes, some transactions involve selling only selected payments, a portion of payments, or payments for a limited period rather than the full stream.
That can reduce how much long-term income is given up, but it still changes future cash flow, so the seller should confirm exactly which payments would remain and which would be transferred.
Related Reading
- Vanguard Immediate Annuity Rates
- Buy Structured Settlement – What You Need to Know?
- Structured Settlement Quotes
- Structured Settlement Payout
- JG Wentworth Loan Reviews
- What Is A Structured Annuity?
- Structured Settlement Loans – What You Need to Know
- Structured Settlement Buyer – What You Need to Know
- Structured Settlement Annuity Companies
- All Blog Guides