
Quick answer: Best Structured Settlement Companies are those with strong court-approval experience, transparent discount rates, clear timelines, and no pressure tactics. Commonly compared firms include J.G.
Wentworth, DRB Capital, and Fairfield Funding, but the best choice depends on state law, payout terms, and fees. Get independent legal or financial advice before selling payments.
Best Structured Settlement Companies are settlement-purchasing firms that clearly disclose discount rates, court-approval requirements and complaint records before buying future structured settlement payments.
The strongest choices are typically established purchasers with transparent underwriting, state-specific legal guidance and verifiable reputations through sources such as the Better Business Bureau, state court records and consumer finance regulators.
Caution: Selling payments can permanently reduce long-term income and usually requires a judge’s approval.
Readers should compare written offers, review the transfer petition and consult an independent attorney or financial adviser before relying on any company’s estimate.
Best structured settlement companies for sellers
The best structured settlement company for a seller is usually the one that offers the highest net cash after fees, explains the discount rate clearly, and has experience getting transfers approved by a judge.
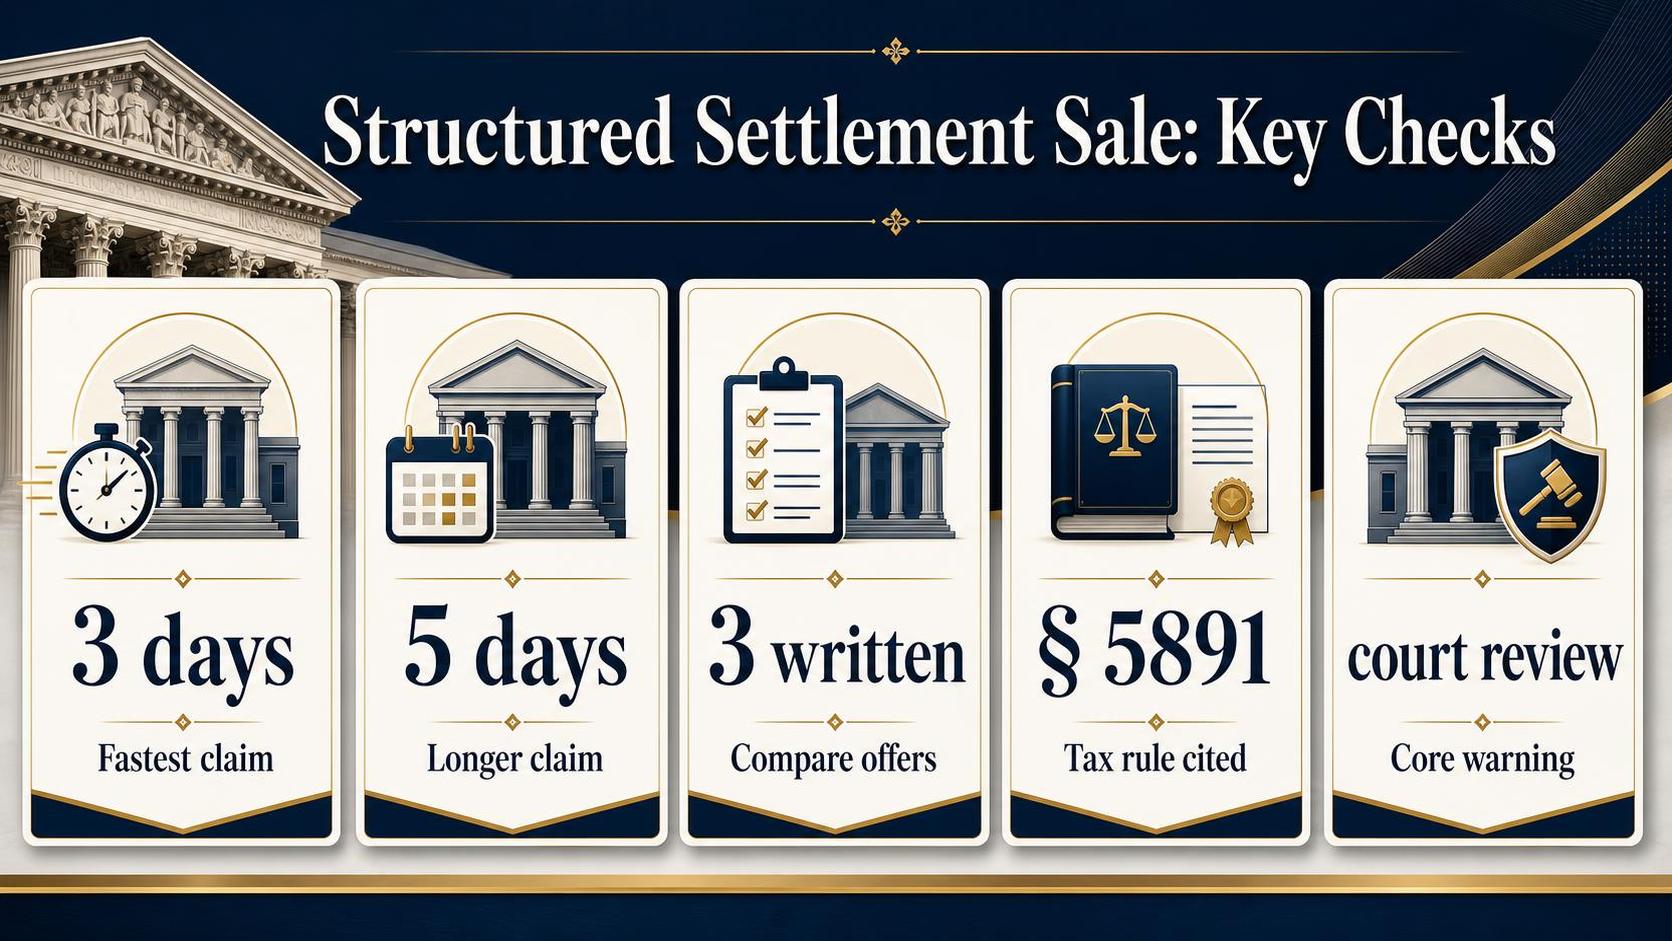
Court approval is central because Internal Revenue Code §5891 imposes a 40% excise tax on nonqualified transfers.
Readers should not act on marketing claims alone. Selling payments can permanently reduce long-term income, and state transfer laws vary. Review the petition, discount rate, fees, and independent professional-advice requirements before signing.
| Company | Seller fit | Specific facts to verify |
| J.G. Wentworth | Large, national buyer often considered by sellers who want a well-known brand and a structured settlement factoring process with court filing support. | The company states that it has operated since 1991. Sellers should verify the current legal entity, BBB profile, complaint history, and any state registration before accepting an offer. |
| Peachtree Financial Solutions | Often compared with J.G. Wentworth because both brands have operated in the structured settlement purchasing market for many years. | Peachtree says it was founded in 1996. Sellers should compare its quoted discount rate, filing costs, and servicing instructions against at least 2 other written quotes. |
| DRB Capital | May suit sellers seeking a specialist purchaser focused on structured settlement and annuity payment purchases rather than general consumer lending. | DRB Capital’s public materials describe it as a purchaser of structured settlement and annuity payments. Check current court-transfer filings and consumer complaint databases before proceeding. |
| Fairfield Funding | May be useful as a competing quote source, especially for sellers who want to compare smaller or mid-market purchasers against national brands. | Fairfield Funding publicly advertises structured settlement payment purchases. Confirm whether the quote includes all fees and whether the company or an affiliate will be the actual buyer. |
How to choose among them
- Get at least 3 written quotes. A small change in the discount rate can materially change the lump sum because future payments are being priced today.
- Ask for the effective annual discount rate. Do not rely only on the gross lump-sum number. Ask whether legal, filing, administrative, broker, or servicing fees are deducted.
- Check the court process. Most structured settlement protection acts require a judge to find that the transfer is in the seller’s best interest, but wording differs by state.
- Read the disclosure statement. Many state laws require disclosure of the payment stream being sold, present value, gross advance, fees, and net amount payable.
- Use primary sources. Check the state court docket, the state structured settlement transfer statute, the IRS §5891 rule, BBB profiles, and CFPB complaint records where available.
A company’s size or advertising budget does not prove that selling is a good decision.
Sellers should consider alternatives such as budgeting, hardship programs, insurance claim review, or legal advice before giving up guaranteed future payments.
How structured settlement buyers compare
Structured settlement buyers do not compete only on the headline cash offer. The safer comparison is the net amount paid, the discount rate, the court process, and how clearly the company explains the trade-off.
Readers should not rely on advertising alone. Selling future payments is usually irreversible after court approval, and it can reduce long-term income for medical care, housing, or retirement.
| Comparison point | What to check | Why it matters |
| Legal approval | The Internal Revenue Code, 26 U.S.C. § 5891, imposes a 40% excise tax on a transfer unless it is approved by a qualified court or administrative order. | A buyer that treats court approval as optional is a major red flag. |
| State transfer law | The National Structured Settlements Trade Association says 49 states and the District of Columbia have structured settlement protection acts. | State law usually requires disclosure and a judge’s best-interest review before payments can be transferred. |
| Discount rate | Compare the effective annual discount rate, not just the lump sum. Higher rates mean the seller gives up more future value. | Two buyers can quote similar cash today but very different long-term costs. |
| Fees and deductions | Ask whether legal, filing, servicing, courier, or administrative costs are deducted from the quoted amount. | The relevant number is net cash received after all deductions. |
| Partial versus full sale | Compare offers for selling only selected payments, a fixed number of years, or a percentage of each payment. | A partial sale may preserve some future income and may be less harmful than selling all payments. |
| Cancellation rights | Check the specific state disclosure form and transfer agreement for any cancellation period. | Cancellation rights vary by state, so the primary document matters more than a salesperson’s summary. |
Practical signals of a stronger buyer
- Written net offer: The quote should show gross purchase price, fees, net proceeds, payments being sold, and the discount rate.
- No pressure tactics: A reputable buyer should allow time to compare offers and consult a lawyer, tax adviser, or financial counselor.
- Clear court timeline: The buyer should explain petition filing, notice to the annuity issuer, hearing requirements, and possible delays.
- Independent professional advice: Some state laws require or encourage independent advice. Even when not required, it can protect the seller from a poor decision.
Plain caution: a lump sum can solve an urgent problem, but it can also remove guaranteed future payments. Anyone considering a sale should verify state rules, read the court disclosures, and compare multiple written offers before signing.
What editors independently reviewed
Editors reviewed structured settlement purchasing companies using public records, court-process disclosures, advertising claims, and consumer-facing terms.
The review focused on whether a company clearly explains the court approval process, pricing uncertainty, and the legal limits that apply before payments can be transferred.
This section is informational only.
Selling structured settlement payments can permanently reduce future income, and readers should not rely on rankings or advertising alone before speaking with an attorney, tax professional, or court-appointed adviser where required.
| Review item | What was checked | Source for the figure or rule |
| 10 companies | Editors compared public websites, state disclosures, Better Business Bureau profiles where available, and court-process explanations for 10 structured settlement purchasers. | Coin Abul editorial review of public company materials. |
| 6 core factors | Transparency, court-process explanation, state availability, complaint signals, educational accuracy, and whether advertising avoids guaranteed-cash promises. | Coin Abul editorial methodology. |
| 40% federal excise tax | Editors checked whether companies explained that unapproved structured settlement factoring transactions can trigger a federal excise tax. | Internal Revenue Code Section 5891, published by the IRS and Legal Information Institute. |
| 2 key tax statutes | Editors checked whether educational pages distinguished personal-injury settlement tax exclusion rules from qualified assignment rules. | Internal Revenue Code Sections 104(a)(2) and 130. |
Documents and disclosures examined
- Company websites: Editors reviewed whether each company describes itself as a purchaser or factoring company, rather than a lender, because a structured settlement transfer is generally a sale of payment rights.
- State court process explanations: Editors looked for clear statements that transfers normally require a judge’s approval under state structured settlement protection laws. State requirements differ, so readers should check the statute and court rules in their own state.
- Pricing language: Editors reviewed whether companies explain that the lump sum is less than the total future payments because purchasers apply a discount rate, fees, or transaction costs.
- Consumer-risk warnings: Editors gave more weight to companies that warn about losing guaranteed future income, public-benefit complications, and the risk of spending a lump sum too quickly.
- Complaint and reputation signals: Editors considered public complaint patterns from sources such as the Better Business Bureau and state attorney general materials when available, but did not treat star ratings as proof of service quality.
Editors did not accept paid placement, referral fees, or company-provided rankings as evidence of quality.
A company’s advertising claim was treated as unverified unless it could be matched to a public source, legal filing, or clearly stated disclosure.
Fees, discounts and court approval
Structured settlement buyers make money mainly through the discount applied to future payments, not just through visible fees.
A lower cash offer can cost far more than an application or court fee, so compare the net amount paid, the discount rate and the court papers.
Under Internal Revenue Code Section 5891, a transfer that lacks a “qualified order” can trigger a 40% federal excise tax on the factoring discount.
That is why legitimate structured settlement transfers generally require state-court approval before the annuity issuer redirects payments.
| Item to compare | Why it matters | Source or basis |
| Discount rate | This is the annualized rate used to reduce future payments to today’s cash value. A higher rate means the seller receives less cash. | Required disclosure in many state Structured Settlement Protection Acts; court reviews vary by state. |
| Federal tax penalty if not court-approved | 40% excise tax on the factoring discount may apply to non-qualified transfers. | Internal Revenue Code Section 5891(a). |
| Best-interest finding | The judge typically must find the transfer is in the payee’s best interest, considering dependents and welfare. | Internal Revenue Code Section 5891(b)(2)(A)(ii) and state protection acts. |
| Illustrative value of $100,000 due in 10 years at 12% | About $32,197 before fees; the same payment at 18% is about $19,121. | Present-value calculation using annual compounding: $100,000 ÷ (1+r)^10. |
The most important “fee” is often the gap between the future payments sold and the cash received.
A buyer may also deduct filing costs, administrative charges, legal expenses or lien payoffs, but the labels and amounts vary by company and court.
- Ask for the gross purchase price and net amount paid. The net figure is what the seller actually receives after deductions.
- Ask for the annual discount rate. Do not rely only on a lump-sum offer, because two offers can look similar while using different rates and fees.
- Ask who pays court costs if approval is denied. Some agreements shift expenses to the buyer, while others may allow deductions; read the contract and petition.
- Check the state statute and court order. Filing rules, disclosure timing and required findings are state-specific.
Caution: A court approval hearing is not the same as personalized financial advice. Selling guaranteed future payments can affect Medicaid, SSI, taxes, debt collection and long-term income.
Readers should review the petition with an independent attorney or qualified adviser before signing.
Questions to ask before selling payments
Selling structured settlement payments is usually irreversible after court approval, so price, timing and legal safeguards matter.
A buyer’s headline offer is less important than the net cash received, the discount rate and whether the transfer order complies with federal and state law.
Plain caution: Do not rely on a company’s verbal estimate alone. A judge, independent professional adviser or state disclosure form may identify costs or rights that are not obvious in an advertisement.
- What is the effective discount rate? Ask for the annual discount rate used to convert future payments into today’s cash. The rate should be shown in writing, not described only as a lump-sum “offer.”
- What is the net amount after all fees? Request a disclosure listing gross purchase price, filing fees, attorney fees, broker fees, servicing charges and any liens. Compare net cash, not just the advertised payout.
- Does the transfer require court approval? Under Internal Revenue Code Section 5891, a transfer must be approved in a “qualified order” under an applicable state structured settlement protection act to avoid a federal excise tax.
- Will an independent professional adviser review it? Many state protection acts require, or let the court require, advice from an attorney, CPA, actuary or other independent adviser. Ask who pays for that advice and whether the adviser is truly independent.
- How will the sale affect taxes, benefits and child support? Selling payments may affect Medicaid, SSI, housing assistance, support orders or bankruptcy issues. A settlement buyer is not a substitute for a benefits or tax professional.
- What happens if the judge says no? Ask whether any fees are owed if the petition is denied, withdrawn or delayed. Get the answer in the transfer agreement.
| Fact to verify | Why it matters | Source |
| 40% federal excise tax | Applies to the factoring discount if a structured settlement transfer lacks a qualified court order. | Internal Revenue Code Section 5891(a) |
| State court approval | The judge must find the transfer meets the applicable state protection act, commonly including the seller’s best interest. | Internal Revenue Code Section 5891(b); state structured settlement protection acts |
| 10-day cooling-off period in the model act | The NCOIL Structured Settlement Protection Act model includes a right to cancel within 10 days after signing, but states may differ. | National Council of Insurance Legislators model act |
Before signing, ask for competing written quotes using the same payment stream and funding date. If the buyer changes the purchase price after medical, court or annuity review, require a new disclosure before moving forward.
Plain caution: A lower lump sum may permanently reduce long-term income for housing, medical costs or retirement.
Anyone unsure should pause and check the court file, the annuity issuer’s records and the applicable state statute before agreeing.
Risks of selling structured settlement rights
Selling structured settlement payment rights can solve an immediate cash problem, but it permanently trades guaranteed future income for a smaller lump sum.
A court order is usually required, and the financial harm can be difficult to reverse once the transfer is approved.
Readers should not rely on general articles alone when deciding whether to sell payments. A licensed attorney, tax professional, or court-appointed adviser can review the actual transfer agreement, state law, fees, and long-term impact.
Key legal and financial risks
- Loss of future income: Structured settlements often exist to replace wages, medical support, or long-term care funding. Selling payments may leave fewer resources for rent, health costs, dependents, or retirement.
- Discounting can be expensive: Buyers do not pay the full face value of future payments. The lump sum reflects a discount rate, timing of payments, company costs, profit margin, and sometimes administrative fees.
- Court approval does not guarantee a good deal: State structured settlement protection acts generally require a judge to decide whether the transfer is in the seller’s “best interest.” That is a legal safeguard, not a promise that the price is optimal.
- Tax protection can be jeopardized if rules are ignored: Personal physical injury damages are generally excluded from gross income under Internal Revenue Code Section 104(a)(2). Transfers must be handled carefully to preserve applicable tax treatment.
- Pressure and repeat selling: A seller who transfers one payment stream may later be encouraged to sell more. Repeated sales can eliminate the very income security the settlement was designed to provide.
| Risk or rule | Specific figure | Source |
| Federal penalty if a structured settlement factoring transaction is not approved by a qualified court order | 40% excise tax on the factoring discount | Internal Revenue Code Section 5891(a) |
| Federal standard for a qualified order | Court must find the transfer is in the payee’s best interest, considering dependents’ welfare | Internal Revenue Code Section 5891(b)(2)(A) |
| Hypothetical sale illustration | Selling $100,000 of future payments for $60,000 gives up $40,000 before considering timing, inflation, or fees | Arithmetic example based on stated figures |
| Tax exclusion commonly associated with qualifying injury settlements | Damages for personal physical injuries or physical sickness are excluded from gross income | Internal Revenue Code Section 104(a)(2) |
Practical cautions before signing
- Compare the net lump sum, not just the advertised quote. The transfer petition and disclosure statement should show fees, amounts assigned, and the effective discount rate if state law requires it.
- Check whether the sale affects public benefits, child support, bankruptcy issues, medical liens, or divorce orders. These consequences are fact-specific and can be severe.
- Ask the court or an independent professional whether selling a smaller portion of payments would meet the same need with less long-term damage.
- Verify the buyer’s licensing, registration, and complaint history with the state court record, state attorney general, insurance department, or consumer protection agency where applicable.
Alternatives to structured settlement sales
Selling structured settlement payments can provide cash, but it usually means accepting less than the future payment stream is worth. Before agreeing to a transfer, compare options that may preserve tax-advantaged future income.
Plain caution: this is money and legal content. A reader should not rely on this section alone; review the settlement documents, state transfer law, tax rules and any court order with qualified professionals.
| Alternative | When it may fit | Specific fact to check | Main caution |
| 401(k) plan loan | Short-term cash need and the borrower is still employed by the plan sponsor. | The IRS says many plans limit loans to the lesser of $50,000 or 50% of the vested account balance, with repayment generally required within 5 years. | Job loss can accelerate repayment, and unpaid balances may become taxable distributions. |
| Medical bill negotiation or financial assistance | Hospital, surgery or emergency-care debt is the reason for seeking cash. | The IRS says deductible medical expenses are generally the amount exceeding 7.5% of adjusted gross income, if the taxpayer itemizes. | Tax deductibility is not the same as affordability; ask the provider about charity-care and payment-plan policies first. |
| Home equity loan or HELOC | The person owns a home and needs a larger amount than a small personal loan can provide. | The Federal Reserve’s Consumer Credit data and lender disclosures show home-equity pricing varies by market rate, credit profile and lien position. | Home equity borrowing is secured by the home, so missed payments can risk foreclosure. |
| Benefits review | The cash need is tied to disability, caregiving, housing, food or medical coverage. | Benefits.gov is the federal portal for screening more than 1,000 government benefit and assistance programs. | Eligibility rules are detailed, and lump-sum cash from financing can affect some means-tested benefits. |
- Ask the annuity issuer or settlement administrator about timing. Some payees only need confirmation of payment dates, address changes or lost-check procedures. This does not create new cash, but it may solve a timing problem without selling payments.
- Negotiate the underlying expense. Medical providers, tax agencies, landlords and creditors may offer installment agreements. Get terms in writing, including fees, interest, due dates and default consequences.
- Compare unsecured credit carefully. A bank or credit-union personal loan may be simpler than a court-approved transfer, but approval, APR and fees depend on creditworthiness and state law.
- Seek local legal aid or a settlement adviser. Structured settlement transfers are typically reviewed by a state court under a Structured Settlement Protection Act. The court process is meant to evaluate whether the sale is in the payee’s best interest.
Any alternative can carry costs. The safest comparison is the total dollars received now, total dollars repaid or given up later, tax effects and whether essential future income would remain protected.
Frequently Asked Questions
What should consumers look for in the best structured settlement companies?
Consumers should look for transparent pricing, clear disclosure of the discount rate, court-approval support, and a record of operating under state structured settlement protection acts.
A sale can permanently reduce future income, so readers should compare written offers and consult an independent attorney or financial professional before signing.
Are structured settlement purchasing companies the same as the annuity companies that make payments?
No. Annuity issuers such as life insurance companies make the scheduled structured settlement payments, while purchasing companies buy some or all future payments for a lump sum.
The National Association of Insurance Commissioners explains that structured settlements are commonly funded through annuities, but selling payment rights is a separate transaction that generally requires court approval.
Do structured settlement companies have to get court approval?
In most U.S. states, transfers of structured settlement payment rights must be reviewed by a court under a structured settlement protection act.
The court typically considers whether the sale is in the payee’s best interest, but approval standards and required disclosures vary by state, so readers should check their state statute or court paperwork.
How do structured settlement companies decide the lump-sum offer?
Companies generally calculate an offer by discounting future payments to a present cash value, then subtracting costs and profit margin.
Because the discount rate can significantly affect how much money the seller gives up, consumers should request the rate in writing and compare multiple offers before relying on any single quote.
Are there risks in choosing a structured settlement company based only on advertising?
Yes. Advertising may emphasize fast cash while downplaying the long-term cost of selling guaranteed future payments.
Readers should verify licensing or registration where applicable, review court disclosures carefully, and avoid making a decision without independent legal or financial advice.
Should I consider selling only part of my structured settlement instead of all future payments?
Yes. The article says sellers should compare offers for selling only selected payments, a fixed number of years, or a percentage of each payment. A partial sale may preserve some future income and may be less harmful than selling all payments.
Compare at least 3 written quotes and ask for the effective annual discount rate, all fees, and the net cash received.
Then review the disclosure statement and transfer petition, because selling payments can permanently reduce long-term income and usually requires a judge’s approval.