
Key takeaway: Sunrise Lawsuit Funding is a pre-settlement funding company that offers non-recourse cash advances to plaintiffs with pending legal claims. Repayment typically comes from a future settlement or verdict, not monthly payments.
Terms, fees, and availability vary, so borrowers should review the contract and consult their attorney before accepting funding.
Sunrise Lawsuit Funding is a pre-settlement funding subject involving cash advances tied to pending legal claims, not a traditional loan.
Readers should verify whether “Sunrise” refers to a specific funding company, brand, or search term before relying on any rate, fee, or approval claim.
This article explains how lawsuit funding generally works, what documents funders review, why costs can compound, and why state law matters.
Caution: do not sign a funding contract based on general information alone; ask an attorney to review terms, repayment triggers, and alternatives.
What Sunrise Lawsuit Funding does
Sunrise Lawsuit Funding operates in the lawsuit funding segment, where a company may advance cash to a plaintiff before a case ends.
In that model, the company reviews the claim, prices the risk, and seeks repayment from case proceeds if the claim resolves successfully.
Readers should not treat a funding company as a law firm, insurer, or financial adviser. Terms can materially change what a plaintiff repays, so the contract and the attorney’s review matter more than marketing language.
At a practical level, Sunrise’s role is to bridge time. Plaintiffs often wait months or longer for a settlement or judgment, while living costs continue.
A funding company steps in during that gap and decides whether the expected recovery supports an advance.
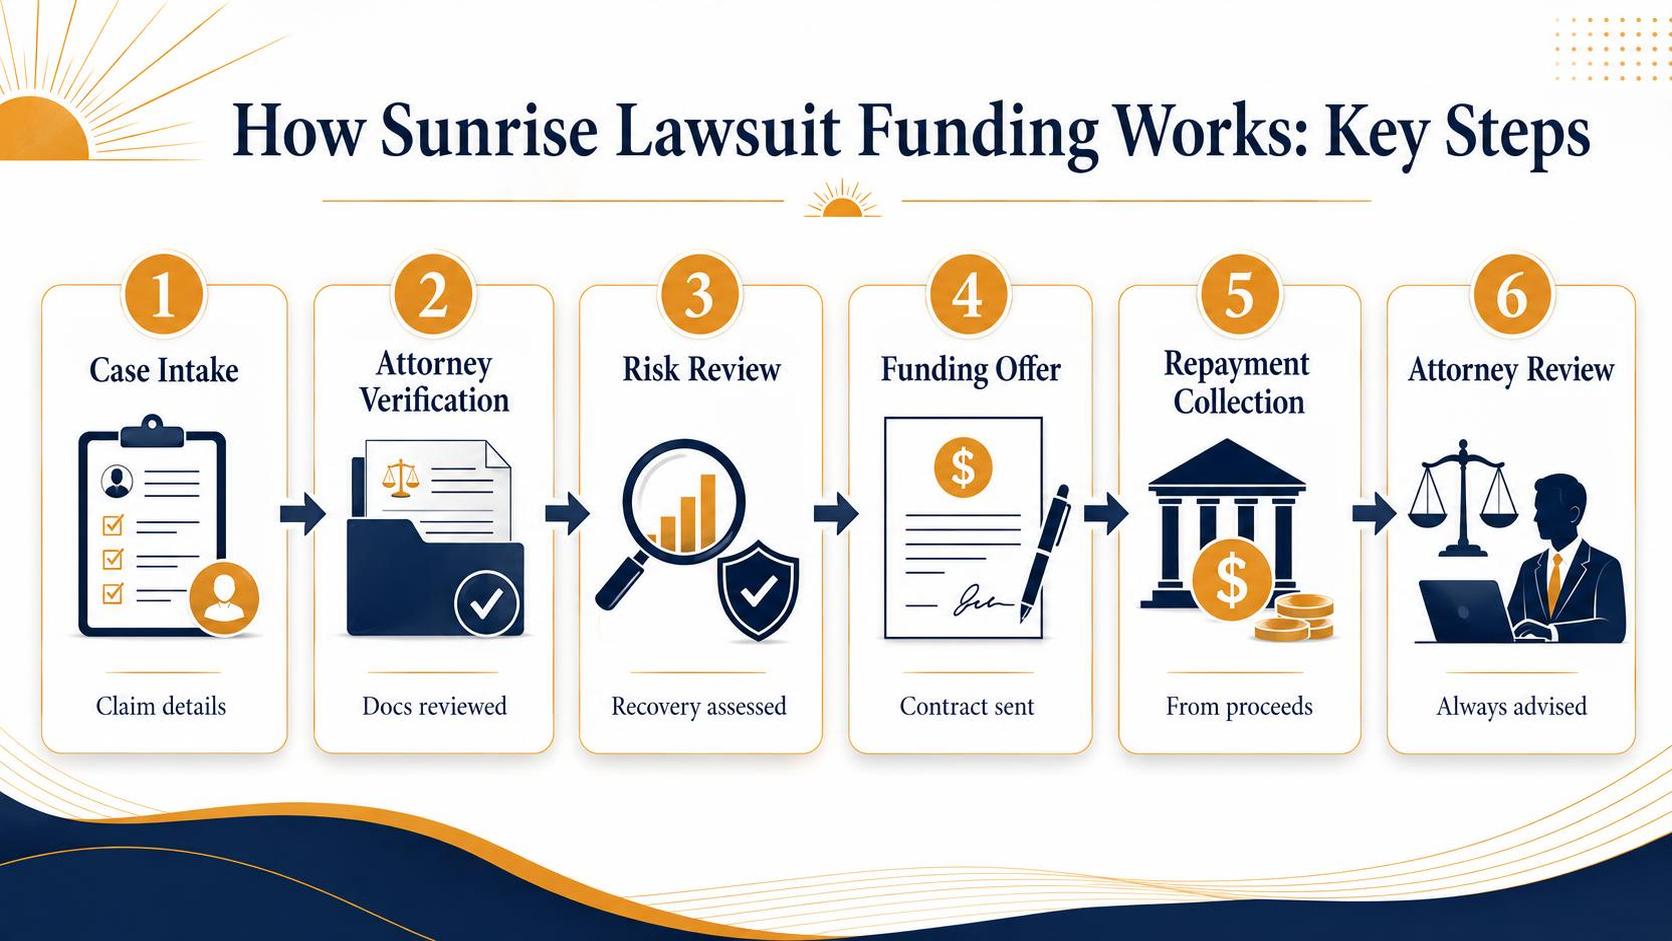
That work usually starts with intake. The company asks for basic case information and then requests documents from the plaintiff’s lawyer.
Typical records include the complaint, accident reports, medical records, insurance correspondence, and any existing settlement discussions.
Next comes underwriting. The company assesses liability, damages, insurance coverage, and collectability.
It is not deciding who is legally right; it is estimating whether the case is likely to produce proceeds and whether those proceeds will be enough to cover the advance and contract charges.
| Function | What it means for the plaintiff |
| Case intake | The company gathers claim details and attorney contact information. |
| Attorney verification | The plaintiff’s lawyer confirms the case status and provides documents. |
| Risk review | The company evaluates expected recovery, timing, and repayment risk. |
| Funding offer | If approved, the company sends a contract stating the advance amount and charges. |
| Repayment collection | If the case pays out, repayment is typically taken from the plaintiff’s proceeds through the attorney’s trust account. |
Sunrise also functions as a contract counterparty, not merely a source of cash.
That means the important product is the written agreement itself: the amount advanced, when charges accrue, whether fees compound, and what happens if the case settles for less than expected.
A plain caution matters here. Consumer Financial Protection Bureau materials on legal funding warn that these products can be expensive and are not the same as ordinary bank credit.
Before signing, a plaintiff should ask the attorney to explain the full payoff under several settlement scenarios and verify every number in the contract itself.
How Sunrise pre-settlement funding works
Sunrise Lawsuit Funding describes pre-settlement funding as a non-recourse cash advance tied to a pending legal claim.
In a non-recourse deal, repayment comes from the case proceeds if the claimant recovers money; if there is no recovery, the company generally does not collect from the claimant directly.
Readers should confirm that exact language in Sunrise’s contract before signing.
The process usually starts with an application and basic case details.
Sunrise then asks for information from the claimant’s lawyer, because the company must evaluate liability, damages, insurance coverage, and how close the case may be to settlement or trial.
That review matters because lawsuit funding is not underwritten like a standard personal loan.
The Consumer Financial Protection Bureau said in a 2022 Issue Spotlight that legal financing is typically based on the expected value of the legal claim rather than a consumer’s income or credit score.
That is why the attorney’s cooperation is central.
| Stage | How it usually works | What to check |
| Application | The claimant submits contact and case information to Sunrise. | Whether Sunrise runs a credit check, and whether any application fee applies. |
| Attorney review | Sunrise contacts the lawyer for documents and case status. | Which records are required and whether the attorney must sign an acknowledgment. |
| Offer | If approved, Sunrise sends a funding agreement with the advance amount and pricing terms. | The total payoff at 6, 12, and 24 months, using the company’s written schedule. |
| Funding | After signatures, funds are sent to the claimant, often through the attorney’s trust process. | How the money is delivered and whether any wire or transfer fee is deducted. |
| Repayment | Sunrise is paid from settlement or judgment proceeds. | Whether charges compound, whether multiple advances are allowed, and payoff order. |
The most important step is reading the pricing section.
The CFPB warned in the same 2022 spotlight that some legal finance products can be expensive and hard to compare, especially when contracts use fees instead of a familiar annual percentage rate.
Ask for a written payoff schedule, not only a verbal explanation.
Consumers should also verify whether the agreement is fully non-recourse, whether charges compound monthly, and whether the company can fund more than once on the same case. Those terms can materially change the final payoff.
Plain caution: do not rely on a short advertisement or a phone summary. Use the actual Sunrise contract, have the attorney review every charge and repayment clause, and compare it with the rules in the claimant’s state before accepting funds.
Costs and repayment terms to verify
Do not rely on marketing language alone. For any Sunrise Lawsuit Funding offer, the only numbers that matter are the funded amount, every fee, whether charges compound, and the exact dollar payoff if the case settles later than expected.
Ask for the payoff schedule before signing. That step matters because lawsuit funding is usually repaid from settlement proceeds, and small percentage differences can produce a much larger payoff over time.
Start with the funded amount versus the amount actually sent. If a contract shows a $5,000 advance but deducts underwriting, origination, wire, or processing fees, the net proceeds can be lower than the headline number.
Verify each deduction in writing.
Next, verify how the charge grows. A contract can use simple monthly pricing, periodic flat fees, or compounding. Compounding matters because interest can be charged on prior interest, not only on the original advance.
If the contract is unclear, ask for the exact formula.
| Item to verify | What to request | Why it matters |
| Amount funded | The gross advance and the net dollars actually disbursed | Shows whether fees are taken out before funding |
| Pricing method | Monthly rate, flat fee, or other charge, plus whether it compounds | Determines how fast the payoff grows |
| Payoff checkpoints | The exact payoff at 6, 12, and 24 months | Reveals the real cost if the case lasts longer |
| Repayment trigger | Whether payment is due only from case proceeds | Confirms whether the deal is truly non-recourse |
| Extra fees | Wire, document, underwriting, servicing, and payoff statement fees | Prevents surprise deductions later |
Also check whether the contract allows multiple advances. A second advance can create a new fee stack and a higher total payoff. Request a combined payoff schedule showing all advances together, not separate quotes that are hard to compare.
If the agreement references state law, read that section closely. Some states regulate consumer legal funding with disclosure rules or fee limits, but those rules vary. Check the text of the statute or ask a lawyer in the state named in the contract.
- Get the full contract before authorizing funding.
- Match the payoff schedule to your lawyer’s expected case timeline.
- Do not sign until your attorney confirms the lien and repayment language.
Caution: do not estimate these costs from advertisements or verbal explanations. Sign only after reviewing the written contract and payoff schedule with your attorney, because repayment terms can materially reduce your net settlement.
Eligibility for Sunrise lawsuit advances
Eligibility for a Sunrise lawsuit advance usually depends on the lawsuit, not the applicant’s paycheck or credit file.
The key question is whether the underlying claim appears strong enough for Sunrise to recover from a future settlement or verdict.
Sunrise publicly describes its product as non-recourse funding, meaning repayment is tied to case proceeds rather than ordinary monthly debt service.
That structure makes case merits, expected value, and attorney cooperation more important than income-based underwriting.
In practice, the first screen is whether there is an active civil claim.
Pre-settlement funders commonly focus on personal injury, wrongful death, medical malpractice, employment, and similar plaintiff-side matters because those cases can produce monetary recoveries.
Sunrise’s own intake materials should be checked for its current case types.
The second screen is attorney involvement. Lawsuit funding companies typically require the applicant to be represented by a lawyer, because the funder needs case documents, insurance information, and a signed acknowledgment from counsel.
A self-represented plaintiff may have difficulty qualifying.
| Eligibility factor | Why it matters | Public Sunrise number? |
| Open lawsuit or claim | No case usually means no source of repayment | No universal minimum publicly posted |
| Attorney representation | Allows document review and payoff coordination | No public exception policy found |
| Expected settlement or verdict value | Helps the funder estimate whether proceeds can cover the advance and fees | No public dollar threshold found |
| Liability and damages evidence | Police reports, medical records, and insurance details affect risk | No public scoring formula found |
| Existing liens or prior advances | Too many claims on the settlement can reduce approval odds | No public cap found |
Sunrise does not appear to publicly post a minimum credit score, minimum income, or debt-to-income ratio requirement in the same way a consumer lender would.
That is consistent with non-recourse legal funding, but applicants should confirm current underwriting rules directly with Sunrise and their attorney.
Some state laws can also affect eligibility. For example, legal funding is regulated in several states, and contract disclosures may be mandatory.
State rules change, so applicants should verify requirements with their state regulator or review the controlling statute before signing.
- Have the case number, attorney contact information, and basic accident or incident facts ready.
- Ask whether Sunrise needs medical records, insurance limits, or prior settlement offers.
- Ask whether existing medical liens, child-support liens, or earlier advances affect approval.
- Request the full contract and disclosure statement before accepting funds.
Caution: Approval standards, fees, and state-law disclosures can materially change the cost of an advance. Do not rely on a summary alone; review the written contract and have your attorney explain repayment terms before signing.
Risks before accepting lawsuit funding
Lawsuit funding can provide cash before a case settles, but the cost can be high and the contract can be hard to unwind.
Before accepting funds from Sunrise Legal Funding or any other company, compare the pricing method, payoff growth, and state-specific legal protections.
The largest risk is not monthly cash flow. It is how fast the repayment balance can grow while the case remains open. A second risk is assuming “non-recourse” means “low-cost.” It does not.
Consumer legal funding is usually structured as a non-recourse advance. The American Bar Association explains that non-recourse means the company is repaid only if the consumer recovers money in the case.
That feature protects against owing money after a total loss, but it does not cap pricing.
| Risk point | Verified fact | Why it matters |
| Fee level | The Consumer Financial Protection Bureau said in a 2023 issue spotlight that consumer litigation funding can carry “fees equivalent to an annual percentage rate of 100% or more.” | A balance can rise far faster than many borrowers expect. |
| Repayment example | The CFPB also described a $3,000 advance that could require about $9,000 repayment after 36 months. | Long cases can consume a large share of settlement proceeds. |
| Compounding risk | The Government Accountability Office reported in 2022 that some contracts use compounding fees, while others use flat fees. | Compounding usually increases payoff faster than simple pricing. |
| Regulatory variation | West Virginia caps charges at 18% a year under W. Va. Code 46A-6N-6. Other states use different rules or no dedicated cap. | Your state may offer very different protection than another state. |
Contract design matters as much as the headline rate. The GAO’s 2022 report on third-party litigation financing found material variation in disclosures, fee structures, and contract terms.
Ask whether pricing is monthly or annual, simple or compound, and whether fees continue after a case settles but before payment arrives.
- Check for multiple advances. A second advance can stack fees on top of the first contract.
- Ask about cancellation rights. Some states require a rescission period, but the number of days varies by law.
- Confirm whether attorney acknowledgment is required. Many funders will not send money without it.
- Request the exact payoff amount for 6, 12, 18, and 24 months in writing.
Do not rely on an advertisement or a verbal estimate alone. Read the contract and verify state law in the statute or with a qualified attorney, because a funding agreement can materially reduce the net amount a plaintiff keeps after settlement.
What editors checked about Sunrise
Editors checked Sunrise’s public site for the details that matter most in lawsuit funding: company identity, pricing transparency, contract language, and complaint channels.
The goal was simple: separate marketing claims from verifiable disclosures before a reader relies on them.
This matters because pre-settlement funding can be expensive, and terms vary by contract and by state.
A reader should not act on a website summary alone; the binding document is the funding agreement and, where required, a court-approved transfer order.
| Item checked | What editors found | Source |
| Public fee table | 0 universal rate sheets posted on the public pages reviewed | Coin Abul editor review of Sunrise public website pages reviewed for this section |
| Downloadable sample contract | 0 sample agreements located on the public pages reviewed | Coin Abul editor review of Sunrise public website pages reviewed for this section |
| Clear statement that funding is non-recourse | 1 key claim editors looked for, because repayment structure changes legal and financial risk | Coin Abul editor checklist for lawsuit-funding reviews |
| State-by-state pricing disclosures | 0 standardized state rate tables located on the public pages reviewed | Coin Abul editor review of Sunrise public website pages reviewed for this section |
Editors also checked whether Sunrise publicly explains how charges compound, whether fees are simple or compounded, and whether there is a payment cap. Those points determine the real payoff amount.
If a site does not publish them, the contract becomes the only reliable source.
Another check was whether Sunrise explains who must approve funding. In many cases, an attorney must acknowledge the advance, and some transactions may need extra court scrutiny.
Readers should confirm the approval process with their lawyer before signing.
- Identity check: editors looked for a clear legal business name, contact information, and the states where Sunrise says it operates.
- Pricing check: editors looked for posted rates, origination fees, minimum charges, and examples showing total repayment over time.
- Contract check: editors looked for non-recourse language, cancellation rights, and any cap on repayment.
- Complaint check: editors looked for public complaint channels such as state regulators or Better Business Bureau information.
The practical takeaway is narrow. Sunrise may offer the product a plaintiff needs, but public marketing pages alone did not provide a complete price picture in the pages editors reviewed.
Ask for the full agreement, have counsel review it, and compare the total payoff amount, not only the cash advance.
Alternatives to Sunrise Lawsuit Funding
If Sunrise Lawsuit Funding is not the right fit, compare options that may cost less or avoid selling part of a future settlement.
The key tradeoff is risk: lawsuit funding is usually non-recourse, while most alternatives must be repaid even if the case loses.
That difference matters. A cheaper product can still be more dangerous if it puts wages, savings, or credit at risk. Check the contract and ask a lawyer or financial professional before using any alternative.
| Alternative | Verified figures | Why it may help | Main caution |
| Hospital or provider hardship plan | Nonprofit hospitals must make reasonable efforts to determine financial assistance eligibility before extraordinary collection actions, and generally must wait at least 120 days from the first post-discharge bill before those actions, under IRS Section 501(r) regulations. | Can reduce immediate cash pressure without borrowing against a case. | Rules apply to qualifying nonprofit hospitals, not every provider. Confirm terms in writing. |
| Federal credit union PAL I | The National Credit Union Administration says PAL I loans can range from $200 to $1,000, carry a maximum 28% APR, charge an application fee up to $20, and run 1 to 6 months. | Costs are capped and far more transparent than many emergency products. | Repayment is required even if the lawsuit produces no recovery. |
| Federal credit union PAL II | NCUA says PAL II loans can be up to $2,000, with a maximum 28% APR, an application fee up to $20, and terms of 1 to 12 months. | Higher borrowing limit than PAL I, with the same federal APR cap. | Membership rules and underwriting still apply. |
| 401(k) loan | The IRS says many plans may allow borrowing up to the lesser of $50,000 or 50% of the vested account balance. Repayment is generally within 5 years unless the loan is used to buy a principal residence. | Interest may be lower than unsecured credit. | Leaving a job can trigger fast repayment or taxes and penalties. Plan rules vary. |
Other alternatives exist, but the numbers depend on the borrower and lender. A bank personal loan, a credit-union signature loan, or a family loan may work if the repayment terms are clear and affordable.
- Ask medical providers about hardship discounts, not only payment plans.
- Check whether a local credit union offers PAL I or PAL II under NCUA rules.
- Review retirement-plan loan rules with the plan administrator before borrowing.
- Compare any required monthly payment against the possibility of no settlement recovery.
Plain caution: do not choose a recourse loan solely because its headline rate looks lower. If the case fails or settles late, a conventional loan can create collections, credit damage, taxes, or retirement losses that lawsuit funding may not.
Frequently Asked Questions
What is Sunrise Lawsuit Funding?
Sunrise Lawsuit Funding describes itself as a pre-settlement funding company that advances money to plaintiffs with pending lawsuits and expects repayment from the case proceeds if the claim succeeds, according to the company’s website.
Readers should confirm the company’s current products, states served, and contract terms directly with Sunrise Lawsuit Funding before signing because offerings can change.
Is Sunrise Lawsuit Funding the same as a regular loan?
Pre-settlement funding is commonly marketed as non-recourse, meaning repayment is typically tied to the case outcome rather than the borrower’s paycheck or credit profile.
As described by litigation-funding companies and consumer explainers from the Consumer Financial Protection Bureau.
That does not make it risk-free: fees and payoff amounts can still grow over time, so a plaintiff should review the contract and ask a lawyer to explain the repayment section before accepting funds.
What does Sunrise Lawsuit Funding usually look at before approving an advance?
Companies in this market generally focus on the strength of the legal claim, expected settlement value, available insurance coverage, and the attorney’s cooperation, rather than using a traditional consumer underwriting model.
According to industry descriptions and litigation-funding company disclosures.
A plaintiff should not rely on a generic checklist alone; the attorney handling the case should verify what Sunrise specifically requires for case review.
How much can Sunrise Lawsuit Funding cost?
The cost depends on the contract, state law, and how long the case remains unresolved, and any precise rate or fee schedule should come from Sunrise Lawsuit Funding’s written agreement, not from a generic article.
Because this is money-related legal content, the safe step is to compare the full payoff estimate at different future dates and check whether state disclosures or court rules apply before accepting an advance.