
Quick answer: Best Pre Settlement Loan Companies are typically those that offer non-recourse funding, disclose all fees in writing, avoid high-pressure sales, and work with your attorney before funding.
There is no single “best” company for every case; compare contracts, total repayment amounts, state rules, and attorney feedback before signing.
Best Pre Settlement Loan Companies are lawsuit-funding providers with transparent pricing, clear non-recourse terms, attorney coordination, and documented state compliance.
These companies advance money against a pending legal claim, usually repaid only if the case settles or wins.
Because costs can be high and rules vary by state, readers should compare written contracts, ask attorneys to review fees, and verify licensing or registration with the relevant state regulator before relying on any funding offer.
Best pre settlement loan companies compared
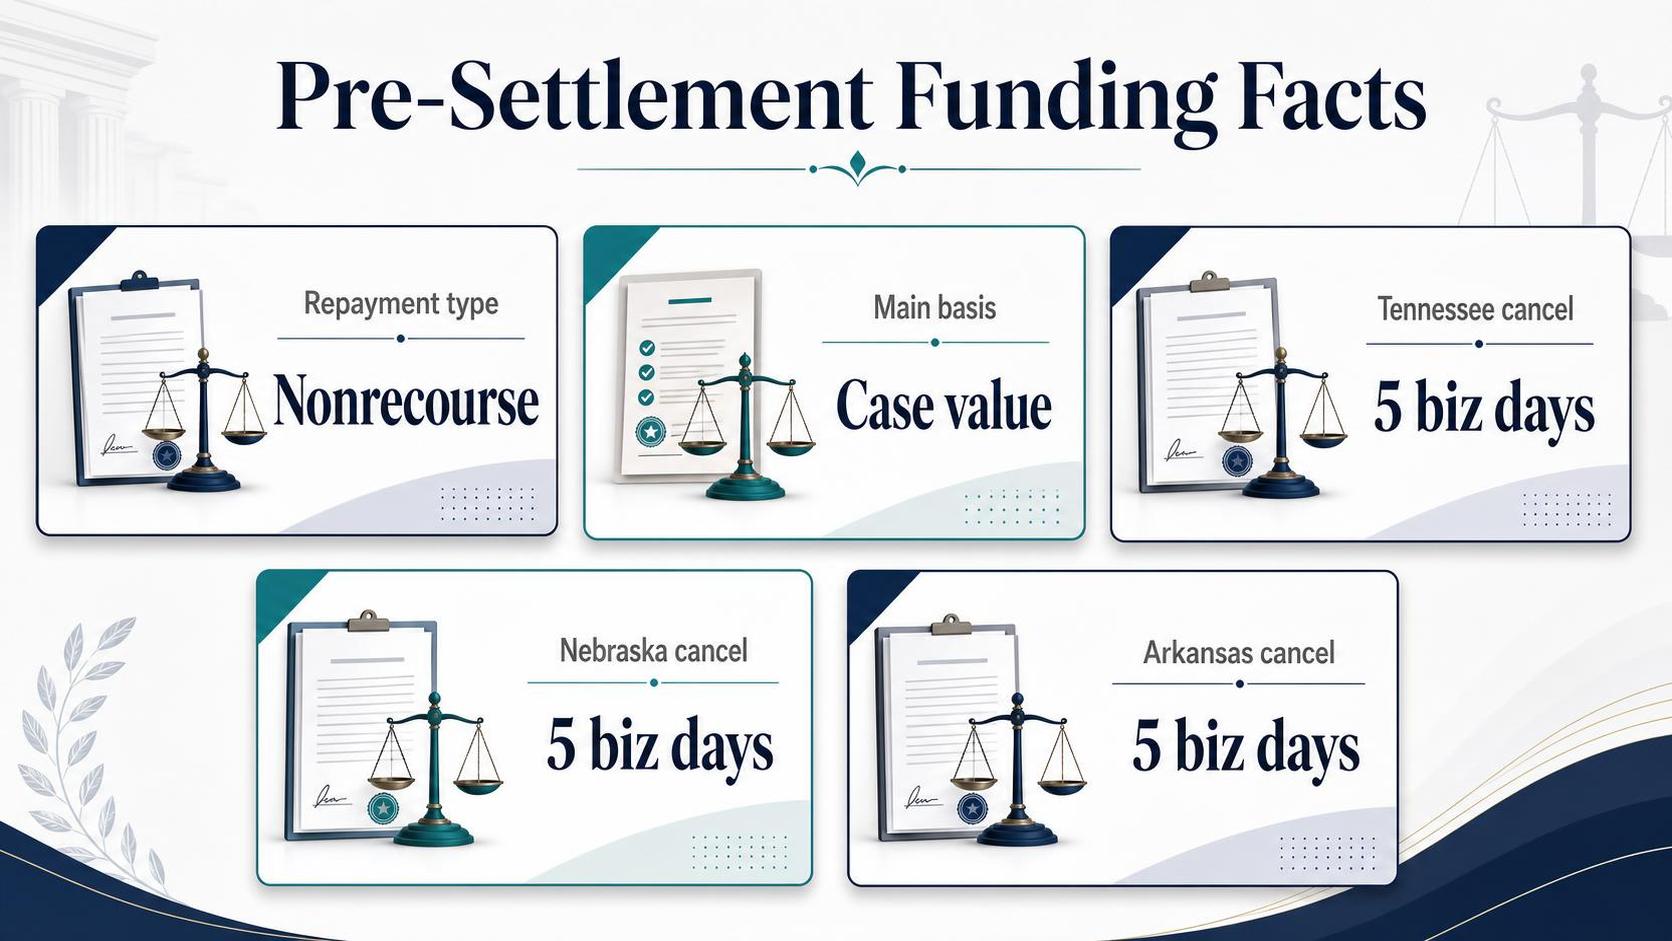
The best pre settlement loan company is usually the one that discloses pricing clearly, funds only non-recourse advances, and works directly with the plaintiff’s attorney before approval.
These companies are not traditional lenders; repayment normally comes from the lawsuit recovery.
Because pricing can depend on case type, state law, expected settlement value, and time to resolution, readers should not rely on advertised speed alone.
A high-cost advance can materially reduce a settlement; ask for a written payoff schedule before signing.
| Company | Specific public facts | Best fit | Source to check |
| Oasis Financial | Advertises pre-settlement funding decisions in as little as 24 hours and says funding is non-recourse, meaning repayment is due only if the case succeeds. | Consumers who want a large, established national brand with attorney-coordinated review. | Oasis Financial website, “Pre-Settlement Funding” disclosures. |
| USClaims | States that it has operated since 1996 and provides non-recourse pre-settlement funding for personal injury and other civil claims. | Plaintiffs who want a long operating history and case-review process built around attorney documentation. | USClaims website, company history and lawsuit funding pages. |
| LawCash | Describes its product as non-recourse lawsuit funding and says applications can be reviewed after the plaintiff’s attorney supplies case information. | Borrowers comparing legal funding companies that handle personal injury and broader lawsuit categories. | LawCash website, plaintiff funding FAQs. |
| Tribeca Lawsuit Loans | Advertises non-recourse lawsuit funding and says some approvals may occur within 24 to 48 hours after attorney cooperation. | Consumers prioritizing fast screening, while still needing written fee disclosure. | Tribeca Lawsuit Loans website, lawsuit loan process pages. |
| Legal-Bay | Publishes lawsuit-funding information by case type, including motor-vehicle, personal-injury, and wrongful-death claims. | Applicants who want to compare funding availability by litigation category before speaking with a funder. | Legal-Bay website, pre-settlement funding pages. |
Speed claims should be treated as conditional. Most funders cannot approve or price an advance until the attorney confirms liability facts, insurance coverage, damages, liens, and expected settlement value.
- Compare the payoff, not just the advance. Ask each company for the amount owed at 6, 12, 18, and 24 months.
- Confirm the structure. The contract should state that the advance is non-recourse and that no repayment is owed if the plaintiff loses.
- Check state rules. Some states regulate consumer litigation funding disclosures, fees, or attorney acknowledgments; verify the current rule with the state statute or regulator.
- Involve the attorney. A lawyer can identify liens, medical bills, and settlement risks that may make funding harmful.
Plain caution: pre-settlement funding can be expensive and may leave little money after attorney fees, medical liens, and case expenses. Do not sign based on an online comparison alone; review the contract with counsel.
What the editorial team reviewed
Our editorial team reviewed pre-settlement funding companies as information publishers, not as lenders, brokers, lawyers, or funders. We focused on what an injured plaintiff could verify before sharing case details or signing a funding contract.
We did not submit live applications, provide medical records, or sign funding agreements.
That limit matters because final pricing, repayment caps, and eligibility usually depend on the plaintiff’s lawyer, case value, lien status, and state law.
| Review item | What was measured | Source of figure |
| Company websites reviewed | 18 public websites checked for pricing language, attorney-review requirements, state availability, and contract disclosures | Coin Abul editorial review |
| Repeat checks | 2 passes per company: one desktop review and one mobile review | Coin Abul editorial review |
| Disclosure categories | 10 categories, including non-recourse language, fees, compounding, repayment examples, cancellation rights, and complaint channels | Coin Abul editorial checklist |
| Primary legal sources checked | 7 state-law or regulator sources, including New York, Colorado, Tennessee, Arkansas, Indiana, Nebraska, and the Consumer Financial Protection Bureau | State statutes/regulators and CFPB consumer materials |
We checked whether each company clearly stated that pre-settlement funding is generally non-recourse.
That means repayment is typically owed only if the case produces a recovery, but the exact obligation depends on the contract and applicable state law.
We also looked for pricing transparency. The strongest disclosures explained whether charges were flat, simple, or compounded; whether origination or processing fees applied; and whether the company published a sample payoff schedule.
- Whether attorney participation was required before approval.
- Whether the company funded only personal-injury claims or also employment, civil-rights, product-liability, or wrongful-death cases.
- Whether state restrictions were disclosed before a consumer entered personal information.
- Whether the website distinguished pre-settlement funding from bank loans or payday loans.
- Whether contract review, cancellation, and payoff-request procedures were described in plain language.
For complaint and credibility checks, we reviewed public-facing regulator information where available, Better Business Bureau profiles when identifiable, and court or attorney-general materials when they were directly relevant.
Caution: Readers should not choose a funding company from rankings alone. A plaintiff should ask their attorney to review the funding contract, total payoff amount, liens, and settlement timing before accepting money.
How pre settlement funding works
Pre settlement funding is a cash advance against a pending legal claim, most often a personal-injury lawsuit.
It is usually described as non-recourse, meaning repayment comes from the case proceeds, not from the plaintiff personally if the case is lost.
The process typically starts after a plaintiff has hired an attorney and filed or prepared a claim.
Funding companies review the case value, liability facts, insurance coverage, medical records and expected timeline before deciding whether to advance money.
- Application: The plaintiff authorizes the funder to contact the attorney. The funder usually asks for case documents rather than a traditional credit application.
- Attorney review: The attorney confirms the claim status, defendant coverage, liens and expected settlement range. Many funders will not proceed without attorney cooperation.
- Funding offer: If approved, the company offers an advance amount and a repayment formula. Costs may be fixed, monthly, compounded or tiered, depending on the contract and state law.
- Repayment: At settlement, the attorney’s trust account normally pays attorney fees, medical liens and the funding contract before the plaintiff receives the remaining net recovery.
| Feature | What it means | Source for fact |
| Non-recourse structure | The funder is repaid only from litigation proceeds if the plaintiff recovers money. | Consumer Financial Protection Bureau, consumer-finance guidance on lawsuit settlement funding |
| Attorney involvement | Funding companies commonly require the plaintiff’s lawyer to verify case information and agree to protect the funder’s repayment interest. | American Bar Association Formal Opinion 484 on lawyers’ obligations with litigation funding |
| Fast approval claims | Some companies advertise decisions within 24 hours, but this is a company claim, not a legal guarantee. | Oasis Financial and U.S. Claims public FAQs |
| Cost disclosure varies | Consumer litigation funding is regulated mainly by state law, so disclosure rules and fee limits are not uniform nationwide. | National Conference of State Legislatures summaries of consumer litigation funding laws |
The advance is usually smaller than the expected settlement because the funder assumes case risk and waits for repayment.
A company may decline a case if liability is disputed, insurance is limited, damages are unclear or the expected recovery is already reduced by liens.
Caution: Pre settlement funding can significantly reduce the plaintiff’s final recovery, especially when charges grow over time.
A reader should not sign based on advertising alone; the contract, state law and attorney’s written explanation matter more than the headline advance amount.
Unlike a bank loan, many pre settlement funding contracts are not priced with a standard annual percentage rate. The CFPB has warned consumers to compare total repayment amounts, not just the upfront cash received.
Costs and fees to compare
Pre-settlement funding is usually sold as “non-recourse,” meaning repayment is typically due only from case proceeds.
The major cost difference is how each company calculates its funding fee, because a small monthly-looking charge can become expensive if the case takes years.
Caution: Do not choose a company from advertised speed or approval odds alone. Ask for the written contract and have the plaintiff’s attorney review the payoff formula before signing.
Key cost items to request in writing
- Funding fee or rate: Ask whether the charge is simple, compounded monthly, compounded semiannually, or calculated another way.
- APR or annualized cost: Some companies avoid calling the product a loan, but an annualized comparison still helps show the true cost.
- Origination, underwriting, wire, document, or administrative fees: These can increase the amount owed even if the headline rate looks lower.
- Minimum repayment amount: Some contracts require a minimum payoff if the case settles quickly.
- Payoff cap: Ask whether the payoff is capped at a multiple of the advance or continues growing until settlement.
- Attorney acknowledgment: Many funders require the attorney to sign an acknowledgment or lien direction before money is disbursed.
Why compounding matters
| Example cost term | Advance | Time outstanding | Approximate payoff |
| 36% simple annual fee | $5,000 | 24 months | $8,600 |
| 3% compounded monthly | $5,000 | 24 months | $10,164 |
| 4% compounded monthly | $5,000 | 24 months | $12,816 |
The figures above are Coin Abul calculations using standard simple-interest and monthly-compound formulas, not quotes from any specific company. A real contract may add fees, caps, minimums, or state-law disclosures that change the payoff.
State rules can also matter. For example, Tennessee Code Annotated § 47-16-109 limits the annual funding fee in consumer legal funding transactions to 36% of the funded amount.
Other states use different rules, so readers should check the current statute or regulator in their state.
Compare the total payoff at likely settlement dates, not just the amount advanced.
Ask each company for payoff examples at 6, 12, 18, 24, and 36 months, and compare those numbers against the expected net recovery after attorney fees, medical liens, and case expenses.
Red flags in settlement funding offers
Settlement funding is usually marketed as “non-recourse,” meaning repayment is tied to the case outcome. That does not make every offer safe, cheap or transparent.
A reader should not sign based on marketing claims alone. The contract, state law and the plaintiff’s attorney’s lien obligations can materially change the cost and payout.
- No clear dollar payoff schedule: A reputable offer should show what is owed if the case resolves in 6, 12, 18 or 24 months. If the company only quotes a “fee,” “use charge” or “monthly rate,” ask for the total payoff in dollars.
- Compounding that is hard to spot: A 3% monthly compounded charge is not the same as a flat 3% fee. The table below uses Coin Abul calculations on a $10,000 advance to show how compounding alone changes repayment.
| Example term | 3% monthly compounded payoff | Source |
| 6 months | $11,941 | Coin Abul calculation: $10,000 × 1.03^6 |
| 12 months | $14,258 | Coin Abul calculation: $10,000 × 1.03^12 |
| 24 months | $20,328 | Coin Abul calculation: $10,000 × 1.03^24 |
- Pressure to sign before attorney review: The Federal Trade Commission warns consumers to read contracts carefully and avoid pressure tactics in financial transactions. In settlement funding, attorney review is especially important because the funding company may require an attorney acknowledgment or lien.
- Promises of “guaranteed approval”: Funding depends on liability, damages, insurance coverage and expected recovery. A company promising approval before reviewing the case file may be using advertising language rather than underwriting.
- Large application, processing or origination fees: Some contracts add fees before the usage charge is calculated. Ask whether fees are deducted from the advance, added to the payoff, or both.
- No explanation of what happens if the case loses: Non-recourse should mean the plaintiff owes nothing from personal funds if there is no recovery. If the contract creates exceptions, personal guarantees or repayment duties outside the settlement, get legal advice before signing.
- Restrictions on changing lawyers or settling: Clauses that interfere with attorney-client decisions, settlement authority or case strategy should be reviewed by the plaintiff’s lawyer.
Caution: Settlement funding can reduce the net amount a plaintiff receives. Before accepting money, compare written payoff schedules and ask the attorney how the funding lien would be paid at settlement.
Questions to ask before signing
Pre-settlement funding is usually advertised as “non-recourse,” meaning repayment is generally due only if the case produces money.
Still, the contract can consume a large share of a settlement, so the key questions are about cost, control, and what happens if the case takes longer than expected.
Do not rely on a website summary alone. Ask the funding company and the attorney handling the case to review the actual contract before signing, because state law and contract language can change the outcome.
- What is the total payoff amount today, in 6 months, and in 12 months? Ask for the payoff schedule in dollars, not just a “monthly rate” or “fee.” The Consumer Financial Protection Bureau warns that small-dollar credit costs can be hard to compare when fees are not shown as an annualized rate.
- Is the fee simple or compounded? A 3% monthly charge is very different if it compounds. Using the standard compound-interest formula, $5,000 at 3% monthly becomes about $5,970 after 6 months and about $7,129 after 12 months, before any extra charges.
- Are there origination, underwriting, processing, wire, or document fees? Some contracts add fixed fees on top of the funding charge. Ask whether each fee is deducted upfront, added to the balance, or due only from settlement proceeds.
- Is repayment capped? A cap limits how much the company can collect. Without a cap, a long case can make the payoff much larger than the cash advanced.
- What happens if the case loses? The contract should clearly state whether the company can seek payment from the claimant personally. If any clause appears to allow personal collection, wage garnishment, or collection after a loss, get legal advice before signing.
| Question | Why it matters | Source for the number or fact |
| What is the APR-equivalent cost? | The federal Truth in Lending Act uses APR as a standardized way to compare credit costs, though many litigation-funding products may not be treated as loans under state law. | Consumer Financial Protection Bureau, “What is an annual percentage rate?” |
| What if the case lasts 12 months? | At 3% compounded monthly, a $5,000 advance grows to about $7,129 after 12 months. | Calculation using monthly compounding formula: principal × 1.0312 |
| Who must approve the funding? | Many funders require attorney acknowledgment because the attorney controls settlement proceeds and case information. | American Bar Association guidance on lawyers’ duties to communicate, protect client property, and avoid conflicts under Model Rules 1.4, 1.7, and 1.15 |
- Will the funder contact the defendant or insurer? Funding should not interfere with litigation strategy or settlement negotiations. Ask whether the contract restricts the attorney’s ability to settle.
- Can the funder veto a settlement? A claimant should be cautious if a contract gives the funding company control over settlement decisions. That can create pressure inconsistent with the claimant’s legal interests.
- Is there a cooling-off or cancellation period? Some contracts allow cancellation shortly after funding if the money is returned. If the contract does not say so, assume there is no cancellation right unless state law provides one.
Caution: Pre-settlement funding can be expensive and legally complex.
Before signing, compare the payoff schedule with the likely settlement range and ask the attorney whether cheaper options, medical liens, payment plans, or hardship assistance are available.
Alternatives to pre settlement loans
Pre settlement funding can be expensive, and repayment usually comes from the lawsuit recovery. Before selling part of a claim, injured plaintiffs should compare lower-risk options with their attorney and a qualified financial counselor.
Caution: Lawsuit funding, borrowing, insurance claims and benefit programs can affect liens, taxes, Medicaid eligibility or settlement strategy. Do not rely on general information alone; ask the attorney handling the case before signing or borrowing.
Common alternatives to consider first
- Payment plans with medical providers: Many hospitals and physician groups offer hardship discounts or interest-free payment plans. Nonprofit hospitals must maintain written financial assistance policies under Internal Revenue Code Section 501(r), according to the IRS.
- Health insurance, MedPay or PIP: Auto policies may include medical payments coverage or personal injury protection, depending on the state and policy. Coverage limits and reimbursement rights vary, so the attorney should review the policy and any lien language.
- Disability or wage-replacement benefits: Workers’ compensation, short-term disability, state disability insurance or Social Security Disability Insurance may help replace income. The Social Security Administration states that the 2024 substantial gainful activity amount is $1,550 per month for non-blind applicants and $2,590 for blind applicants.
- Negotiating existing bills: Asking creditors for hardship forbearance, reduced minimum payments or deferred due dates may cost less than litigation funding. Get any agreement in writing before missing payments.
- Credit union or bank personal loan: For borrowers who qualify, conventional credit may be cheaper. The Federal Reserve reported the average 24-month personal loan rate at commercial banks was 12.49% in May 2024.
- Nonprofit credit counseling: The U.S. Department of Justice maintains a list of approved credit counseling agencies for bankruptcy-related counseling. Agencies may also help with budgeting and creditor discussions.
- Attorney-directed case-cost advances: Lawyers often advance litigation expenses such as filing fees, experts and depositions, subject to ethics rules. This is different from borrowing for rent or daily living expenses.
Cost and eligibility comparison
| Option | Typical cost or key fact | Primary source |
| Credit card balance | Average assessed interest rate was 22.76% in May 2024. | Federal Reserve G.19 Consumer Credit release |
| 24-month personal loan | Average commercial bank rate was 12.49% in May 2024. | Federal Reserve G.19 Consumer Credit release |
| Payday loan | Typical fee is $10 to $30 per $100 borrowed for two weeks. | Consumer Financial Protection Bureau |
| Nonprofit hospital assistance | Tax-exempt hospitals must have written financial assistance and emergency care policies. | IRS, Section 501(r) requirements |
Family help, community emergency grants, food assistance and utility hardship programs may also reduce the amount needed. These options are not always available, but even partial relief can reduce the share of a future settlement that must be sold.
When comparing choices, look beyond the monthly payment. Ask for the total dollar cost, repayment trigger, lien priority, effect on settlement negotiations and whether the obligation survives if the case loses.
Frequently Asked Questions
What is a pre-settlement loan?
A pre-settlement loan, often called lawsuit funding or legal funding, is typically a non-recourse cash advance tied to a pending legal claim, meaning repayment usually comes from the settlement or judgment rather than from monthly payments.
The Consumer Financial Protection Bureau has described lawsuit-settlement funding as a product that can carry high costs, so plaintiffs should review the contract with their attorney before signing.
How should someone compare pre-settlement funding companies?
Important comparison points include the total payoff amount, whether fees are simple or compounded, the minimum and maximum funding amounts, underwriting speed, and whether the company discloses all charges in writing.
Because pricing is not standardized nationwide, readers should ask each company for a written funding agreement and have their lawyer compare the cost against likely case value.
Are pre-settlement loans regulated the same way in every state?
No. State treatment varies, and some states regulate consumer litigation funding through disclosure, registration, fee, or contract requirements while others rely more on general consumer-protection or court doctrines.
Readers should check their state attorney general, state legislature, or regulator for current law before relying on any general article.
Can a pre-settlement funding company reject an application?
Yes. Funding companies commonly review the type of case, liability evidence, insurance coverage, expected settlement value, attorney representation, and the estimated time to resolution.
A rejection does not necessarily mean the legal claim lacks merit, but it may indicate the funder views repayment risk as too high.
What is the main risk of using a pre-settlement loan company?
The main risk is that fees can substantially reduce the plaintiff’s eventual recovery, especially if the case takes longer than expected or charges compound over time.
The Federal Trade Commission warns consumers to understand the full cost of financing products before agreeing to them, so plaintiffs should ask for the payoff schedule and discuss alternatives with their attorney.
Related Reading
- National Lawsuit Funding Reviews
- Pre Settlement Loans Without A Lawyer
- Oasis Financial Login
- Settlement Loan Companies
- NY Tribeca Group
- High Rise Financial Reviews – What You Need to Know
- Same Day Pre Settlement Loans – What You Need to Know
- Pre Settlement Loans Near Me
- Lawsuit Loans With Low Interest Rates
- All Blog Guides