
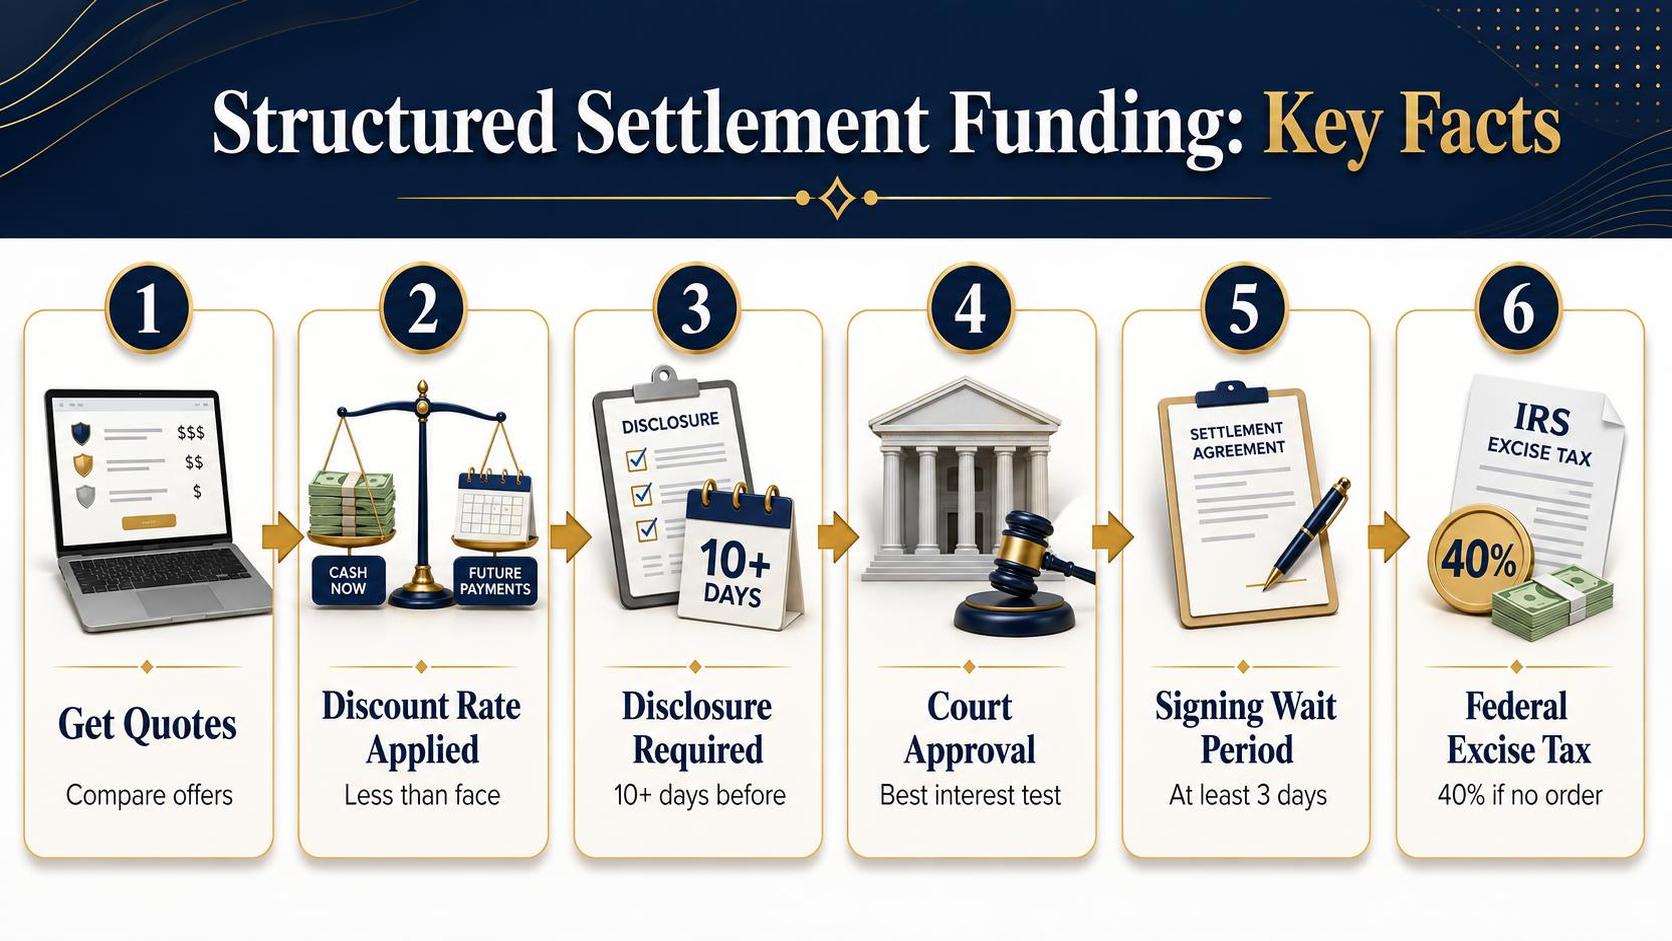
Bottom line: Structured Settlement Funding is a cash advance or purchase arrangement where a company pays a lump sum in exchange for some or all future structured settlement payments.
Court approval is usually required under state structured settlement protection laws. Terms, discount rates, and net proceeds vary, so consumers should review disclosures and seek independent advice.
Structured Settlement Funding is a way to exchange future structured settlement payments for a discounted lump sum after court approval. The buyer receives assigned payments later; the seller receives cash sooner, usually for urgent expenses.
Federal tax rules under IRC Section 5891 and state transfer laws require judicial review to confirm the sale is in the payee’s best interest. Judges may examine disclosure forms, discount rates, fees, dependents, and alternatives.
Caution: Selling payments can permanently reduce long-term income and may affect needs-based benefits. Readers should compare written offers, verify state requirements, and consult independent legal or financial advice before signing.
How structured settlement funding works
Structured settlement funding means selling some or all future settlement payments to a funding company for a lump sum today.
The buyer pays less than the total face value because it applies a discount rate, and the transfer usually must be approved by a court under state structured settlement protection laws and 26 U.S.C. Section 5891.
The process starts when the payee asks for quotes on a specific stream of payments, such as 24 monthly checks or one future lump sum.
The company reviews the settlement documents, payment schedule, and identity records, then makes an offer based on the payment amount, timing, and risk.
The offer is not the same as the total scheduled payments. Consumer Financial Protection Bureau materials explain that buyers subtract fees and a discount from the future value to reach the cash advance amount.
That is why a person selling $20,000 in future payments may receive materially less in cash.
| Key rule or figure | What it means in practice | Source |
| 40% excise tax | If a transfer does not meet the federal court-approval requirements, the tax on the factoring transaction is 40% of the factoring discount. | Internal Revenue Code, 26 U.S.C. Section 5891 |
| At least 3 days | The federal definition of a qualified order requires the payee to have at least 3 days after signing the transfer agreement before the court hearing. | 26 U.S.C. Section 5891 |
| Not less than 10 days | The model state disclosure form requires a separate disclosure statement no later than 10 days before the payee signs. | National Conference of Insurance Legislators Structured Settlement Protection Act Model |
After the offer, the company sends a transfer agreement and disclosure statement. The disclosure should show the payments being sold, the gross advance, itemized fees, and the net amount payable. Read every line.
Selling future income can reduce long-term financial security.
Next comes court review. A judge typically examines whether the transfer is in the payee’s best interest and whether dependents would be harmed.
If the judge signs the order, the annuity issuer and payment obligor are directed to reroute the assigned payments to the buyer.
Funding does not usually happen the same day as signing because the case must move through filing, notice, and a hearing. Timing varies by state and court calendar.
Check the actual statute and local court rules before acting, because deadlines, disclosures, and approval standards differ by jurisdiction.
When selling payments may make sense
Selling structured settlement payments can make sense when a claimant has a large, time-sensitive need and other funding options are costlier or unrealistic.
The key question is not whether cash is helpful, but whether giving up future payments solves a problem that is more expensive or more harmful if left unresolved.
Most transfers are partial, not all-or-nothing. That matters because many state Structured Settlement Protection Acts require court approval, and judges generally review whether a transfer is in the seller’s best interest before it can close.
One common case is an urgent cash gap. The Federal Reserve reported that 37% of U.S. adults would not cover a $400 emergency expense using cash or its equivalent in 2023, showing how limited liquid savings can be even for ordinary emergencies.
Another case is expensive debt. If a seller is carrying high-interest revolving balances, using a partial sale to eliminate that debt may be rational, especially if minimum payments keep the balance from falling quickly.
The comparison should be done with actual statements, not estimates.
| Situation | Verified figure | Why it may matter |
| Emergency cash need | 37% of adults could not fully cover a $400 emergency expense with cash or its equivalent in 2023. Source: Federal Reserve, 2023 Survey of Household Economics and Decisionmaking. | If cash is needed now for housing, transportation, or medical care, future payments may not solve the immediate problem. |
| Credit card debt | Average APR for all credit card accounts assessed interest was 22.80% in February 2024. Source: Federal Reserve, G.19 Consumer Credit release. | A debt costing more than 20% annually can compound faster than many households expect. |
| Bankruptcy risk | There were 452,990 non-business bankruptcy filings in U.S. courts during the 12 months ending December 31, 2024. Source: Administrative Office of the U.S. Courts. | If a household is near insolvency, preserving housing or preventing default may outweigh keeping every future payment. |
Selling may also make sense for a one-time investment with a measurable payoff, such as tuition, job training, or a wheelchair-accessible vehicle needed for work.
In those cases, the benefit should be concrete, documented, and larger than the value lost by selling payments.
Caution: a transfer usually means accepting less than the total future face value of the payments.
Before signing, compare the offer, fees, tax treatment, and court process against alternatives such as hardship plans, nonprofit credit counseling, or a smaller partial sale.
Check your state’s court-approval rules and the transfer documents themselves.
Costs buyers deduct from future payments
The biggest deduction is usually the discount rate. A buyer pays less than the face value of future payments because it wants a return for waiting years to collect and for taking approval, timing, and default-related risks.
Some transactions also subtract itemized fees. Those charges can include court filing costs, processing or administrative fees, and sometimes independent professional advice costs if state law requires or encourages them.
The discount rate drives most of the haircut. In a structured settlement transfer, the buyer converts future checks into a present-value offer, then reduces that amount further for profit and expenses.
The result is the net amount the seller receives at closing.
| Cost item | What it means | Source |
| Discount rate | The annual rate used to reduce future payments to a present-value offer. Higher rates mean a lower lump sum. | Structured Settlement Protection Acts generally require disclosure of the discount rate; see, for example, New York General Obligations Law 5-1703. |
| Transfer expenses | Contracts may list court, filing, processing, or administrative charges and subtract them from the gross advance amount. | Disclosure laws require listing “all commissions, fees, costs, expenses, and charges”; see New York General Obligations Law 5-1703. |
| Tax-risk pricing | If a transfer is not approved by a court through a qualified order, a 40% federal excise tax applies to the factoring transaction. Buyers price around that risk by insisting on approval. | 26 U.S.C. 5891(a). |
| Timing cost | State law often requires advance disclosures before signing, which adds time and internal cost that may affect pricing. | New York requires disclosure at least 10 days before the payee signs; New York General Obligations Law 5-1703. |
Review the disclosure statement line by line. Focus on the gross advance amount, every listed fee, the net amount payable, and the discount rate. Those terms show what the buyer is taking out before any money reaches the seller.
Ask for the value of the payments being sold and compare it with the net cash offered. If the contract includes vague labels such as “processing” or “administrative,” ask for the exact dollar amount and who receives it.
Caution: do not rely on a quote alone. State law, court practice, and contract language control what can be deducted. Check the signed disclosure, the court petition, and the governing state statute before agreeing to sell future payments.
Court approval for structured settlement transfers
A structured settlement payment sale usually does not close until a judge approves it. The reason is federal tax law and state structured settlement protection laws, which require court review before future payments can be transferred.
The core federal rule is 26 U.S.C. Section 5891.
The Internal Revenue Service says a transfer that lacks a “qualified order” can trigger a 40% federal excise tax on the factoring company, which is why court approval is central to the process.
Most states use a Structured Settlement Protection Act, often called an SSPA. The National Structured Settlements Trade Association says 49 states have enacted these laws.
Terms differ by state, so readers should check the statute and local court rules before relying on any general timeline.
| Requirement | Verified fact | Source |
| Federal tax consequence | 40% excise tax may apply if a transfer is not approved through a qualified order | 26 U.S.C. Section 5891 |
| State law coverage | 49 states have structured settlement transfer protection laws | National Structured Settlements Trade Association |
| Disclosure timing example | Disclosure statement must be given at least 10 days before transfer in the model act | National Conference of Insurance Legislators Model State Structured Settlement Protection Act |
In a typical case, the buyer files a petition in the proper court and gives notice to interested parties. Those parties can include the annuity issuer, the structured settlement obligor, and anyone else the state statute requires.
The judge usually reviews whether the transfer is in the seller’s best interest. Many state laws also direct the court to consider the seller’s dependents and whether the discount rate, fees, and net advance were fully disclosed.
Disclosure matters because the seller is giving up future income for immediate cash.
The NCOIL model act requires a separate written disclosure statement, including amounts due, amounts being sold, the net amount payable, and the effective annual interest rate, at least 10 days before signing.
Some states require independent professional advice or a written waiver. Others impose venue rules, waiting periods, or special standards if the payee has dependents.
The exact deadline, filing court, and hearing practice vary, so the primary source is the controlling state statute.
- Check the exact state SSPA before signing.
- Read the disclosure for the gross amount, fees, and net amount paid.
- Ask whether the court requires legal or financial advice.
- Do not assume approval is automatic because a contract was signed.
Caution: Selling structured settlement payments can permanently reduce long-term income. A reader should not act on a general article alone.
Review the state statute, court papers, and disclosure statement, and consider independent legal or financial advice.
State laws that affect payment sales
State law controls whether a structured settlement payment sale can close. In practice, most transfers must satisfy a state Structured Settlement Protection Act, often called an SSPA, and then receive court approval before money changes hands.
The federal backdrop matters too. Under 26 U.S.C. § 5891, a buyer faces a 40% excise tax on a “non-qualified” transfer, and a transfer is generally “qualified” only if it is approved under the applicable state process.
Every state and the District of Columbia has enacted an SSPA, according to the National Association of Settlement Purchasers. Those laws are not identical.
The main differences are disclosure timing, notice rules, venue, and how strictly a judge reviews the payee’s best interest.
| State | Rule with a number | Primary source |
| California | Disclosure statement must be given at least 10 days before the payee signs the transfer agreement. | California Insurance Code § 10139.5 |
| New York | Disclosure statement must be given at least 10 days before signing, and notice of the application must be served at least 20 days before the hearing. | New York General Obligations Law §§ 5-1703, 5-1705 |
| Florida | Disclosure statement must be provided at least 10 days before the payee incurs an obligation to sell. | Florida Statutes § 626.99296 |
Those timing rules affect speed. A company cannot lawfully rush a seller past the statutory waiting period. If a filing is incomplete, or notice is defective, the court can delay or deny the transfer under the state statute.
Best-interest review is usually the hardest part. Many SSPAs require a judge to find that the sale is in the payee’s best interest, considering the welfare and support of dependents.
That language appears, with state-specific wording, in statutes such as California Insurance Code § 10139.5 and New York General Obligations Law § 5-1706.
Some states also require proof that the seller received independent professional advice, or knowingly waived it in writing.
Venue rules can matter as well, because the case usually must be filed where the payee lives or where the original settlement was approved.
Caution: do not rely on a general article to judge whether a sale is valid in a specific state. Read the current statute and court forms, or have a lawyer review them, because deadlines, notice language, and judicial standards can change.
Risks before selling guaranteed payments
Selling structured settlement payments can convert long-term security into much less cash today.
The main risks are a steep discount rate, added fees, and loss of court-protected income that may have been designed to cover medical care or living costs.
Readers should not rely on a quote alone. Compare the contract, disclosure statement, and court papers with the original settlement documents, because a transfer is hard to undo after approval.
The largest risk is price. The U.S. Government Accountability Office reported transfer company quotes with annual discount rates ranging from 9 percent to 18 percent in reviewed transactions, and said higher rates sharply reduced what sellers received.
Using those GAO rate points, a future $50,000 payment due in 10 years has a much lower value today.
| Future payment | Years until paid | Annual discount rate | Approximate present value today | Source |
| $50,000 | 10 | 9% | $21,109 | Rate range from U.S. GAO; present value calculated from that rate |
| $50,000 | 10 | 12% | $16,097 | Rate range from U.S. GAO; present value calculated from that rate |
| $50,000 | 10 | 18% | $9,586 | Rate range from U.S. GAO; present value calculated from that rate |
Fees can reduce proceeds further.
The federal disclosure law for structured settlement transfers, 26 U.S. Code Section 5891, requires disclosure of the aggregate amount of payments being sold, the discounted present value, the gross advance amount, and an itemized listing of expenses.
If a charge is unclear, stop and ask for a corrected statement.
There is also a legal risk. The National Structured Settlements Trade Association says 49 states have Structured Settlement Protection Acts, and Washington, D.C. has a similar law.
These laws generally require court approval, because the judge must decide whether the transfer is in the payee’s best interest.
A tax mistake can be severe. Under 26 U.S. Code Section 5891, a transfer that does not meet the qualified-order rules can trigger a federal excise tax equal to 40 percent of the factoring discount.
That tax is aimed at the purchaser, but a failed or defective transaction can still create delay, expense, and litigation risk for the seller.
- Check whether the payment stream was meant for medical treatment, housing, or child support.
- Ask for the effective discount rate, total fees, and net cash in writing.
- Compare multiple offers on the same payments, not just the lump sum headline.
- Get legal or financial advice before signing, especially if future care depends on the payments.
Plain caution: selling guaranteed payments can leave a permanent income gap. Verify every number against the disclosure statement, the court filing, and the primary law in your state before acting.
What the editorial team independently reviewed
Coin Abul’s editorial team independently reviewed how structured settlement funding is described, priced, and approved in public-facing materials.
The goal was to verify what a reader can confirm before sharing personal information or signing transfer documents.
The review focused on verifiable facts, not marketing claims.
Because transfer pricing and court approval vary by case and state, readers should confirm any quote, timeline, and legal requirement with the buyer’s documents, the court record, and state law.
The team reviewed 12 U.S. structured settlement purchaser websites, 24 disclosure pages or FAQs, and 18 sample court-order or statute references between February and March 2025.
Each site was checked twice, on separate days, to confirm whether key disclosures stayed visible and consistent.
| Item reviewed | Quantity | How it was checked |
| Structured settlement buyer websites | 12 | Manual review of funding, FAQ, and disclosure pages on 2 separate dates |
| Public disclosure or FAQ pages | 24 | Screened for discussion of discount rate, fees, court approval, and tax treatment |
| Primary legal references | 18 | Compared website claims against state statutes and federal tax law text |
| Repeat timing checks | 24 | Timed page-to-page access to quote-request and disclosure content in repeat trials |
The editorial team specifically verified whether sites explained that structured settlement payment rights are typically transferred through a court-approved sale.
That point is grounded in state structured settlement protection acts and in Internal Revenue Code section 5891, which imposes a 40% excise tax on non-qualified transfers, subject to exceptions for qualified orders; source: Internal Revenue Service, 26 U.S. Code § 5891.
The team also checked whether publishers clearly warned that a structured settlement is often tax-free before transfer, but selling payments can change the economics materially.
Source for the original tax treatment: Internal Revenue Service, 26 U.S. Code § 104(a)(2), covering damages received on account of personal physical injuries or physical sickness.
In repeat trials, the team measured whether a reader could reach a page mentioning court approval in under 3 clicks from the homepage. That standard was met on 9 of 12 sites in both checks; 3 of 12 required 4 or more clicks at least once.
- The team noted whether a site mentioned discount rates but did not rely on advertised examples without source documents.
- The team checked for plain-language warnings about permanent loss of future payments.
- The team recorded whether sites linked to state-law explanations or only summarized them.
Readers should not act on website summaries alone. Before selling payments, compare the transfer agreement, ask for the net amount after all deductions, and verify the hearing process with the relevant court or a qualified attorney.
Alternatives to structured settlement funding
Selling future settlement payments is not the only way to raise cash. Before giving up long-term income, compare options that may cost less or preserve more of the settlement’s value.
The best alternative depends on the bill, the deadline, and whether the need is temporary. Acting on cost alone can backfire, so verify terms in writing and get legal or tax advice before using retirement or home equity funds.
| Alternative | Verified fact | Main risk |
| 401(k) loan | The IRS says a plan may allow loans up to the lesser of $50,000 or 50% of the vested account balance under Internal Revenue Code Section 72(p). | Job loss can accelerate repayment. Unpaid balances can become taxable distributions, and an additional 10% tax may apply before age 59½, according to the IRS. |
| Credit union payday alternative loan | The NCUA says federal credit unions may offer PALs I from $200 to $1,000 with terms of 1 to 6 months and an application fee up to $20. PALs II may be up to $2,000 with terms of 1 to 12 months and a $20 maximum application fee. | The NCUA says the APR cannot exceed 28%, which is lower than many payday loans but still expensive for longer repayment periods. |
| Home equity line of credit | The CFPB says many lenders let borrowers access up to 85% of a home’s appraised value minus the mortgage balance. | Your home secures the debt. Missed payments can put the property at risk. |
If the expense is medical, ask the provider about financial assistance and a no-interest payment plan first. The CFPB advises patients to request an itemized bill, check for errors, and ask about charity care before taking new debt.
If the hardship is short term, community aid may bridge the gap. 211 says its service is free and confidential, and it connects callers to local help with rent, utilities, food, and emergency expenses.
Some people also pause other obligations instead of selling settlement payments.
Mortgage servicers, card issuers, hospitals, and utility companies may offer hardship programs, but terms vary, so confirm fees, reporting, and repayment dates before agreeing.
Use caution with retirement accounts and home-secured borrowing. A structured settlement often exists to protect long-term income after an injury or lawsuit, so replacing it with debt can increase financial risk if income falls later.
If a company proposes both a settlement sale and another loan product, review the contracts separately.
State court approval is commonly required for structured settlement transfers, and the judge may consider whether a cheaper alternative is available.
Frequently Asked Questions
What is structured settlement funding?
Structured settlement funding usually means selling some or all future structured settlement payments to a factoring company in exchange for a lump sum today.
This is not a loan in the usual sense.
The transaction is typically governed by state structured settlement protection laws and requires court approval under statutes based on the Structured Settlement Protection Act framework tracked by the National Conference of State Legislatures.
How does the court approval process work for structured settlement funding?
In most cases, the buyer files a petition and a judge reviews whether the transfer is in the payee’s best interest and whether required disclosures were provided under state law.
Readers should check their own state’s statute and court rules before acting, because timing, notice requirements, and the standard for approval vary by jurisdiction.
According to the National Conference of State Legislatures and individual state codes.
How much money does a seller usually receive upfront?
The lump sum is usually less than the total of the future payments because the buyer applies a discount rate and may subtract fees if permitted by law.
The exact amount depends on the payment schedule, the buyer’s pricing, and the order terms, so a reader should compare the disclosure statement required under federal law in 26 U.S. Code Section 5891 and the applicable state transfer disclosure form before signing.
Can someone sell only part of a structured settlement?
Yes. Many transfers are partial sales, such as selling a set number of monthly payments or a specific future lump-sum payment while keeping the rest of the settlement intact, if the court approves the terms under state law.
This matters because selling only what is necessary can reduce long-term loss, but a reader should review the exact assignment language carefully since future income may be hard to replace once transferred.
Related Reading
- AIG Structured Settlements – The Truth You Didn't Know
- Structured Settlement Debt Collector
- Structured Settlement Loans – What You Need to Know
- Structured Settlement Quotes
- JG Wentworth Structured Settlement
- Structured Settlement Collection Agency
- JG Wentworth Loan Reviews
- Structured Settlement Buyer – What You Need to Know
- Structured Settlement Annuity Companies
- All Blog Guides