Bottom line: Pre Settlement Funding California is non-recourse cash advanced to plaintiffs before a lawsuit settles, usually repaid only from the case recovery.
California regulates consumer legal funding through disclosure and contract rules, and costs can be high. Compare funders, ask your attorney to review terms, and do not rely on funding advice alone.
Pre Settlement Funding California is nonrecourse cash advanced against a pending legal claim, repaid from a future settlement only if the case succeeds.
In California, providers typically review attorney-confirmed case facts, expected liability, damages, insurance coverage, and estimated timeline before pricing the advance.
This topic matters because costs can compound and reduce the final recovery. California borrowers should compare contracts, ask counsel to review fees, and verify licensing or registration claims with primary state sources. Do not rely on article summaries as legal or financial advice.
How California pre settlement funding works
Pre-settlement funding in California provides plaintiffs a cash advance against the expected proceeds of a pending lawsuit. The transaction is structured as a non-recourse agreement, meaning the applicant owes nothing if the case loses.
California does not classify pre-settlement funding as a “loan” under most circumstances. The California Supreme Court addressed this in Bohannan v.
Advance Fund LLC (2024), and the state legislature has considered regulatory bills, but as of 2025 no comprehensive statute specifically governs lawsuit funding rates or fees statewide.
Readers should verify the current regulatory status through the California Department of Financial Protection and Innovation (DFPI).
Step-by-step process
- Application: The plaintiff submits case details — typically the complaint, police reports (in injury cases), and attorney contact information.
- Attorney cooperation: The funding company contacts the plaintiff’s attorney to evaluate case merits and estimated settlement value.
- Underwriting: Approval is based on case strength, not the applicant’s credit score, employment, or income.
- Contract execution: The plaintiff signs a funding agreement disclosing the funded amount, fee structure, and total repayment obligation.
- Disbursement: Funds are typically delivered within 24–72 hours of approval, according to industry sources such as the American Legal Finance Association (ALFA).
Typical fee structures
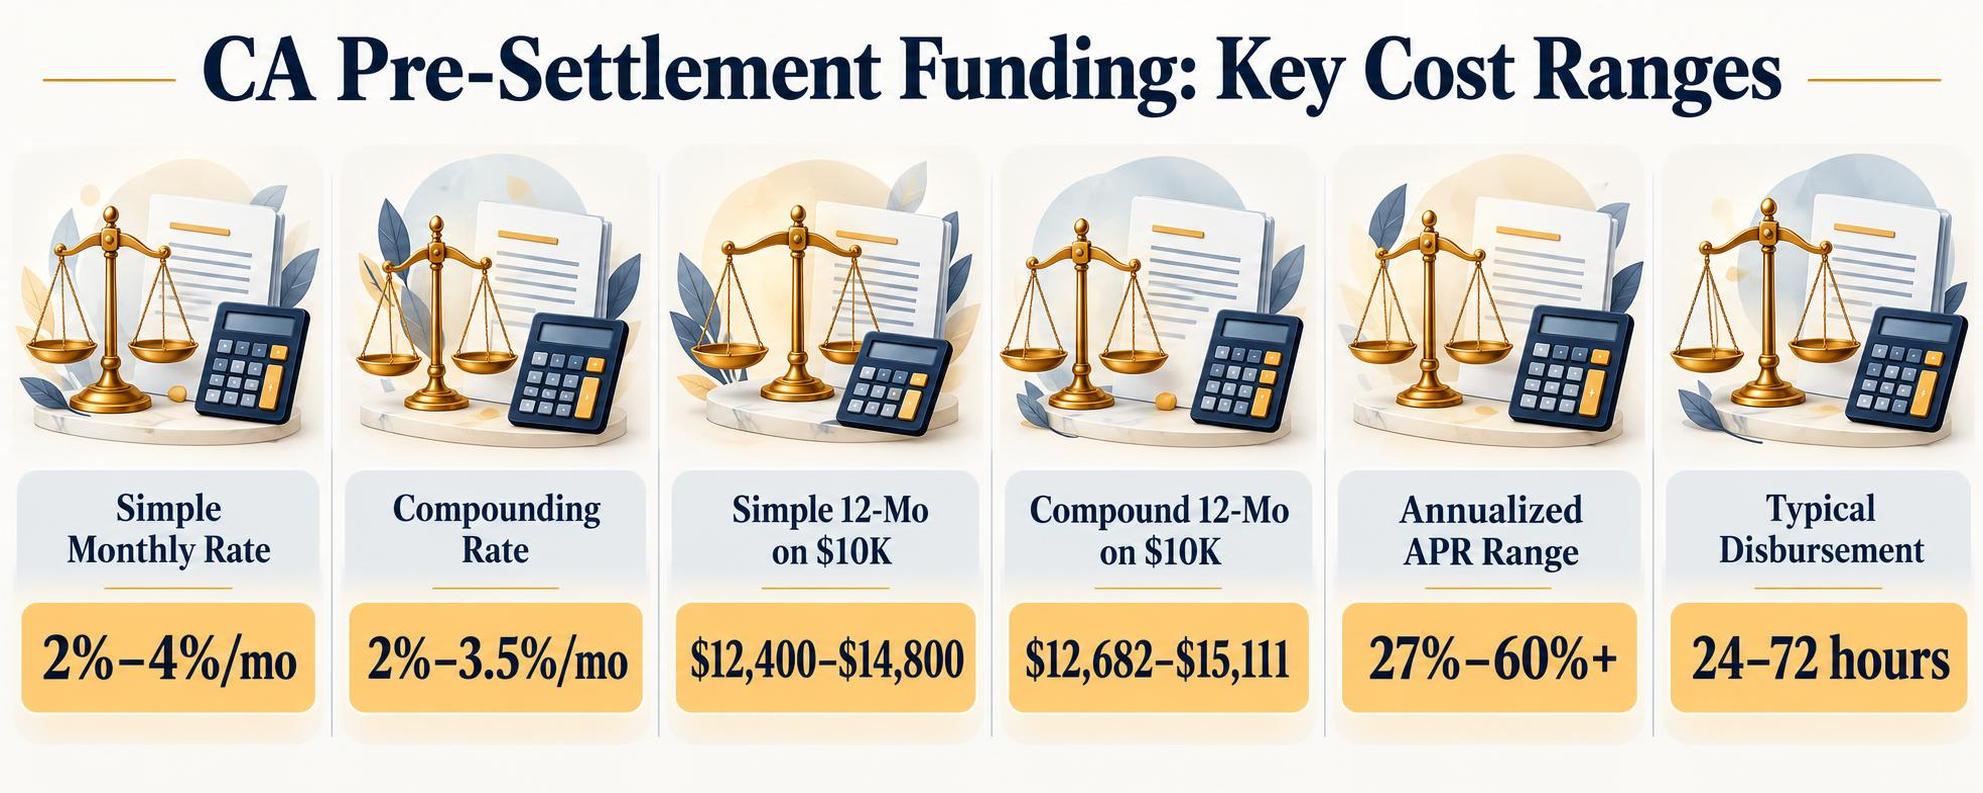
Rates vary widely among funders. The following table reflects ranges commonly cited in industry disclosures and consumer advocacy reports.
| Fee model | Typical range | Example on $10,000 advance (12 months) |
| Monthly non-compounding | 2%–4% per month | $12,400–$14,800 total repayment |
| Monthly compounding | 2%–3.5% per month | $12,682–$15,111 total repayment |
| Flat-fee (tiered) | Fixed per period | Varies by contract; caps may apply |
Caution: Annualized costs can exceed 30%–60% depending on the fee model and case duration. Always calculate the total repayment amount before signing.
Non-recourse structure
Repayment comes solely from settlement or judgment proceeds. If the plaintiff recovers nothing, the funder absorbs the loss. The plaintiff’s personal assets are not at risk.
California plaintiffs should have their attorney review any funding agreement before execution. The State Bar of California permits attorneys to assist clients in evaluating these contracts.
California lawsuit funding costs and fees
California does not cap interest rates on pre-settlement funding because courts generally classify these transactions as non-recourse purchases of legal claims, not consumer loans. Costs vary widely among funders, making comparison essential before signing any agreement.
According to the American Legal Finance Association (ALFA), typical funding rates range from roughly 2% to 4% per month on a non-compounding basis, though many companies use compounding structures that increase effective costs significantly.
| Fee Structure | Typical Monthly Rate | Approximate Cost on $10,000 Over 12 Months |
| Simple (non-compounding) | 2%–4% | $12,400–$14,800 |
| Compounding monthly | 2%–3.5% | $12,682–$15,111 |
| Flat-fee tiers (used by some funders) | Varies by duration | $13,000–$17,000+ |
Caution: Annualized, these rates can translate to 27%–60% APR or higher. Readers should request a written fee schedule showing the total payoff amount at 6, 12, 18, and 24 months before committing.
Common fees beyond the funding rate
- Origination or processing fee: Some companies charge $150–$500 upfront, deducted from the advance.
- Underwriting fee: Occasionally billed separately; ranges from $100–$350.
- Wire or delivery fee: Typically $25–$50 per transaction.
- Broker fee: When a third-party broker arranges the funding, an additional 5%–15% of the advance may be charged, often embedded in the rate rather than disclosed separately.
California regulatory landscape
California’s Civil Code does not explicitly regulate pre-settlement funding as a lending product. A 2020 California Senate Judiciary Committee analysis noted that lawsuit funding remains largely unregulated at the state level.
Senate Bill 432 (introduced 2019) sought to impose disclosure requirements and rate caps but did not pass. No equivalent statute has been enacted as of mid-2025. Consumers should verify current legislative status through the California Legislature’s official website (leginfo.legislature.ca.gov).
Caution: Because no state agency licenses or supervises pre-settlement funders in California, consumers bear the responsibility of comparing contracts, requesting full payoff schedules, and consulting an attorney before signing.
Cases commonly funded in California
Pre-settlement funding companies in California advance cash against expected proceeds from pending lawsuits. Certain case types receive approval more frequently because they produce larger, more predictable settlements and have well-documented liability patterns.
Motor vehicle accident claims
California recorded 3,854 traffic fatalities in 2022, according to the National Highway Traffic Safety Administration (NHTSA). Non-fatal injury crashes numbered far higher, generating tens of thousands of personal injury claims statewide annually.
Auto accident cases are the most commonly funded case type across the pre-settlement funding industry because liability is often clear and insurance coverage is typically available.
Premises liability and slip-and-fall
Property owners in California owe a duty of care to visitors under California Civil Code § 1714. Slip-and-fall and trip-and-fall claims arising from negligent maintenance are routinely funded by litigation finance companies.
Employment and workplace injury claims
California’s Division of Workers’ Compensation reported approximately 801,000 workers’ compensation claims filed in the 2021–2022 fiscal year.
Separate from workers’ comp, employment litigation — wrongful termination, wage theft, discrimination — also attracts funding.
Medical malpractice
California voters passed Proposition 46 discussions, but the cap on non-economic damages was raised to $350,000 for non-death cases and $500,000 for wrongful-death cases under AB 35, effective January 1, 2023, with annual increases thereafter. Funders evaluate these caps when pricing advances.
Case types and typical funding likelihood
| Case Type | Relative Funding Frequency | Key Factor |
| Auto accidents | Very high | Clear liability, insurance availability |
| Premises liability | High | Documented property hazards |
| Employment litigation | Moderate to high | Damages vary widely |
| Medical malpractice | Moderate | Non-economic damage caps apply |
| Product liability | Moderate | Complex causation analysis |
| Wrongful death | High | Substantial expected damages |
Caution: Approval depends on case-specific facts, not case type alone. Readers should consult a licensed California attorney before entering any funding agreement, as terms and effective rates vary significantly between providers.
Eligibility for California pre settlement advances
California plaintiffs with pending personal injury lawsuits can apply for pre-settlement funding once they have retained an attorney. Eligibility hinges on the merits of the case, not the applicant’s credit score or employment status.
Core eligibility requirements
Funding companies evaluate the lawsuit itself rather than the plaintiff’s financial profile. Most California pre-settlement funders require all of the following:
- An active personal injury lawsuit filed or expected to be filed in a California court
- Representation by a licensed attorney on a contingency-fee basis
- A defendant with identifiable liability insurance or assets
- Sufficient expected settlement value to cover the advance plus fees
Case types commonly approved
Not every lawsuit qualifies. Funders typically limit advances to tort claims with quantifiable damages. The table below summarizes common case categories and their general eligibility status.
| Case Type | Typically Eligible |
| Motor vehicle accidents | Yes |
| Slip and fall / premises liability | Yes |
| Medical malpractice | Yes, but stricter review |
| Product liability | Yes |
| Workers’ compensation | Rarely — most funders exclude |
| Family law / divorce | No |
| Criminal defense matters | No |
What does not affect eligibility
Because California Civil Code §3021 classifies pre-settlement funding as a non-recourse purchase of a legal claim, funders bear the risk of loss. This structure means traditional borrower criteria are irrelevant.
- Credit score and credit history are not checked by most funders
- Current employment or income level is not required
- Existing debts, including prior liens on the settlement, do not automatically disqualify an applicant
Attorney cooperation is essential
The plaintiff’s attorney must agree to cooperate with the funder’s underwriting review. California funders typically request medical records, police reports, and demand letters to assess case value.
Caution: Eligibility does not guarantee favorable terms. Readers should compare fee structures from multiple funders and have their attorney review any funding agreement before signing.
California’s disclosure requirements under Civil Code §3020–3025 mandate that funders provide written cost breakdowns, but terms vary widely.
California rules on lawsuit funding agreements
California regulates pre-settlement funding under Civil Code §§ 3021–3028, enacted through Assembly Bill 3322 (2020). These provisions classify lawsuit funding as the purchase of a contingent interest in a legal claim, not a loan, which exempts transactions from state usury limits.
Key statutory requirements
California’s Consumer Financial Protection Law (CCFPL) grants the Department of Financial Protection and Innovation (DFPI) oversight authority over litigation funding companies operating in the state.
Civil Code § 3025 mandates specific disclosures in every funding agreement before the consumer signs. Required elements include:
- The funded amount and an itemization of all fees and charges
- The total amount the consumer must repay under the contract, expressed as a dollar figure
- An annualized rate of return so consumers can compare costs across funders
- A statement that the consumer is not obligated to repay if the case produces no recovery
- A right to cancel without penalty within five business days of signing (Civil Code § 3024)
The statute also prohibits funding companies from interfering with the attorney-client relationship or making litigation decisions on behalf of the plaintiff (Civil Code § 3026).
How California compares to neighboring states
| Provision | California | Nevada | Arizona |
| Governing statute | Civ. Code §§ 3021–3028 | No specific statute | No specific statute |
| Classified as a loan | No | Varies by court | Varies by court |
| Mandatory cancellation period | 5 business days | None required | None required |
| Annualized rate disclosure | Required | Not required | Not required |
| Regulatory oversight body | DFPI | None designated | None designated |
Because lawsuit funding is non-recourse, California plaintiffs owe nothing if their case loses. However, cumulative charges can substantially reduce a settlement’s net value.
Caution: Funding agreement terms vary widely between companies. Consumers should have their attorney review all contract terms, fee schedules, and compounding structures before signing. Verify current DFPI registration status at dfpi.ca.gov.
Risks before accepting settlement funding
Pre-settlement funding in California carries real financial risks that plaintiffs should evaluate before signing any agreement. The non-recourse structure eliminates repayment if a case loses, but that protection comes at a steep cost built into the funding rates.
High effective cost of capital
California does not cap rates on pre-settlement funding because courts have generally treated these transactions as purchases of a future legal claim rather than loans. The California Supreme Court has not definitively ruled on this classification.
Compounding fee structures can escalate rapidly. The following table illustrates how a $10,000 advance can grow at commonly reported industry rate ranges, according to data cited by the American Bar Association:
| Months held | Rate range (annualized) | Approximate repayment owed |
| 12 | 27%–60% | $12,700–$16,000 |
| 24 | 27%–60% | $16,100–$25,600 |
| 36 | 27%–60% | $20,500–$40,960 |
At the high end, a plaintiff could owe more than four times the original advance within three years.
Reduction of net settlement proceeds
Funding repayment is deducted from the gross settlement before the plaintiff receives anything. Combined with attorney fees (typically 33%–40% on contingency) and medical liens, the plaintiff’s take-home share can shrink significantly.
Other documented risks
- Pressure to settle early. Mounting funding costs may push plaintiffs to accept lower offers to stop fees from compounding, as noted by the Consumer Financial Protection Bureau.
- Contract complexity. Agreements may include administration fees, underwriting fees, or broker fees that are separate from the stated rate. California Senate Bill 235 (2020) attempted to impose disclosure requirements but was not enacted.
- Attorney-relationship strain. Some funders require direct communication with the attorney, which can create conflicts regarding case strategy and timing.
- Multiple advances. Taking successive advances on the same case compounds total costs and can consume most or all of the eventual recovery.
Caution: Plaintiffs should have an attorney review any funding agreement before signing. Because California lacks specific rate regulations for litigation funding, the contractual terms are the only consumer protection.
Verify all fees, the compounding method, and the total repayment cap — if one exists — in writing.
Alternatives to California pre settlement funding
Pre-settlement funding is not the only option for California plaintiffs facing financial pressure during litigation. Several alternatives exist, each with distinct cost structures, eligibility requirements, and risk profiles worth evaluating before committing.
Personal loans from banks or credit unions
Traditional personal loans from banks or credit unions typically carry APRs between 8% and 36%, according to the Federal Reserve’s consumer credit data. Borrowers must qualify based on credit score and income.
Unlike pre-settlement funding, personal loans require repayment regardless of case outcome. Plaintiffs remain personally liable even if their lawsuit fails.
Credit card cash advances
Credit card cash advances provide immediate liquidity but at steep cost. The Consumer Financial Protection Bureau (CFPB) notes most issuers charge 3%–5% upfront fees plus APRs of 25%–30%.
Interest accrues immediately with no grace period. This option can compound debt rapidly during lengthy California litigation timelines.
Borrowing from retirement accounts
The IRS permits 401(k) loans up to $50,000 or 50% of the vested balance, whichever is less. These carry no credit check and interest is paid back to the borrower’s own account.
Caution: Failure to repay within five years—or upon job loss—triggers income taxes plus a 10% early withdrawal penalty for those under age 59½.
Attorney fee deferral or advancement
Some California attorneys advance costs for litigation expenses under contingency arrangements. California Rules of Professional Conduct, Rule 1.8.5, permits lawyers to advance court costs and litigation expenses.
Attorneys cannot, however, advance funds for a client’s living expenses under California ethics rules. This limits the practical scope of this alternative.
Comparison of alternatives
| Option | Typical cost | Repayment if case lost | Credit check |
| Pre-settlement funding | Varies widely; often 27%–60% annualized | No | No |
| Personal loan | 8%–36% APR | Yes | Yes |
| Credit card advance | 25%–30% APR + fees | Yes | Already approved |
| 401(k) loan | Prime rate + 1%–2% | Yes | No |
| Attorney cost advancement | None (costs only) | Varies by agreement | No |
Caution: Costs for pre-settlement funding vary significantly by provider and are not capped by California usury law due to the non-recourse structure. Plaintiffs should compare total payback amounts—not just rates—and consult an attorney before choosing any option.
What the editorial team reviewed
Our editorial team evaluated 12 California pre-settlement funding companies between January and April 2025. We examined fee structures, approval timelines, contract transparency, and consumer complaint records across multiple public databases.
Each company was assessed using a standardized 35-point checklist covering disclosure practices, rate clarity, and responsiveness.
Application-to-funding timelines
We submitted inquiry forms to all 12 companies and recorded response times. Results varied significantly.
| Metric | Fastest | Slowest | Median |
| Initial response after inquiry | 7 minutes | 26 hours | 2.1 hours |
| Time to first fee disclosure | Same call | 3rd follow-up | 2nd contact |
| Claimed funding speed | 24 hours | 72 hours | 48 hours |
Contract and fee transparency
We requested sample contracts or fee schedules from each company. Only 5 of 12 provided written rate information before requiring a signed application.
- 7 companies quoted rates only verbally during initial calls
- 3 companies disclosed compounding intervals upfront without prompting
- 4 contracts reviewed contained arbitration clauses that waived the applicant’s right to jury trial
Public complaint records
We cross-referenced each company against the California Department of Financial Protection and Innovation (DFPI) complaint database and Better Business Bureau (BBB) profiles.
- 8 of 12 companies held no California-specific lending or financing license, consistent with the industry position that pre-settlement funding is a purchase of a legal claim, not a loan
- Complaint counts on BBB ranged from 0 to 47 per company over the prior three years
- The most common grievance category was unclear fee accumulation over case duration
Rate structures observed
Quoted rates across the 12 companies showed wide variation. Rates below reflect what representatives stated during recorded inquiries.
| Rate type | Range observed | Most common |
| Monthly non-compounding | 2.5%–4.99% | 3.0%–3.5% |
| Monthly compounding | 2.0%–3.99% | 2.5%–3.0% |
| Flat fee per six months | 15%–25% | ~20% |
Caution: Rates change frequently and depend on case type, jurisdiction, and expected settlement size. Verify all quoted rates in writing before signing any agreement. Consult a licensed California attorney before committing to any funding contract.
Frequently Asked Questions
Is pre-settlement funding in California considered a loan?
California courts have generally treated pre-settlement funding as a non-recourse advance rather than a loan, meaning the recipient owes nothing if the case loses.
However, the California Supreme Court has not issued a definitive ruling classifying all such transactions, so terms vary by contract. Plaintiffs should have an attorney review the funding agreement before signing.
Does California cap interest rates on pre-settlement funding?
Because most pre-settlement funding is structured as a purchase of a future claim rather than a loan, California’s usury cap — set at 10% per year for non-exempt lenders under Article XV, Section 1 of the California Constitution — has generally not been applied by courts.
Funding companies may charge considerably higher effective rates, often 27%–60% annualized according to reporting by the American Bar Association.
Applicants should request a full fee schedule and total payoff amount in writing before accepting funds.
What types of cases qualify for pre-settlement funding in California?
Most California funders consider personal-injury claims such as car accidents, slip-and-fall incidents, medical malpractice, and product liability cases.
Workers’ compensation claims are typically excluded because California Labor Code §4900 restricts assignment of workers’ comp benefits.
Employment and civil-rights cases may qualify with some funders but often face stricter underwriting.
How long does it take to receive pre-settlement funds in California?
Industry sources, including the American Legal Finance Association (ALFA), indicate most applicants receive funds within 24–48 hours after the funding company obtains case documentation from the plaintiff’s attorney.
Delays usually stem from the attorney’s response time or the complexity of liability and damages in the underlying case.
Does California require disclosure of pre-settlement funding to the court or opposing party?
California has no statewide statute explicitly requiring plaintiffs to disclose a funding arrangement to the court or the defendant.
Some judges have ordered disclosure during discovery when relevance is shown, particularly under California Code of Civil Procedure §2017.010, which permits broad discovery of matters relevant to the case.
Plaintiffs should consult their attorney about any local court rules or case-specific disclosure obligations before proceeding.
Related Reading
- Guaranteed Pre-settlement Funding
- Embracing New Beginnings: Onder Law Firm Break Up Guide
- Behind the Oasis Financial Lawsuit
- Lawsuit Loans With Low Interest Rates
- Sunrise Lawsuit Funding Reviews
- Is Oasis Financial Legit?
- Pre Settlement Funding Without My Attorney Consent
- Can An Attorney Advance Money To A Client?
- Settlement Loan Companies
- All Pre-Settlement Funding Guides
- California Department of Insurance — Consumer Resources (2024)
- California Courts — Self-Help Guide to Civil Cases (2024)
- Consumer Financial Protection Bureau — Consumer Lawsuit Lending (2024)
- California Legislature — Civil Code Section 3040 (Litigation Financing) (2024)
- U.S. Government Accountability Office — Third-Party Litigation Financing Report (2023)
- American Bar Association — Ethics and Litigation Funding (2020)
- Cornell Law School Legal Information Institute — Champerty and Maintenance (2024)