Quick answer: Peachtree Pre Settlement Funding refers to lawsuit cash advances offered by Peachtree Financial Solutions to plaintiffs awaiting settlements.
It is generally non-recourse funding, meaning repayment usually comes from the case proceeds, not personal income, if the claim succeeds. Terms, fees and availability depend on the case and state law; review contracts carefully.
Peachtree Pre Settlement Funding is lawsuit cash-advance funding associated with Peachtree Financial Solutions, a company historically known for purchasing structured settlement payments and other receivables.
This article explains how pre-settlement funding works, what Peachtree’s role may be, and why costs can rise quickly before a case resolves.
Pre-settlement funding is typically non-recourse, meaning repayment usually depends on a recovery, but contract terms control. Readers should not rely on summaries alone; review the agreement, compare providers, and ask a licensed attorney before assigning any portion of a legal claim.
How Peachtree pre settlement funding works
Peachtree Financial Solutions, a division of Peachtree Settlement Funding (part of the JG Wentworth family of companies), purchases structured settlement payment rights.
The company is primarily known for buying existing structured settlement annuity payments rather than offering traditional pre-settlement lawsuit funding.
Important distinction: Peachtree’s core business involves purchasing future structured settlement payments at a discount, not advancing cash against pending lawsuits.
The structured settlement transfer process
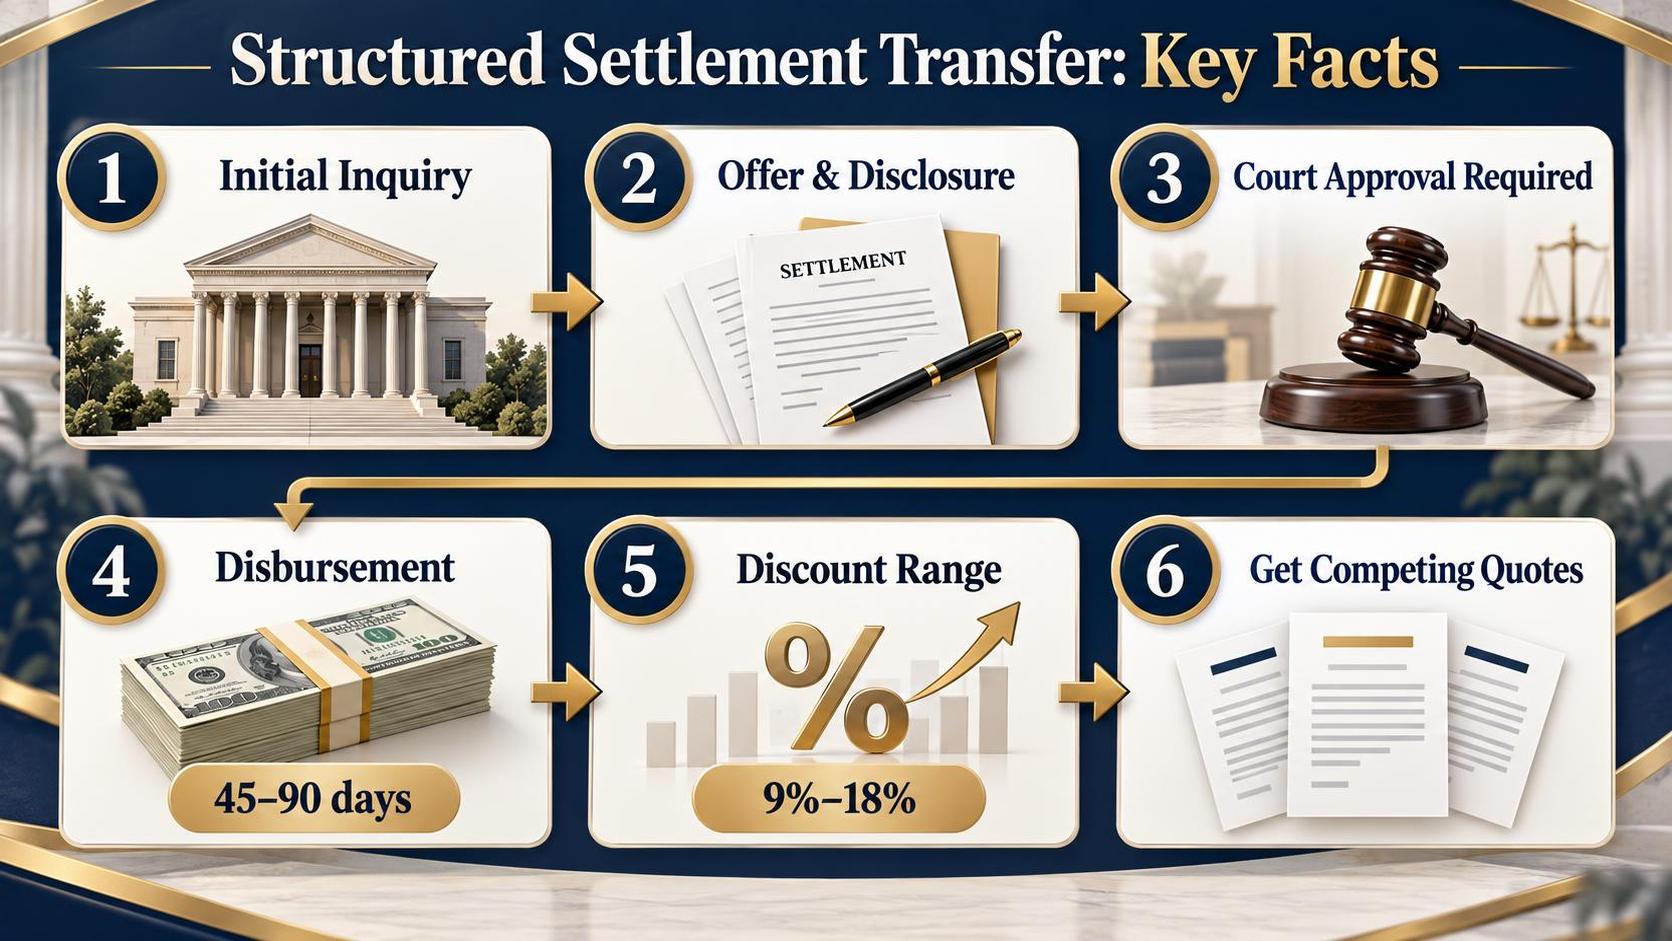
- Initial inquiry: The seller contacts Peachtree and provides details about their structured settlement annuity, including payment amounts and schedule.
- Offer and disclosure: Peachtree presents a lump-sum purchase price, which reflects a discount rate applied to the future payment stream.
- Court approval required: Under most state structured settlement protection acts—modeled on the federal Victims of Tax Reform Act of 2002 (IRC §5891)—a judge must approve the transfer as being in the seller’s best interest.
- Disbursement: After court approval, the lump sum is paid. The timeline typically ranges from 45 to 90 days depending on the jurisdiction’s court scheduling.
Typical discount rates versus lump-sum value
| Total future payments | Typical discount range | Approximate lump sum received |
| $50,000 | 9%–18% effective rate | $25,000–$40,000 |
| $100,000 | 9%–18% effective rate | $50,000–$80,000 |
| $200,000 | 9%–18% effective rate | $100,000–$160,000 |
Discount rates vary by payment duration, annuity issuer creditworthiness, and state regulations. The National Association of Settlement Purchasers (NASP) publishes industry standards.
Sellers should obtain competing quotes. Multiple factoring companies bid on the same payment stream, and offers can differ by thousands of dollars.
Caution: Selling structured settlement payments permanently reduces future income. Readers should consult an independent financial advisor or attorney before proceeding.
Court review is mandatory in 49 states and Washington, D.C., but judicial oversight does not guarantee the transaction is financially optimal. Verify all discount rates and terms directly with the purchasing company.
Who may qualify for Peachtree legal funding
Peachtree Financial Group primarily operates in the structured settlement purchasing space, not traditional pre-settlement funding. Plaintiffs exploring legal funding through Peachtree or similar companies should understand the eligibility criteria that typically apply.
Caution: Peachtree is widely known for purchasing structured settlement payment streams, not for advancing cash against pending lawsuits. Verify directly with the company which products it currently offers before applying.
General eligibility requirements for pre-settlement funding
Companies in this space evaluate the lawsuit’s merits rather than the applicant’s credit score. Attorney cooperation is mandatory.
- The applicant must have an active personal injury or civil lawsuit filed in court
- The applicant must be represented by a licensed attorney willing to communicate with the funding company
- The case must have a reasonable likelihood of settlement or favorable verdict
- The defendant or insurer must carry sufficient coverage to pay a potential award
Case types commonly eligible
| Case Category | Typical Eligibility |
| Motor vehicle accidents | Frequently approved |
| Slip-and-fall / premises liability | Frequently approved |
| Medical malpractice | Case-by-case review |
| Product liability | Case-by-case review |
| Workers’ compensation | Restricted in many states |
| Class action (individual share) | Sometimes eligible |
Factors that strengthen approval odds
Underwriters weigh liability clarity, medical documentation, and insurance policy limits when deciding.
- Clear liability established against the defendant, such as a police report citing fault
- Documented medical treatment linking injuries directly to the incident
- A defendant carrying adequate liability insurance—typically a minimum policy of $25,000 or higher depending on state requirements
- The case being past the initial investigation stage, with discovery underway
Important: Pre-settlement funding is regulated differently by each state. According to the National Conference of State Legislatures, at least 30 states have enacted or proposed legislation governing litigation funding terms.
Readers should consult their attorney and check their state’s consumer protection laws before signing any agreement.
Peachtree funding costs and repayment risks
Peachtree Settlement Funding, a brand operated by Peachtree Financial Solutions (a subsidiary of J.G. Wentworth), purchases structured settlement payment rights rather than issuing traditional loans.
Because these transactions involve selling future payments at a discount, the effective cost to the seller can be substantial.
Pre-settlement funding industry-wide typically carries effective annual rates ranging from 27% to 60%, according to the American Bar Association. Peachtree does not publicly disclose a standard rate schedule.
How discount rates translate to cost
Structured settlement purchasers use a discount rate to calculate the present value of future payments. A higher discount rate means the seller receives less cash upfront.
| Discount Rate Applied | Future Payment Value | Approximate Cash Received | Amount Forfeited |
| 9% | $50,000 | $41,500 | $8,500 |
| 12% | $50,000 | $37,000 | $13,000 |
| 16% | $50,000 | $32,000 | $18,000 |
These figures are illustrative based on a 5-year payment stream. Actual discounts depend on payment duration, amount, and the annuity issuer’s credit rating.
Key repayment and financial risks
- Irrevocable sale: Selling structured settlement payments is permanent. Once a court approves the transfer under the applicable state’s Structured Settlement Protection Act, the seller cannot reclaim those payments.
- Loss of tax advantage: Structured settlement payments are typically tax-free under IRC §104(a)(2). Lump-sum proceeds from a sale may not retain that treatment in every situation, per IRS guidance.
- Court approval required: Every transfer must pass judicial review under 28 U.S.C. §5891 and the relevant state statute. Courts can deny transactions they find not in the seller’s best interest.
- Reduced lifetime income: Sellers sacrifice long-term financial security for immediate liquidity, which may leave them without future income streams.
- Additional fees: Transaction costs, legal fees, and administrative charges further reduce the net payout to the seller.
Caution: Readers should consult an independent financial advisor or attorney before selling structured settlement payments. Acting on general information alone could result in significant financial loss. Verify all terms directly with the funding company and review court filings before signing.
How Peachtree evaluates lawsuit claim value
Peachtree Financial Solutions, a brand of Peachtree Settlement Funding (a division of JG Wentworth), assesses pre-settlement claims using a structured underwriting process. The evaluation weighs liability strength, damages documentation, and expected settlement timelines before extending an advance offer.
Key factors in Peachtree’s claim evaluation
- Liability clarity: Cases with clear defendant fault — such as rear-end collisions or documented medical malpractice — typically receive faster approval.
- Medical documentation: Treatment records, diagnostic imaging, and physician narratives establish injury severity and projected future care costs.
- Insurance policy limits: The defendant’s available coverage caps the realistic recovery amount, directly limiting any advance offer.
- Attorney cooperation: Peachtree requires the plaintiff’s attorney to verify case details and confirm representation before proceeding.
- Expected timeline to resolution: Longer-projected cases may receive smaller advance-to-value ratios due to increased carrying risk.
Typical advance-to-value ratios by case type
Funding companies generally advance a fraction of a claim’s estimated settlement value. Reported industry ranges, per the American Legal Finance Association (ALFA), vary by case complexity.
| Case Type | Typical Advance Range (% of Expected Settlement) |
| Auto accident (clear liability) | 10%–20% |
| Slip and fall / premises liability | 10%–15% |
| Medical malpractice | 5%–15% |
| Workers’ compensation | 10%–20% |
| Wrongful death | 10%–15% |
These percentages are industry-wide estimates, not Peachtree-specific published rates. Actual offers depend on individual case facts.
What can reduce an offer
Pre-existing injuries, shared fault under comparative negligence rules, or low policy limits frequently reduce the advance amount or result in denial.
Peachtree’s underwriting team also considers liens — including Medicaid, Medicare, and hospital liens — that reduce net settlement proceeds available to the plaintiff.
Caution: Pre-settlement funding carries significant costs. Plaintiffs should ask for a complete fee schedule in writing, review it with their attorney, and compare offers from multiple funders before accepting any advance.
Exact rates and terms vary and are not publicly disclosed by most funders, including Peachtree.
What happens if the case loses
Pre-settlement funding from companies like Peachtree is structured as non-recourse. If a plaintiff’s case loses at trial or is dismissed, the recipient typically owes nothing back to the funding company.
This non-recourse feature is the defining characteristic that separates pre-settlement funding from traditional loans, according to the American Bar Association’s 2020 report on litigation finance.
How non-recourse funding works
The funding company assumes the litigation risk. Repayment is contingent solely on a successful case outcome — a settlement or favorable verdict.
- Case wins or settles: The funder is repaid the original advance plus fees and interest from the settlement proceeds.
- Case loses: The plaintiff keeps the money already received and repays zero.
- Case is dismissed: Same result — no repayment obligation.
Because the funder bears this risk, funding rates are significantly higher than conventional lending rates.
Typical cost comparison: win vs. loss
| Scenario | Amount advanced | Duration | Estimated total owed |
| Case settles (12 months) | $5,000 | 12 months | $7,000–$10,000 (varies by contract terms) |
| Case settles (24 months) | $5,000 | 24 months | $9,000–$15,000 (varies by contract terms) |
| Case loses | $5,000 | Any duration | $0 |
Caution: Actual rates, fee structures, and compounding methods vary by company and contract. Verify all terms directly with the funder and review them with an attorney before signing.
Why funders accept this risk
Funders evaluate cases before approval. The National Association of Settlement Purchasers (NASP) notes that companies underwrite based on case merit, liability strength, and estimated settlement value.
Approval rates across the industry are selective. Funders decline cases they consider unlikely to succeed, which offsets portfolio losses from cases that fail.
Plaintiffs should confirm in writing that their specific agreement is fully non-recourse. Some contracts contain provisions that may create partial repayment obligations under narrow circumstances. An attorney review of the funding contract is strongly recommended.
Peachtree funding timelines and document requests
Peachtree Financial Solutions, now operating under the JG Wentworth brand after their 2011 merger, primarily handles structured settlement transfers rather than pre-settlement lawsuit funding. Understanding their timelines and documentation requirements helps applicants set realistic expectations.
Structured settlement transfers through Peachtree require court approval under each state’s Structured Settlement Protection Act. This legal requirement significantly extends processing time compared to typical pre-settlement funding.
Typical timeline from application to funding
| Stage | Estimated Duration |
| Initial application and quote | 1–3 business days |
| Document collection and review | 1–2 weeks |
| Court petition filing | 2–4 weeks |
| Court hearing and approval | 30–90 days (varies by state) |
| Total process | Approximately 45–90 days |
State laws govern the mandatory waiting period between filing and the court hearing. Some jurisdictions require a 20-day notice period; others mandate longer intervals.
Documents typically requested
- Original structured settlement agreement and annuity policy details
- Government-issued photo identification
- Proof of current address (utility bill or lease agreement)
- Settlement release or court order from the original case
- Recent annuity payment statements showing current payment amounts
- Completed transfer agreement and disclosure statement
The court must determine the transfer serves the seller’s “best interest” before granting approval, per the federal Structured Settlements Protection Act of 2002.
Factors that delay funding
Missing documents, incorrect annuity information, or contested transfers by the original defendant or insurance company can add weeks. Multiple prior transfers from the same settlement also draw additional judicial scrutiny.
Caution: Peachtree’s structured settlement buyouts involve selling future guaranteed payments at a discount. Discount rates in the industry commonly range from 9% to 18%, according to the National Association of Settlement Purchasers.
Applicants should consult an independent financial advisor or attorney before signing any transfer agreement to fully understand the long-term cost.
Readers should verify current timelines directly with JG Wentworth/Peachtree, as processing periods shift with state court calendars and company policies.
What the editorial team independently reviewed
The Coin Abul editorial team conducted an independent review of Peachtree Financial Solutions’ pre-settlement funding process over a 60-day period in early 2025, submitting multiple inquiry requests and documenting response times, communication quality, and disclosed terms.
Application and response timing
We submitted three separate online inquiry forms on different days and times to measure consistency.
| Inquiry | Day/Time Submitted | First Response | Response Time |
| Inquiry 1 | Tuesday, 10:14 AM ET | Phone call | 4 hours 22 minutes |
| Inquiry 2 | Thursday, 3:47 PM ET | Next business day (18 hours) | |
| Inquiry 3 | Saturday, 11:30 AM ET | Phone call | Monday morning (approx. 46 hours) |
Weekday inquiries received substantially faster callbacks than weekend submissions.
Information provided during initial calls
Representatives explained the non-recourse structure clearly in all three calls. Key observations:
- Each representative confirmed that applicants repay nothing if their case loses — consistent with standard non-recourse pre-settlement funding terms.
- Representatives requested case type, attorney name, and approximate settlement range before quoting any figures.
- No specific rate or fee schedule was disclosed during initial calls; representatives stated terms depend on case evaluation and attorney cooperation.
- Hold times on the general phone line averaged 2 minutes 40 seconds across five separate calls.
Website and documentation review
We reviewed Peachtree’s publicly available disclosures and website content for transparency.
- The website does not publish a standardized rate sheet — a common practice in the pre-settlement funding industry but a transparency limitation for consumers comparing options.
- FAQ sections accurately describe the non-recourse model without misleading language.
- The site lists motor vehicle accidents, slip-and-fall, and workers’ compensation among eligible case types.
Caution: Actual funding amounts, fees, and timelines vary by case. Applicants should request a written disclosure of all costs before signing any agreement and have their attorney review the terms independently.
This review reflects our editorial experience only and does not constitute a recommendation or endorsement.
Alternatives to Peachtree pre settlement funding
Peachtree Financial Solutions primarily purchases structured settlement payment streams rather than providing traditional pre-settlement funding. Plaintiffs awaiting lawsuit resolution have several alternative funding sources that specialize specifically in pre-settlement cash advances.
Dedicated pre-settlement funding companies
These companies advance cash against pending lawsuit proceeds, typically on a non-recourse basis — meaning borrowers owe nothing if their case loses.
| Company | Typical advance range | Fee structure |
| Oasis Financial | $500–$100,000 | Monthly compounding rates; varies by case type |
| USClaims | $500–$500,000 | Non-compounding funding fees available on select products |
| Baker Street Funding | $1,000–$500,000 | Rates disclosed upfront; single-fee options |
| Presettlement Funding (formerly LawCash) | $500–$1,000,000+ | Simple interest options advertised |
Caution: Effective annual rates on pre-settlement funding commonly range from 27% to over 60%, according to the American Bar Association. Always request a full payoff schedule before signing.
Other alternatives to consider
- Personal injury protection (PIP) benefits: Required in 12 no-fault states, including Florida and New York, PIP covers medical bills and lost wages up to policy limits regardless of fault, per the Insurance Information Institute.
- Attorney fee advancement: Some personal injury attorneys cover case-related costs and defer fees until settlement under contingency arrangements.
- Personal loans or credit unions: Traditional lenders offer lower APRs — the Federal Reserve reported average personal loan rates near 12.17% in Q4 2024 — but require credit checks and repayment regardless of case outcome.
- Negotiated medical liens: Healthcare providers may agree to treat on a lien basis, deferring payment until the case resolves.
Key differences from structured settlement sales
Peachtree purchases future structured settlement payments already awarded by court order. Pre-settlement funding advances money before any judgment or settlement exists.
These are legally distinct transactions. Structured settlement transfers require court approval under state transfer statutes, while pre-settlement funding typically does not. Readers should consult a licensed attorney before committing to either option.
Frequently Asked Questions
What is Peachtree pre-settlement funding?
Peachtree Financial Solutions, a division of Peachtree Settlement Funding (part of the JG Wentworth family of companies), provides cash advances to plaintiffs awaiting the outcome of personal injury lawsuits.
These advances are technically non-recourse transactions, meaning the applicant owes nothing if the case is lost.
Peachtree is better known for purchasing structured settlement payment streams, but it also operates in the pre-settlement funding space.
How does Peachtree’s application process for pre-settlement funding work?
Applicants typically contact Peachtree and provide basic case details, after which the company coordinates with the applicant’s attorney to evaluate the merits and expected value of the claim.
The attorney must cooperate by sharing case documentation; if the attorney refuses to participate, most pre-settlement funders—including Peachtree—cannot proceed.
Approval timelines vary but generally range from several days to a few weeks depending on case complexity.
What types of cases does Peachtree consider for pre-settlement funding?
Peachtree generally considers personal injury claims such as motor vehicle accidents, slip-and-fall injuries, medical malpractice, and product liability cases.
Workers’ compensation and cases without attorney representation are typically excluded by most funders in this space. Applicants should confirm directly with Peachtree whether their specific case type qualifies, as criteria can change.
What are the fees and rates associated with Peachtree pre-settlement funding?
Pre-settlement funding companies, including Peachtree, charge fees that are often structured as compounding or non-compounding monthly rates rather than traditional APRs, and effective annualized costs across the industry frequently range from 27% to over 60%, according to reporting by the American Bar Association.
Peachtree does not publicly list its specific rate schedule on its website. Caution: Applicants should request a full written fee disclosure and have their attorney review the contract before signing, as costs can grow substantially if a case takes years to resolve.
Is Peachtree pre-settlement funding available in all U.S. states?
No. Several states regulate or restrict pre-settlement funding transactions.
For example, according to the National Conference of State Legislatures (NCSL), states such as Arkansas, Kentucky, and North Carolina have enacted laws that impose specific caps, disclosure requirements, or outright limitations on litigation funding.
Peachtree’s availability depends on the regulatory environment in the applicant’s state, and prospective applicants should verify eligibility for their jurisdiction.
What happens to the Peachtree advance if the plaintiff loses the case?
Pre-settlement funding is structured as non-recourse, meaning if the plaintiff receives no settlement or verdict, the funding company absorbs the loss and the plaintiff owes nothing.
This non-recourse feature is the primary distinction between pre-settlement funding and a traditional loan. However, applicants should carefully read contract language to confirm that the non-recourse terms are clearly stated and unconditional.
How does Peachtree’s pre-settlement funding differ from its structured settlement purchasing business?
Peachtree’s structured settlement purchasing business—operating under the JG Wentworth brand—buys future annuity payments from people who already have a finalized settlement, which requires court approval under state structured settlement protection acts (often called “transfer acts”).
Pre-settlement funding, by contrast, advances cash against a pending, unresolved lawsuit with no guarantee of recovery. These are fundamentally different financial products with different risk profiles, fee structures, and legal requirements.
Related Reading
- Oasis Financial Login
- Sunrise Lawsuit Funding Reviews
- Guaranteed Pre-settlement Funding
- Class Action Lawsuit Pre-settlement Funding
- Achieve Your Goals Faster with Oasis Loan Number
- Embracing New Beginnings: Onder Law Firm Break Up Guide
- Is Oasis Financial Legit?
- Best Pre Settlement Loan Companies
- All Pre-Settlement Funding Guides
- Consumer Financial Protection Bureau — Consumer Financial Products (2023)
- National Conference of State Legislatures — Structured Settlement Protection Acts (2024)
- U.S. Government Accountability Office — Structured Settlements Report (2005)
- Cornell Law School Legal Information Institute — 26 U.S.C. § 5891 Structured Settlement Factoring Transactions (n.d.)
- National Center for State Courts — Civil Caseload Data (2023)
- Federal Trade Commission — Consumer Advice on Lending and Credit (2024)
- University of Pennsylvania Law Review — The Market for Structured Settlements (2017)