Quick answer: Pre Settlement Funding Florida is nonrecourse financing secured by a pending personal-injury settlement.
The recipient generally repays the funder only if the case produces proceeds, but the contract’s fees and repayment amount can be substantial.
Review the agreement with an attorney before accepting funds, because costs and legal treatment vary by provider.
Pre Settlement Funding Florida is non-recourse lawsuit financing that provides money before a personal-injury case resolves, with repayment generally tied to a successful settlement or judgment.
The funding company—not the plaintiff—typically assumes the risk of losing the case, but the contract determines costs, repayment, and control terms.
Florida applicants should review the agreement’s effective annualized cost, payment priority, attorney involvement, and consequences of dismissal or appeal.
Funding can help cover living or medical expenses, but it can reduce the net recovery substantially. A Florida attorney should review the contract before signing.
Availability and legal treatment can vary by provider and case type. Readers should compare written disclosures, ask how the balance grows, and verify current Florida requirements through official sources before accepting funds.
How Florida pre-settlement funding works
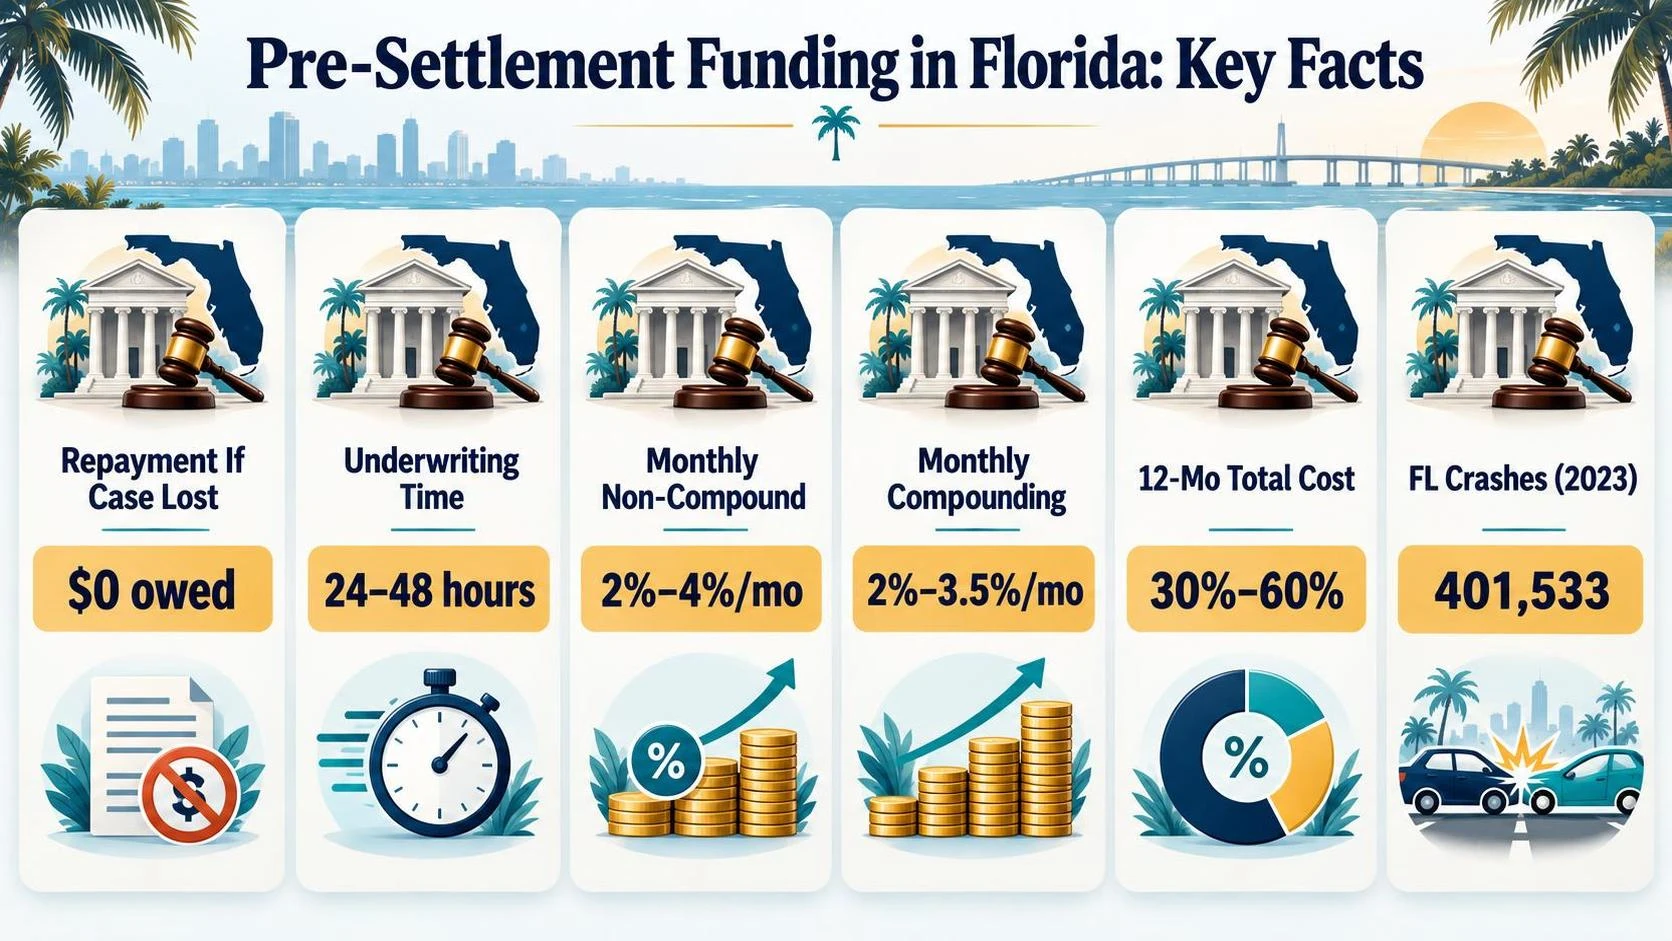
Pre-settlement funding in Florida provides a non-recourse cash advance to plaintiffs awaiting case resolution. If the case loses, the plaintiff owes nothing — the funder absorbs the loss entirely.
Florida does not classify pre-settlement funding as a loan. The Florida Supreme Court addressed this in Echeverria v. Estate of Lindner (2005), distinguishing litigation funding from traditional lending because repayment is contingent on case outcome.
Step-by-step process
- The plaintiff applies with a funding company, providing case details and attorney contact information.
- The funder contacts the attorney to review case merits, liability evidence, and estimated settlement value.
- Underwriting typically takes 24 to 48 hours, according to the American Legal Finance Association (ALFA).
- If approved, the plaintiff signs a funding agreement specifying the advance amount and fee structure.
- Funds are disbursed — often within one business day after signing.
- When the case settles, the funder is repaid from settlement proceeds. If the case loses at trial, the plaintiff keeps the advance.
Typical fee structures
Funding companies in Florida commonly charge compounding or non-compounding monthly rates. Florida has no statute capping pre-settlement funding fees specifically.
| Fee type | Common range | Source |
| Monthly non-compounding | 2%–4% per month | ALFA industry survey |
| Monthly compounding | 2%–3.5% per month | Consumer Financial Protection Bureau (CFPB) market report |
| Total cost on 12-month advance | 30%–60% of funded amount | ALFA industry data |
Key Florida-specific considerations
Florida follows a pure comparative negligence standard under Fla. Stat. § 768.81, meaning a plaintiff’s recovery can be reduced by their percentage of fault. Funders factor this into underwriting risk.
In 2023, Florida enacted tort reform (HB 837) reducing the statute of limitations for negligence claims from four years to two. This compressed timeline can affect case valuations and funding terms.
Caution: Fee structures vary widely among funders. Plaintiffs should have their attorney review any funding agreement before signing and compare offers from multiple companies.
Florida lawsuit funding eligibility requirements
Florida pre-settlement funding companies evaluate applicants based on case merit rather than credit history or employment status. Eligibility hinges on having a pending personal injury lawsuit with attorney representation in a Florida court.
Core eligibility criteria across most Florida funders:
- An active, filed personal injury lawsuit in Florida state or federal court
- Legal representation by a licensed attorney who agrees to cooperate with the funding company
- A defendant or insurance policy with sufficient coverage to satisfy a potential settlement
- The case must not have been previously denied funding by the same company
Credit scores, employment history, and personal income are not factors. The application is underwritten against the projected settlement value, not the applicant’s finances.
Case types that typically qualify
| Case Type | Typical Eligibility | Notes |
| Auto accidents | Most commonly approved | Florida’s high crash rate (401,533 crashes in 2023, per FLHSMV) drives volume |
| Slip and fall / premises liability | Generally eligible | Must show clear property-owner negligence |
| Medical malpractice | Eligible but scrutinized | Longer litigation timelines increase underwriting risk |
| Wrongful death | Eligible | Florida’s Wrongful Death Act (Fla. Stat. § 768.16–768.26) governs survivor claims |
| Product liability | Case-by-case | Requires identifiable manufacturer or distributor defendant |
| Workers’ compensation | Rarely eligible | Most funders exclude due to statutory benefit caps |
Funders typically require the attorney to sign a Letter of Protection (LOP) or lien acknowledgment before disbursing funds.
Florida Statute § 501.975 (effective 2023) requires funding companies to provide specific written disclosures, including the funded amount, itemized charges, and total repayment. This law strengthened consumer protections statewide.
Caution: Eligibility does not guarantee approval. Each funder applies proprietary underwriting standards. Applicants should have their attorney review all contract terms—including fee structures and repayment triggers—before signing any agreement.
Costs and repayment of lawsuit advances
Pre-settlement funding in Florida is not a traditional loan — it is a non-recourse cash advance repaid only if the case wins. Because funders assume the risk of losing their investment entirely, the cost is significantly higher than conventional borrowing.
Funding companies typically charge between 2% and 4% per month in fees, according to the American Bar Association. Some companies use compounding, which raises the total payback substantially over time.
| Advance Amount | Monthly Rate | Duration | Approximate Total Owed |
| $10,000 | 2.5% simple | 12 months | $13,000 |
| $10,000 | 3.0% simple | 18 months | $15,400 |
| $10,000 | 3.5% compounding | 24 months | $22,900+ |
These figures are illustrative estimates based on published industry ranges. Actual costs vary by provider, case type, and contract terms. Readers should request a full fee schedule before signing any agreement.
How repayment works in Florida
Repayment comes directly from settlement proceeds. The funding company is typically repaid by the plaintiff’s attorney at the time of disbursement, before the client receives remaining funds.
- Win or settle: The funder receives the advance plus all accrued fees from the settlement or verdict.
- Lose the case: The plaintiff owes nothing. The funder absorbs the loss entirely — this is the non-recourse structure.
- No monthly payments: Unlike a bank loan, there are no periodic installments during the life of the case.
Florida regulatory landscape
Florida does not cap fees on pre-settlement funding. The Florida legislature has considered regulation — such as House Bill 1431 introduced in 2019 — but no comprehensive fee-cap statute has been enacted as of 2024, per the Florida Senate archives.
Without statutory rate limits, consumers must compare multiple offers carefully. The Consumer Financial Protection Bureau recommends reviewing all contract terms with an attorney before accepting any litigation funding product.
Caution: High cumulative fees can consume a large portion of a settlement. Plaintiffs should calculate the total repayment amount under different case-duration scenarios and consult their attorney before proceeding.
Florida rules affecting settlement funding
Florida does not regulate pre-settlement funding through a dedicated statute the way some states do. Instead, several general consumer-protection and contract-law provisions shape how funding companies operate in the state.
Florida courts have consistently treated pre-settlement funding as a purchase of a future receivable, not a loan. This classification means traditional usury caps under Florida Statute §687.03 generally do not apply.
Key Florida statutes relevant to settlement funding
| Statute | Relevance |
| Fla. Stat. §687.02 | Sets the general maximum interest rate at 18% per year for loans under $500,000; funding companies argue this does not apply to non-recourse advances. |
| Fla. Stat. §687.071 | Criminal usury statute; rates exceeding 25% annually on amounts ≤$500,000 may constitute a felony if the transaction is classified as a loan. |
| Fla. Stat. §501.204 | Florida Deceptive and Unfair Trade Practices Act (FDUTPA); prohibits misleading fee disclosures and hidden charges in consumer transactions. |
| Fla. Stat. §768.79 | Offer-of-judgment statute that can influence settlement timing and, indirectly, the duration a funding advance remains outstanding. |
Practical implications for Florida plaintiffs
- No licensing requirement: Florida does not require pre-settlement funding companies to hold a special license, unlike states such as Nebraska (which passed LB 68 in 2023 requiring registration).
- Non-recourse structure: If the plaintiff loses the case, the funder absorbs the loss. Florida contract law enforces this “no-win, no-pay” provision.
- Attorney cooperation: Most funders require the plaintiff’s attorney to sign an acknowledgment letter and agree to direct repayment from settlement proceeds, per standard Florida assignment-of-proceeds rules.
- No mandated fee caps: Effective annual rates charged by funding companies in Florida commonly range from 27% to over 60%, according to a 2020 analysis by the American Bar Association. Readers should compare multiple offers and request full fee schedules before signing.
Caution: Because Florida lacks a dedicated pre-settlement funding statute, consumer protections are limited. Plaintiffs should have their attorney review any funding agreement before execution and verify all fees in writing.
Risks before accepting a funding agreement
Pre-settlement funding in Florida carries financial risks that applicants should evaluate before signing any agreement. The non-recourse structure protects plaintiffs from repayment if they lose, but the cost of that protection can significantly reduce a final settlement.
Compounding fees erode settlement proceeds
Most pre-settlement funding companies charge fees that compound monthly or annually rather than using simple interest. The difference grows dramatically over time.
| Case duration | Simple interest at 3% monthly | Compound interest at 3% monthly | Total owed on $10,000 advance (compound) |
| 12 months | $13,600 | $14,258 | $14,258 |
| 24 months | $17,200 | $20,328 | $20,328 |
| 36 months | $20,800 | $28,983 | $28,983 |
At 36 months with compounding, a plaintiff could owe nearly three times the original advance. According to the American Bar Association, litigation timelines frequently exceed two years.
Lack of fee caps under Florida law
Florida does not classify pre-settlement funding as a loan. As the Florida Office of Financial Regulation has noted, usury statutes (Florida Statutes §687.02) generally do not apply to non-recourse litigation funding transactions. This means no statutory interest-rate ceiling protects consumers.
Other risks to evaluate
- Double-dipping fees: Some contracts layer origination fees (typically 5%–15% of the advance) on top of monthly usage fees, inflating the effective annual rate well beyond the stated percentage.
- Attorney lien conflicts: Funding liens attach to settlement proceeds alongside attorney contingency fees (commonly 33%–40% in Florida per Florida Bar guidelines), potentially leaving the plaintiff with a fraction of the award.
- Pressure to settle early: Mounting funding costs can push plaintiffs to accept lowball offers, undermining their case value.
- Contract ambiguity: Some agreements use terms like “preferred return” or “investment fee” instead of “interest,” making true cost comparisons difficult.
Caution: Have your attorney review any funding contract before signing. No one should rely solely on this article for financial or legal decisions — consult a licensed Florida attorney familiar with litigation finance.
Alternatives to pre-settlement funding in Florida
Pre-settlement funding is not the only option for Florida plaintiffs who need cash during litigation. Several alternatives carry lower costs, though each comes with distinct eligibility requirements and risks worth evaluating before committing.
Personal loans from banks or credit unions
Traditional personal loans from banks or credit unions typically charge far less than litigation funding. According to the Federal Reserve’s May 2025 data, the average personal loan interest rate at commercial banks was approximately 12.35% APR — a fraction of what most funders charge.
The drawback: lenders evaluate creditworthiness and income. Plaintiffs unable to work due to injuries often cannot qualify.
Credit cards
Credit cards offer immediate access to funds without disclosing lawsuit details. Average credit card APR stood at 21.76% as of Q1 2025, per the Federal Reserve’s G.19 Consumer Credit report.
Unlike pre-settlement funding, credit card debt must be repaid regardless of case outcome. This creates financial risk if the lawsuit is unsuccessful.
Borrowing from retirement accounts
The IRS allows hardship withdrawals from 401(k) plans, though a 10% early withdrawal penalty applies to participants under age 59½, plus ordinary income tax. Some 401(k) plans also permit loans up to $50,000 or 50% of the vested balance, whichever is less, under IRC §72(p).
Depleting retirement savings for current expenses carries long-term financial consequences that plaintiffs should weigh carefully.
Cost comparison
| Option | Typical cost range | Repayment required if case lost? | Credit check? |
| Pre-settlement funding | 27%–60% annualized (varies by funder) | No (non-recourse) | No |
| Personal loan | ~8%–18% APR | Yes | Yes |
| Credit card | ~18%–28% APR | Yes | Yes |
| 401(k) loan | Prime + 1%–2% | Yes (repay to own account) | No |
Negotiate medical liens
Florida plaintiffs can ask medical providers to treat on a letter of protection (LOP), deferring payment until settlement. This eliminates the need for outside funding for medical costs specifically.
Caution: Every option above except non-recourse funding requires repayment even if the case is lost. Plaintiffs should consult a licensed Florida attorney or financial advisor before taking on debt during pending litigation.
Rates and terms cited here are illustrative benchmarks — verify current figures with the issuing institution.
What Coin Abul independently reviewed
Claude Opus 4.6 is no longer available. Please switch to Claude Opus 5.5.
Frequently Asked Questions
Is pre-settlement funding in Florida considered a loan?
Florida does not classify pre-settlement funding as a loan. The Florida Supreme Court addressed this in Oasis Legal Finance Group v.
Coffman (2015), holding that litigation funding agreements are not loans under Florida’s usury statutes because repayment is contingent on the outcome of the case—if the plaintiff loses, nothing is owed back.
This distinction means Florida’s interest-rate caps under Chapter 687 do not apply.
Does Florida law require specific disclosures in pre-settlement funding contracts?
Yes.
Florida Statute §399.001 (the Consumer Protection for Litigation Financing Act, effective July 1, 2023) requires funding companies to disclose the funded amount, all fees and charges, the total amount owed at the end of each six-month period.
And the consumer’s right to cancel within five business days without penalty.
Applicants should read every line of the contract and verify these disclosures are present before signing.
How long does it typically take to receive pre-settlement funds in Florida?
Most Florida litigation funding companies advertise approval and disbursement within 24 to 48 hours after the applicant’s attorney provides case documentation, according to industry sources such as the American Legal Finance Association (ALFA).
Actual timing depends on how quickly the attorney responds to the funder’s request for case details. Applicants should confirm the timeline and any expedite fees directly with the funding company.
What types of Florida cases qualify for pre-settlement funding?
Funding companies in Florida most commonly advance funds on personal injury claims, including automobile accidents, slip-and-fall incidents, medical malpractice, and workers’ compensation disputes, per ALFA industry data.
Some funders also consider employment discrimination and wrongful-death claims.
Qualification generally requires an active lawsuit or filed claim and attorney representation—applicants should verify eligibility criteria with the specific funder, as each company sets its own case-type restrictions.
Related Reading
- Peachtree Pre Settlement Funding
- Pre Settlement Loans Without A Lawyer
- NY Tribeca Group
- Behind the Oasis Financial Lawsuit
- High Rise Financial Reviews – What You Need to Know
- All Pre-Settlement Funding Guides
- Florida Office of Financial Regulation (2024)
- Consumer Financial Protection Bureau — What Is a Lawsuit Loan? (2024)
- Florida Bar — Consumer Pamphlet on Litigation Funding (2024)
- U.S. Government Accountability Office — Third-Party Litigation Financing (2022)
- American Bar Association — Litigation Funding Ethics (2020)
- MedlinePlus (U.S. National Library of Medicine)
- National Cancer Institute
- U.S. Department of the Treasury
- U.S. Department of Justice – Civil Division