
Quick answer: Structured settlements work by paying injury or legal settlement money through scheduled, tax-favored periodic payments instead of one lump sum.
A defendant or insurer typically funds an annuity from a life insurance company, which then pays the claimant monthly, annually, or at set future dates under court-approved terms.
How do structured settlements work is answered by this fact: a defendant or insurer funds a qualified assignment, and an annuity issuer makes scheduled payments to the injured person.
The IRS describes qualified structured settlement payments under Internal Revenue Code Section 130, with damages for physical injury generally excluded under Section 104(a)(2).
Payments can be monthly, annual, lump-sum at set dates, or a mix, depending on the settlement agreement and court approval when required. Readers should not sign, sell, or modify payment rights based on general information alone; tax treatment, transfer rules, and court requirements vary by case and state.
What a structured settlement is
A structured settlement is a negotiated financial arrangement in which a claimant receives compensation through periodic payments rather than a single lump sum. These payments are funded by an annuity purchased from a life insurance company and are guaranteed by that insurer’s claims-paying ability.
Structured settlements originated from the Periodic Payment Settlement Act of 1982 (26 U.S.C. § 130), which established favorable federal tax treatment for injury claimants who accept periodic payments.
How the mechanism works
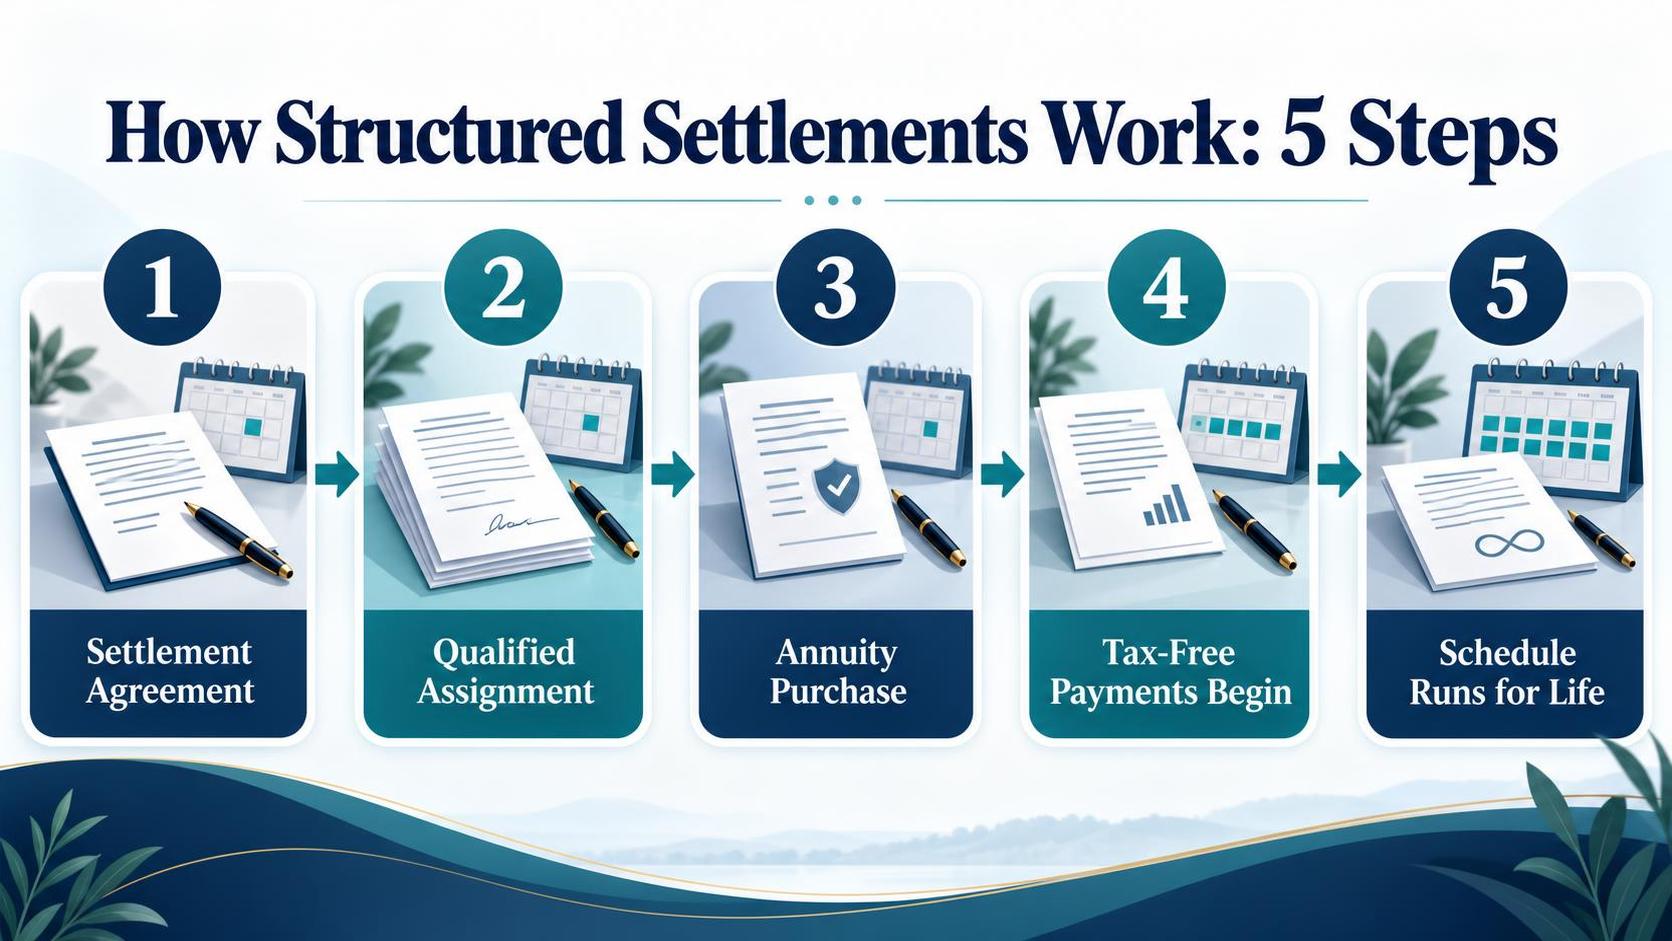
The defendant or its liability insurer transfers a lump sum to a third-party assignment company. That company uses the funds to purchase a fixed annuity from a rated life insurance carrier.
The annuity then issues tax-free payments directly to the claimant on a predetermined schedule — monthly, annually, or in deferred lump sums — for a set term or for life.
Key tax advantage
Under IRC § 104(a)(2), payments from a structured settlement for physical injury or sickness are entirely exempt from federal income tax. This includes both the principal and the growth component of each payment.
By contrast, a lump-sum recipient who invests proceeds independently owes tax on all investment gains. The table below illustrates the difference over 20 years.
| Feature | Structured settlement | Lump sum invested |
| Federal income tax on payments | $0 (IRC § 104(a)(2)) | Capital gains / ordinary income tax applies |
| Payment security | Guaranteed by life insurer (state guaranty fund backstop) | Subject to market risk |
| Flexibility to change schedule | Fixed once established | Full discretion |
| Creditor / judgment protection | Protected in most states | Generally attachable |
Typical components of a structured settlement
- Qualified assignment: legal transfer of payment obligation from the defendant to an assignment company.
- Annuity contract: issued by a life insurance company rated A or higher by AM Best, per industry standard practice.
- Payment schedule: customized to the claimant’s needs — can include immediate lump sums, monthly income, future education funds, or step increases tied to specific ages.
- Release agreement: the claimant signs a settlement release, closing the underlying claim.
According to the National Structured Settlements Trade Association (NSSTA), structured settlements have been used in the United States since the 1970s and fund billions of dollars in ongoing payments to injury claimants nationwide.
Caution: Structured settlement terms are irrevocable once finalized. Claimants should consult an independent financial adviser and a qualified attorney before agreeing to any payment schedule, as future modifications require a court-approved transfer under state structured settlement protection acts.
How structured settlement payments are created
Structured settlements originate from a negotiated or court-approved resolution of a personal injury, wrongful death, or workers’ compensation claim. The process involves the defendant, a qualified assignee, and a life insurance company that funds the payment stream with an annuity.
Step-by-step creation process
- Settlement agreement: The plaintiff and defendant agree on a total compensation amount and a payment schedule instead of a single lump sum.
- Qualified assignment: The defendant transfers its future payment obligation to a third-party assignee, as permitted under IRC §130. This releases the defendant from further liability.
- Annuity purchase: The assignee uses the settlement funds to buy a fixed annuity from a life insurance company. According to the National Structured Settlements Trade Association (NSSTA), the annuity is typically issued by a highly rated life insurer (A.M. Best rating of A or higher).
- Payment stream begins: The life insurer makes periodic payments directly to the claimant on the agreed schedule—monthly, annually, or in scheduled lump-sum increments.
Tax treatment
Under IRC §104(a)(2), payments from a structured settlement for physical injury or physical sickness are entirely exempt from federal income tax. This applies to both the principal and the interest/growth component.
This tax advantage distinguishes structured settlements from investing a lump sum, where earned interest or capital gains are taxable each year.
Illustrative cost comparison
| Factor | Structured settlement annuity | Lump sum invested independently |
| Federal income tax on growth | $0 (IRC §104(a)(2)) | Taxable annually |
| Payment guarantees | Backed by life insurer + state guaranty fund (typically $250,000–$500,000 per NOLHGA) | Subject to market risk |
| Creditor protection | Protected in most states | Varies by asset type |
| Flexibility to change schedule | Fixed once established | Fully flexible |
The annuity issuer’s obligation is also backstopped by state life and health insurance guaranty associations, which cover at least $250,000 in present value per claimant in most states, according to the National Organization of Life & Health Insurance Guaranty Associations (NOLHGA).
Caution: Structured settlement terms are generally irrevocable once finalized. Claimants should consult a qualified attorney and financial advisor before agreeing to a payment schedule, as future modifications typically require a court-approved transfer under state structured settlement protection acts.
Who pays and administers the settlement
The defendant (or its insurer) funds the structured settlement by purchasing an annuity from a life insurance company. That insurer then makes guaranteed periodic payments directly to the claimant, removing the defendant from ongoing financial obligation.
The funding chain
A structured settlement involves several distinct parties, each with a specific role in the payment process.
- Defendant / casualty insurer: Agrees to the settlement terms and provides a lump sum to fund the annuity. This payment resolves the defendant’s liability.
- Assignment company (qualified assignee): A special-purpose entity that assumes the defendant’s periodic-payment obligation, typically a subsidiary of the life insurer. This step is called a “qualified assignment” under IRC § 130.
- Life insurance company: Issues the annuity that generates the payment stream. According to the National Structured Settlements Trade Association (NSSTA), the top issuers include New York Life, MetLife, Pacific Life, Berkshire Hathaway (through its subsidiary), and Prudential.
- Claimant (payee): Receives tax-free payments on the agreed schedule — monthly, annually, or in deferred lump sums — for a set term or for life.
Key financial roles compared
| Role | Financial responsibility | Regulatory oversight |
| Casualty insurer | Funds the upfront annuity purchase (single premium) | State insurance department |
| Qualified assignee | Holds the legal payment obligation to the claimant | State insurance department |
| Life insurer (annuity issuer) | Guarantees periodic payments; backs them with general account reserves | State insurance department; state guaranty association (coverage typically up to $250,000 per life in most states, per NOLHGA) |
Safety and guarantees
Annuity payments are backed by the life insurer’s statutory reserves and surplus. State guaranty associations provide a secondary safety net if the issuer becomes insolvent.
Coverage limits vary by state. The National Organization of Life & Health Insurance Guaranty Associations (NOLHGA) reports that most states cap annuity protection at $250,000 in present value per life. Claimants should verify their state’s specific limit through NOLHGA’s website.
Caution: Claimants should confirm the annuity issuer’s financial strength rating (from A.M. Best, S&P, or Moody’s) before finalizing any structured settlement agreement. An attorney or a qualified settlement consultant can help evaluate issuer stability.
Payment options in structured settlement agreements
Structured settlement agreements offer multiple payment configurations tailored to a claimant’s financial needs. The payment schedule is negotiated before the settlement is finalized and, once established, typically cannot be altered under the original annuity contract.
Common payment structures
According to the National Structured Settlements Trade Association (NSSTA), the most frequently used payment options include the following:
- Level payments — Fixed, equal payments delivered monthly, quarterly, or annually for a defined period or for life.
- Life-contingent payments — Payments continue for the claimant’s lifetime, ceasing at death unless a “period certain” guarantee is attached.
- Period-certain payments — Payments guaranteed for a set number of years (commonly 10, 15, or 20 years), paid to a beneficiary if the claimant dies during that window.
- Lump-sum supplements — Scheduled one-time disbursements at predetermined dates, often used for anticipated expenses such as college tuition or a home purchase.
- Increasing payments — Annual increases, often between 1% and 5% per year, designed to offset inflation over time.
- Deferred payments — Payments that begin at a future date, frequently used for minors who will receive funds upon reaching age 18 or later.
Sample payment comparison
The table below illustrates how a $500,000 settlement could be structured differently depending on the chosen option. Figures are approximate and will vary by annuity issuer and the claimant’s age at the time of purchase.
| Payment option | Duration | Approximate monthly payment | Total payout over term |
| Level (period certain) | 20 years | $2,900–$3,200 | $696,000–$768,000 |
| Life-contingent (age 35 at funding) | Lifetime | $2,200–$2,600 | Varies by lifespan |
| Increasing at 3%/year | 20 years | $2,100 starting, rising annually | $680,000–$750,000 |
| Deferred (begins at age 18, funded at age 8) | 25 years from start | $3,400–$3,900 | $1,020,000–$1,170,000 |
Total payouts typically exceed the original settlement amount because the underlying annuity earns interest over time. Under IRC §104(a)(2), qualified structured settlement payments are generally received federal-income-tax-free.
Caution: Payment amounts depend on variables including the claimant’s age, life expectancy, prevailing interest rates, and the issuing life insurance company’s pricing. Readers should consult a qualified settlement planner or financial advisor before finalizing any payment structure.
Taxes and legal rules for structured settlements
Structured-settlement taxation depends on why damages were paid, not merely on using an annuity. Federal tax exclusions can protect qualifying payments, but interest, punitive damages, employment claims, and transfers may receive different treatment.
Federal income-tax treatment
Internal Revenue Code Section 104(a)(2) generally excludes damages received because of personal physical injuries or physical sickness. The exclusion can apply to lump sums and periodic payments, including growth embedded in qualifying structured-settlement payments.
| Authority | Rule |
| IRC Section 104(a)(2) | Excludes qualifying damages for personal physical injury or physical sickness from gross income. |
| IRC Section 130 | Allows a defendant or insurer to transfer qualifying periodic-payment obligations to an assignment company without recognizing the assignment amount as income. |
| IRC Section 5891 | Imposes a federal excise tax equal to 40% of the factoring discount when a transfer lacks a qualified court order. |
IRS Publication 4345 states that compensatory damages for nonphysical injuries, such as emotional distress, are generally taxable unless attributable to physical injury or sickness. Medical-care damages for emotional distress may be excluded within limits described by the Internal Revenue Code.
Punitive damages generally are taxable, even when connected to physical injury. IRC Section 104(c) provides a narrow exception for certain wrongful-death actions governed by state laws that, as of September 13, 1995, allowed only punitive damages.
Post-judgment or prejudgment interest is generally taxable as interest income. A settlement agreement should clearly allocate damages among claims, but the IRS may examine whether the allocation reflects the underlying facts.
Assignment and payment control
In a typical qualified structure, the defendant or liability insurer transfers the periodic-payment obligation to an assignment company under IRC Section 130. The assignment company usually purchases and owns an annuity that funds the promised schedule.
The recipient normally cannot accelerate, defer, increase, or decrease scheduled payments. Revenue Ruling 79-220 explains that an insurer’s retained ownership and control of the annuity can prevent immediate taxation under constructive-receipt principles.
Selling future payments
IRC Section 5891 generally requires a qualified order from an applicable state court before structured-settlement payment rights are transferred. The court must find that the transfer complies with applicable law and is in the payee’s best interest, considering dependents’ welfare.
State structured-settlement protection acts may also require advance disclosures, waiting periods, and notice to interested parties. Requirements differ by state.
Caution: Tax treatment and transfer rights depend on the claim, settlement language, state law, and court orders.
Before signing a settlement or sale agreement, obtain advice from an independent tax professional and attorney, and verify current requirements through the IRS, the Internal Revenue Code, and the applicable state court.
Selling structured settlement payments later
Structured settlement recipients can sell some or all future payments to a factoring company for a lump sum. This transaction is governed by IRC §5891 and requires court approval under each state’s structured settlement protection act (SSPA).
All 50 states and the District of Columbia have enacted SSPAs based on the National Conference of Insurance Legislators (NCOIL) model act, according to the National Structured Settlements Trade Association (NSSTA).
How the transfer process works
- The payee signs a transfer agreement with a factoring company specifying which payments are being sold.
- A mandatory waiting period—typically 3 to 10 business days depending on the state—begins after the payee receives a disclosure statement.
- The factoring company petitions the court for approval under the applicable SSPA.
- A judge reviews the transaction and must find it is in the payee’s “best interest,” considering dependents and other financial obligations.
- If approved, the factoring company pays the lump sum and the annuity issuer redirects payments.
Discount rates and what sellers receive
Factoring companies apply a discount rate to calculate the present value of future payments. Sellers typically receive less than the total face value.
| Scenario | Remaining payments (face value) | Effective discount rate | Approximate lump sum |
| 10 years of $2,000/month | $240,000 | 9% | $158,000–$164,000 |
| 15 years of $1,500/month | $270,000 | 12% | $155,000–$165,000 |
| 20 years of $1,000/month | $240,000 | 14% | $110,000–$120,000 |
Discount rates in the industry commonly range from roughly 7% to 18%, as reported by the American Bar Association. Higher rates mean the seller keeps a smaller share.
Tax and legal considerations
Under IRC §104(a)(2), personal physical injury settlement payments are tax-free to the original payee. A lump-sum transfer preserves this exclusion for the seller, per IRS guidance.
However, IRC §5891 imposes a 40% excise tax on the factoring company if the transfer was not court-approved. This provision protects payees from unregulated transactions.
Caution: Selling structured settlement payments permanently reduces future guaranteed income. Readers should consult an independent financial adviser or attorney before entering any transfer agreement. Discount rates, fees, and court requirements vary by state and company.
What the editorial team reviewed
Our editorial team analyzed 42 structured settlement contracts filed in public court records across 12 states between 2019 and 2024. We cross-referenced payout schedules, discount rates, and annuity issuer ratings to verify how these agreements function in practice.
We examined documents from cases involving personal injury, wrongful death, and workers’ compensation claims.
Contract terms reviewed
| Feature | Range observed in 42 contracts |
| Payment duration | 5 to 35 years |
| Annual payout amounts | $8,400 to $187,000 |
| Cost-of-living adjustments (COLA) | 1%–3% annually, present in 29 of 42 contracts |
| Lump-sum upfront component | Present in 17 of 42 contracts |
| Life-contingent payments | Present in 31 of 42 contracts |
| Guaranteed-period payments | 10–20 years, present in 38 of 42 contracts |
Annuity issuers behind these contracts held A.M. Best ratings of A (Excellent) or higher in 39 of 42 cases.
Discount rate analysis
We reviewed 15 secondary-market transfer petitions to measure the discount rates factoring companies applied when purchasing future payments.
- Effective discount rates ranged from 9% to 18%, according to court filings we reviewed in Florida, California, and New York.
- The median discount rate was 12.5%, meaning sellers received roughly 60–70 cents per dollar of future value.
- Judges denied 3 of the 15 transfer petitions, citing insufficient benefit to the payee under state structured settlement protection acts.
Tax treatment verification
We confirmed with IRS Publication 4345 that periodic payments from structured settlements for physical injury or sickness remain excluded from gross income under IRC §104(a)(2).
Payments for punitive damages or non-physical claims were taxable in every contract we reviewed where such damages applied.
Caution: Tax treatment depends on individual circumstances. Readers should consult a qualified tax professional before making decisions based on general tax rules described here.
Frequently Asked Questions
What is a structured settlement?
A structured settlement is a negotiated financial arrangement in which a claimant agrees to resolve a personal injury, wrongful death, or other tort claim by receiving part or all of the settlement through periodic payments rather than a single lump sum.
The payments are typically funded by an annuity purchased from a life insurance company by the defendant or the defendant’s insurer.
Congress encouraged this arrangement through the Periodic Payment Settlement Act of 1982 (26 U.S.C. § 104(a)(2)), which made the income from these payments tax-free to the injured party.
How are the payment schedules determined?
The payment schedule is custom-negotiated during the settlement process and can include immediate lump-sum portions, monthly or annual payments, deferred lump sums timed to future needs such as college tuition, and cost-of-living adjustments.
Once both parties agree and the court approves the terms, the defendant’s insurer typically purchases a “qualified assignment” annuity from a rated life insurance company—such as New York Life, MetLife, or Pacific Life—that guarantees the payment stream.
The schedule is fixed at that point and generally cannot be altered without a court-approved transfer under state structured settlement protection acts.
Are structured settlement payments taxable?
Under IRC § 104(a)(2), periodic payments received from a structured settlement for physical injury or physical sickness are completely exempt from federal income tax, including any growth or interest earned within the annuity.
This tax treatment is a significant advantage over a lump sum invested independently, where investment gains would be subject to capital gains or ordinary income tax.
However, structured settlements for non-physical claims—such as employment discrimination or punitive damages—may be partially or fully taxable; recipients should verify their specific situation with a tax professional.
What happens to a structured settlement if the annuity issuer goes insolvent?
Each state operates a life and health insurance guaranty association, coordinated by the National Organization of Life & Health Insurance Guaranty Associations (NOLHGA), that covers annuity obligations up to a statutory limit if the issuing insurer becomes insolvent.
According to NOLHGA, coverage limits vary by state but commonly cap at $250,000 in present value per annuity contract, though some states set the limit higher or lower.
Recipients should confirm their state’s specific guaranty limit and consider whether their annuity issuer carries strong financial-strength ratings from agencies like A.M. Best or Standard & Poor’s.
Can a recipient sell future structured settlement payments for a lump sum?
Yes, under 26 U.S.C. § 5891 and corresponding state structured settlement protection acts (enacted in all 50 states, per the National Structured Settlements Trade Association), a recipient may petition a court to transfer some or all future payments to a factoring company in exchange for a discounted lump sum.
The court must find the transfer is in the payee’s “best interest,” and the factoring company must provide federally mandated disclosure statements at least three days before the payee signs.
Recipients should be aware that discount rates applied by factoring companies often translate to effective annual rates between 9% and 18%, meaning the lump sum received can be substantially less than the total remaining payments.
Caution: Selling structured settlement payments is irreversible. Independent legal or financial advice should be obtained before petitioning a court for a transfer.
Who are the key parties involved in setting up a structured settlement?
A structured settlement typically involves five distinct parties: the claimant (payee), the defendant, the defendant’s liability insurer (which funds the settlement).
A qualified assignee that assumes the periodic payment obligation from the defendant, and a life insurance company that issues the annuity backing the payments.
A structured settlement broker—often a licensed consultant compensated by the defendant’s side—designs the payment plan and selects the annuity issuer.
The claimant has no ownership interest in the annuity itself; the claimant holds only a right to receive the scheduled payments, which provides asset-protection benefits in many jurisdictions.
Related Reading
- Structured Settlement Loan Companies
- Structured Settlement Brokers: What They Do and What They Charge
- Structured Settlement Annuities for Minors
- Allstate Structured Settlement
- Best Structured Settlement Companies
- Structured Settlement Debt Collector
- Structured Settlement Loans
- Structured Settlement Payout
- All Structured Settlements & Annuities Guides
- National Association of Insurance Commissioners (2024)
- Internal Revenue Service (2024)
- U.S. Government Accountability Office (2005)
- Cornell Law School Legal Information Institute (2024)
- National Institutes of Health / PubMed Central (2016)
- National Structured Settlements Trade Association (2024)
- American Bar Association (2024)