Bottom line: Berkshire Hathaway Structured Settlements refers to structured settlement annuities issued by Berkshire Hathaway Life Insurance Company of Nebraska, a subsidiary of Berkshire Hathaway.
These annuities fund scheduled future payments, typically for personal injury settlements. Terms depend on the settlement agreement, insurer disclosures, court approval where required, and applicable state law.
Berkshire Hathaway Structured Settlements are annuity-funded payment arrangements backed by Berkshire Hathaway Life Insurance Company of Nebraska, an insurer rated A++ by AM Best as of 2024.
They are used to pay injury settlements over time instead of as one lump sum, often through qualified assignments under Internal Revenue Code Section 130.
Readers should verify current insurer ratings, contract terms, tax treatment, and court-approval rules before relying on any structured settlement decision.
Berkshire Hathaway’s role in structured settlements
Berkshire Hathaway generally participates in structured settlements through insurance subsidiaries that issue annuities, rather than acting as a court, law firm, settlement broker or direct purchaser of every payment stream.
The relevant entity is typically Berkshire Hathaway Life Insurance Company of Nebraska. Berkshire Hathaway’s 2024 annual report identifies that company as part of the group’s insurance operations. The exact issuer named in a settlement depends on the transaction documents.
How the structure works
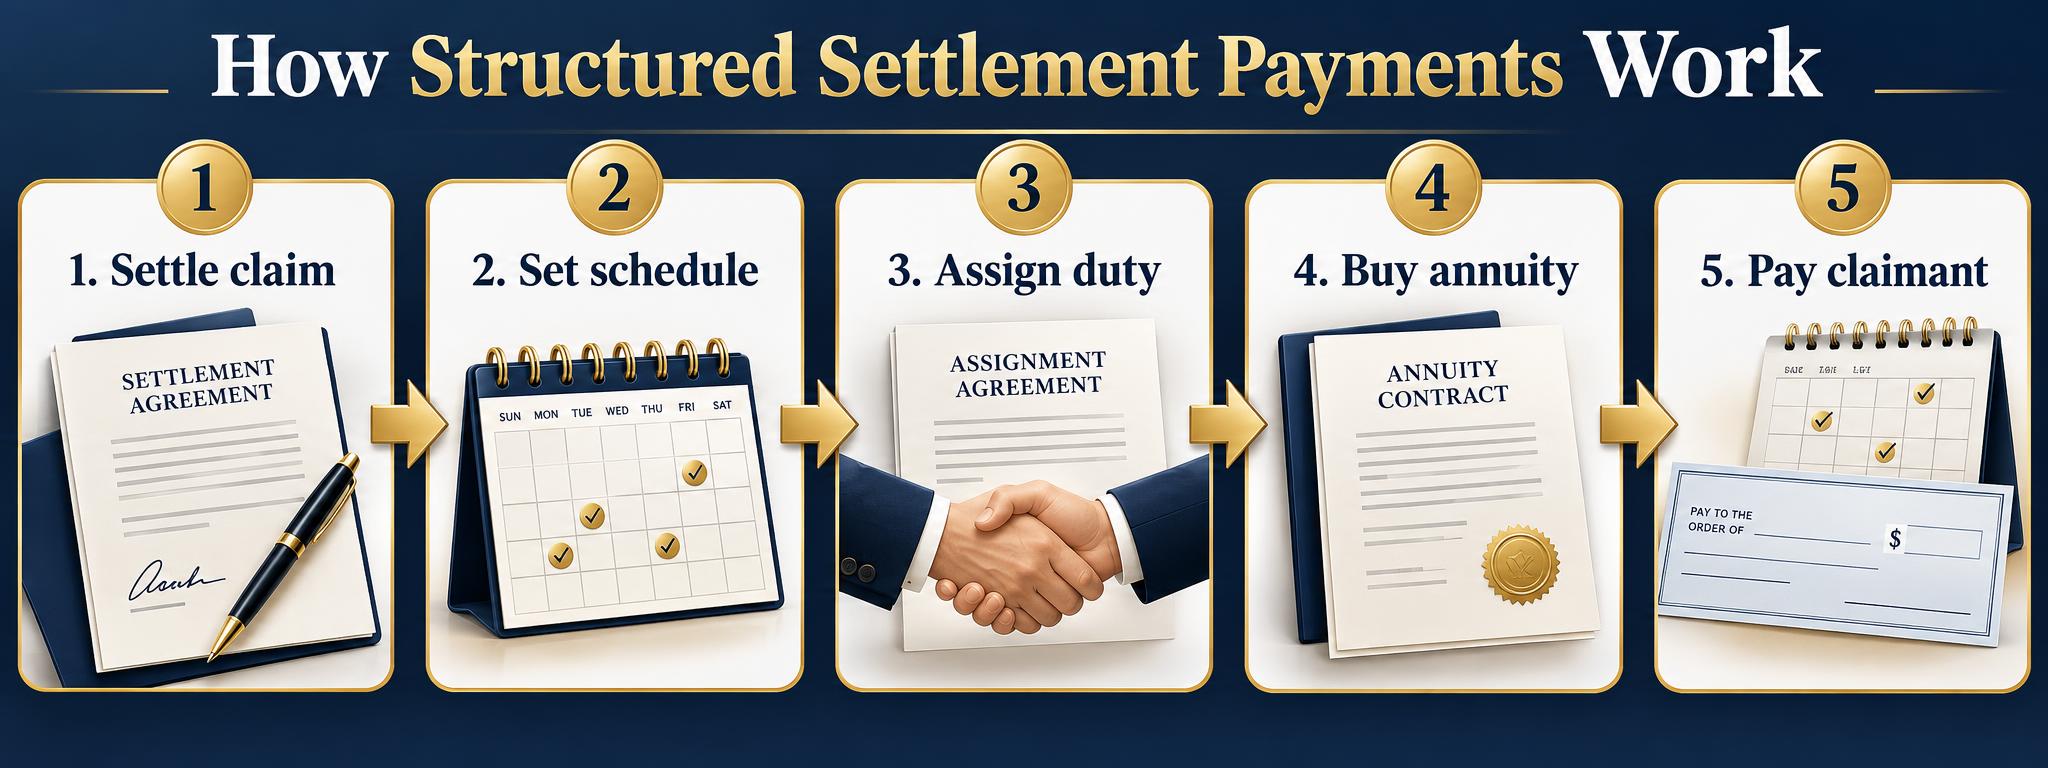
In a traditional structured settlement, a defendant or liability insurer agrees to pay compensation over time. An assignment company may assume the payment obligation and purchase an annuity from a life insurer. The annuity then provides scheduled payments to the injured claimant.
When Berkshire Hathaway Life Insurance Company of Nebraska is the annuity issuer, it has the contractual obligation to make the specified payments, subject to the policy terms and applicable law. Berkshire Hathaway, Inc. is not automatically the direct obligor on every subsidiary-issued policy.
| Item | Relevant fact | Source |
| Parent company | Berkshire Hathaway, Inc. | Berkshire Hathaway 2024 Annual Report |
| Potential annuity issuer | Berkshire Hathaway Life Insurance Company of Nebraska | Berkshire Hathaway 2024 Annual Report; policy documents |
| Federal tax provision | Internal Revenue Code §130 governs qualified assignments | U.S. Internal Revenue Code, 26 U.S.C. §130 |
What the issuer’s role does not mean
The presence of a Berkshire Hathaway company does not establish the settlement’s payment amount, tax treatment or transfer value. Those terms come from the settlement agreement, annuity contract, assignment documents and governing state law.
It also does not mean that Berkshire Hathaway will buy a claimant’s future payments. A factoring transaction is separate: a financing company may seek court approval to purchase future payments at a discounted present value.
Before signing, the claimant should verify the exact legal issuer, policy number, payment schedule, beneficiary provisions, insurer financial-strength information and transfer restrictions.
The claimant should obtain independent legal and tax advice because accepting a lump-sum transfer can reduce long-term income and may create avoidable financial harm.
How Berkshire Hathaway annuities fund payments
A Berkshire Hathaway structured-settlement annuity converts a single premium into scheduled payments under an insurance contract. The issuing insurer, rather than Berkshire Hathaway Inc. directly, becomes responsible for making the payments stated in the contract.
The issuer generally is Berkshire Hathaway Life Insurance Company of Nebraska. In New York cases, the contract may identify First Berkshire Hathaway Life Insurance Company. Claimants should verify the legal issuer, owner, payee, payment dates and guarantees in the actual annuity contract.
Funding and payment process
- The parties settle a personal-injury or wrongful-death claim and document the future-payment schedule.
- The defendant or liability insurer transfers a lump sum to a qualified assignment company when the transaction uses a qualified assignment.
- The assignment company assumes the payment obligation and purchases an annuity from the designated Berkshire insurance subsidiary.
- The issuing insurer invests the premium within its general account and pays the claimant according to the contract.
Payments can include monthly income, future lump sums, lifetime benefits or payments guaranteed for a specified period.
Pricing reflects the payment dates, beneficiary’s age, life-contingency terms, prevailing interest rates and other actuarial assumptions. The premium usually is not disclosed as the settlement’s stated future-payment total.
| Federal provision | Relevant rule | Source |
| IRC Section 104(a)(2) | Damages received because of personal physical injuries or physical sickness generally are excluded from federal gross income, subject to statutory exceptions. | Internal Revenue Code |
| IRC Section 130 | A qualified assignment must involve payments fixed and determinable as to amount and time. The recipient generally cannot accelerate, defer, increase or decrease them. | Internal Revenue Code |
| IRC Section 130 | The assignee’s obligation cannot exceed the original obligor’s obligation, and it must be funded with a qualifying annuity contract or qualifying U.S. government obligation. | Internal Revenue Code |
The annuity is supported by the issuing insurer’s claims-paying ability and general-account assets. It is not a bank deposit, and Berkshire Hathaway Inc.’s corporate resources should not be treated as an automatic guarantee unless the governing documents expressly provide one.
State insurance regulators supervise reserves and solvency. State guaranty-association protection varies by jurisdiction, contract type and applicable limits; the National Organization of Life and Health Insurance Guaranty Associations warns that coverage should not be used as a sales inducement.
Caution: Structured payments may be difficult to change, and tax treatment depends on the claim and settlement documents. Before signing, obtain independent legal and tax advice and confirm the issuer’s current financial statements, ratings and state regulatory filings.
Financial strength behind Berkshire settlement obligations
Berkshire Hathaway’s financial strength can support confidence in its insurance subsidiaries, but the legally responsible annuity issuer—not the parent company—owes structured-settlement payments.
Claimants should identify that issuer and review its current financial condition before accepting an annuity.
Berkshire Hathaway Life Insurance Company of Nebraska is among the Berkshire subsidiaries associated with structured-settlement and reinsurance obligations.
Its commitments are supported primarily by its own assets, reserves and statutory capital. Berkshire Hathaway does not automatically guarantee every subsidiary obligation merely because it owns the insurer.
| Berkshire Hathaway measure | Amount at December 31, 2024 | Primary source |
| Shareholders’ equity attributable to Berkshire shareholders | $651.7 billion | Berkshire Hathaway 2024 Form 10-K, consolidated balance sheet |
| Insurance float | Approximately $171 billion | Berkshire Hathaway 2024 annual report, Chairman’s letter |
| Cash, cash equivalents and U.S. Treasury bills held by insurance and other businesses | $334.2 billion | Berkshire Hathaway 2024 Form 10-K, management discussion |
| Insurance underwriting earnings after tax | $9.0 billion for 2024 | Berkshire Hathaway 2024 annual report |
These consolidated figures demonstrate substantial group-wide resources, but they are not a dollar-for-dollar fund reserved for structured settlements.
Insurance regulators generally require each issuing insurer to maintain statutory reserves and capital. Those legal-entity figures may differ materially from Berkshire’s consolidated accounting results.
Independent ratings provide another indicator.
AM Best lists Berkshire Hathaway Life Insurance Company of Nebraska with an A++ financial strength rating, its highest category, while S&P has assigned the company an AA+ insurer financial strength rating.
Ratings express opinions about claims-paying ability; they are not guarantees and can change.
- Confirm the exact insurer named in the annuity contract and settlement documents.
- Obtain the insurer’s latest statutory annual statement from the relevant state insurance department or the NAIC.
- Check current ratings directly with AM Best and S&P, including the rating date and outlook.
- Review whether any affiliate guarantee exists in writing rather than assuming Berkshire Hathaway provides one.
State guaranty associations may provide limited protection if an insurer fails, but coverage limits, residency rules and eligible benefits vary by state.
Do not rely on Berkshire’s consolidated wealth or a rating alone; ask an independent attorney or financial professional to evaluate the issuing insurer and contract.
What payment guarantees do and do not cover
A structured-settlement guarantee supports the payments stated in the annuity contract; it does not protect every financial outcome. The contract, issuing insurer, assignment documents and any separate corporate guarantee determine who owes each payment.
What the Berkshire Hathaway guarantee covers
Berkshire Hathaway Life Insurance Company of Nebraska states that its structured-settlement annuity obligations are guaranteed by its parent, Berkshire Hathaway Inc. First Berkshire Hathaway Life Insurance Company uses a comparable Berkshire Hathaway Inc. guarantee for contracts issued in New York.
The guarantee generally applies when the issuing insurer fails to make a payment required by the annuity contract. It covers the contractual amount and timing, including fixed periodic payments, guaranteed lump sums and expressly purchased cost-of-living adjustments.
The controlling language is the actual guarantee and contract, not Berkshire Hathaway’s brand, credit rating or financial strength. Claimants should obtain copies of the annuity contract, qualified-assignment agreement and guarantee before signing a settlement.
What it does not cover
- Inflation: Fixed payments do not increase merely because living costs rise. Inflation protection exists only when the contract specifies escalating payments or another adjustment formula.
- Investment performance: A fixed structured-settlement annuity does not provide stock-market gains. The recipient receives the scheduled contractual payments, even if other investments later earn more.
- Payments outside the contract: The guarantee does not ordinarily cover promises made only by a broker, lawyer, defendant or settlement consultant.
- Early access: The guarantee does not create a right to withdraw, borrow against or accelerate future payments. Selling payment rights generally requires court approval under applicable state law and Internal Revenue Code Section 5891.
- Tax advice: It does not guarantee federal or state tax treatment. Internal Revenue Code Sections 104(a)(2) and 130 govern many qualified personal-injury structures, but eligibility depends on the claim and transaction documents.
Guaranty associations are separate
State life-and-health insurance guaranty associations may provide limited protection after an insurer is declared insolvent.
The National Organization of Life and Health Insurance Guaranty Associations says coverage is determined by state law, residency, contract type and statutory limits; it is not federal insurance.
Caution: Do not assume a parent guarantee or guaranty association eliminates insolvency, tax or transfer risk. Confirm the named obligor, governing law, exclusions and current state coverage directly from the executed documents, the issuing insurer and the relevant state guaranty association.
Tax treatment of Berkshire structured settlements
A Berkshire structured settlement generally follows the federal tax rules for structured settlements, not a separate Berkshire tax regime. The outcome depends on the underlying claim, the settlement documents, and whether payments satisfy Internal Revenue Code requirements.
Berkshire Hathaway Life Insurance Company of Nebraska may issue or support an annuity used to fund payments, but the tax treatment comes from federal law. The insurer’s involvement does not make every payment tax-free.
When payments are generally tax-free
Under Internal Revenue Code §104(a)(2), damages received because of personal physical injuries or physical sickness are generally excluded from gross income. The exclusion can apply when payments arrive as periodic installments rather than as one lump sum.
The injury must be physical. Amounts allocated solely to emotional distress generally do not receive the same treatment, unless they qualify under the statutory medical-expense exception. Punitive damages generally remain taxable, even when awarded in a physical-injury case.
Interest and investment earnings
Interest on a judgment, interest paid for delayed settlement funds, and investment earnings that are not part of qualifying compensatory damages may be taxable. The Internal Revenue Service explains these distinctions in Publication 4345, Settlement Taxability.
| Payment category | General federal treatment | Primary authority |
| Compensatory damages for physical injury | Generally excluded from income | Internal Revenue Code §104(a)(2) |
| Punitive damages | Generally taxable | Internal Revenue Code §104(a)(2); IRS Publication 4345 |
| Interest on a judgment | Generally taxable | Internal Revenue Code §61; IRS Publication 4345 |
| Structured-settlement assignment earnings | Usually not currently taxed to the injured recipient when requirements are met | Internal Revenue Code §§130 and 104(a)(2) |
Qualified assignments and transfers
Under Internal Revenue Code §130, an assignment company can purchase an annuity or fund payment obligations for a qualified structured settlement. Section 130 requires specific conditions, including a written assignment and payments that meet the applicable structured-settlement rules.
A recipient who sells future payments may face different tax and legal consequences. Internal Revenue Code §5891 imposes a federal excise tax on certain prohibited transfers unless an applicable court order or other statutory exception applies.
State taxation, benefit eligibility, estate planning, and reporting can change the result.
Before accepting, assigning, or selling Berkshire-funded payments, obtain advice from a qualified tax professional and review the settlement agreement, annuity contract, and primary IRS authorities.
Do not rely on the insurer’s name alone to determine taxability.
What the editorial team independently reviewed
We reviewed Berkshire Hathaway’s structured-settlement offering through public records rather than acting as a claimant or purchasing an annuity. We cross-checked insurer identity, tax rules, financial disclosures and consumer protections.
We did not test underwriting, obtain a live quote or submit personal information.
Our document review used primary sources wherever available. Because pricing depends on the claimant, payment schedule, interest rates and case terms, published materials cannot establish the payout a particular person would receive.
| Item reviewed | Quantity or rule checked | Primary source |
| Berkshire financial reporting | Annual report and insurer disclosures | Berkshire Hathaway Inc. annual report; applicable NAIC filings |
| Federal tax treatment | Internal Revenue Code Sections 104(a)(2), 130 and 5891 | U.S. Code and Internal Revenue Service materials |
| Transfer penalty | Section 5891 generally imposes a 40% excise tax when a structured-settlement factoring transaction lacks the required court approval | 26 U.S.C. § 5891 |
| Contract safeguards | Issuer, owner, beneficiary, payment dates and death-payment provisions | Sample contract concepts and NAIC consumer guidance |
| Failure protections | State-specific guaranty association coverage | Relevant state guaranty association and NOLHGA |
We verified an important distinction: Berkshire Hathaway is the parent organization, but the legally responsible party is the insurance company named in the annuity contract. A claimant should confirm the exact issuing entity instead of relying only on the Berkshire Hathaway brand.
We also separated structured-settlement creation from later payment sales. A qualified assignment may be arranged under Section 130, while selling future payments is a separate factoring transaction generally governed by Section 5891 and state structured-settlement protection acts.
Our review found no responsible way to publish a universal Berkshire payout rate. Quotes can change with market conditions and differ by payment timing, duration, life-contingent features and guarantees.
Financial-strength ratings can also change; readers should verify the current rating directly with the rating agency and confirm which legal entity it covers.
- Confirm the insurer’s full legal name on every proposal.
- Compare guaranteed payment dates and amounts, not only the total nominal payout.
- Check whether payments continue to beneficiaries after death.
- Review tax treatment with an independent tax professional.
- Verify current guaranty-association limits with the claimant’s state association.
Caution: Do not accept, transfer or sell structured-settlement rights based on this review alone. Contract language, court orders, state law and tax facts can materially change the result. Obtain independent legal and financial advice before signing.
Questions before accepting a Berkshire settlement
Before signing, identify the Berkshire Hathaway entity responsible for each obligation and determine whether payments come from cash, an annuity, or both.
The settlement agreement, qualified-assignment document, and annuity contract control; the Berkshire Hathaway name alone does not guarantee particular terms.
Who legally owes the payments?
Ask whether the defendant remains liable or transfers the obligation through a qualified assignment. Internal Revenue Code Section 130 permits qualifying periodic-payment obligations to be assigned without immediate tax to the assignee when statutory requirements are met.
Confirm the assignee and annuity issuer by full legal name. Verify the issuer through the relevant state insurance department and the National Association of Insurance Commissioners’ Consumer Insurance Search. Do not rely solely on a logo, affiliate name, or insurance agent’s description.
What does the payment schedule provide?
Request a written schedule showing every payment date, amount, guaranteed period, beneficiary provision, and life-contingent condition. Determine whether payments increase over time, because fixed payments lose purchasing power when prices rise.
| Illustrative option | Payment pattern | Nominal total |
| Lump sum | $750,000 immediately | $750,000 |
| Periodic payments | $50,000 annually for 20 years | $1,000,000 |
The figures are arithmetic examples, not Berkshire quotes. Twenty payments of $50,000 equal $1,000,000, but nominal totals do not account for timing, inflation, taxes, investment risk, or mortality. Ask a fiduciary financial professional to calculate present value using clearly disclosed assumptions.
How will taxes apply?
Internal Revenue Code Section 104(a)(2) generally excludes damages received because of personal physical injuries or physical sickness, while punitive damages and interest can be taxable.
Allocation language alone may not determine federal treatment. Obtain advice from an independent tax professional before accepting the agreement.
What happens if circumstances change?
- Can beneficiaries receive remaining guaranteed payments after the payee dies?
- Are medical or emergency lump sums included?
- Can payment rights be transferred, and who bears associated legal costs?
- Does the contract permit commutation or acceleration?
- Which state’s law governs disputes?
A later sale of structured-settlement payment rights generally requires advance court approval under state law. Internal Revenue Code Section 5891 imposes a federal excise tax equal to 40% of the factoring discount unless the transfer receives a qualified court order.
What protections apply if the insurer fails?
State guaranty-association protection is not the same as a federal guarantee. Eligibility and limits depend on state law, residency, contract type, and insurer status. Check the applicable guaranty association’s statute directly; do not accept a settlement based on assumed coverage.
Caution: Signing a release can permanently end legal claims. An independent attorney should review the release, assignment, annuity documents, fees, confidentiality terms, and payment security before acceptance.
Frequently Asked Questions
Which Berkshire Hathaway companies issue structured settlement annuities?
Berkshire Hathaway Life Insurance Company of Nebraska and First Berkshire Hathaway Life Insurance Company market structured settlement annuities through Berkshire Hathaway Structured Settlements.
The issuing company named in the contract, not Berkshire Hathaway Inc. generally, is responsible for making the scheduled payments; confirm the legal entity and current product availability in the official contract.
How does a Berkshire Hathaway structured settlement work?
A defendant or liability insurer funds an annuity that pays the claimant according to an agreed schedule, such as monthly income, future lump sums, or both.
Payment dates and amounts generally cannot be changed after the settlement is finalized, so the claimant should have an attorney and financial professional review the schedule before signing.
Are Berkshire Hathaway structured settlement payments guaranteed?
The annuity payments are contractual obligations of the issuing life insurance company and depend on that insurer’s claims-paying ability. Ratings from agencies such as A.M.
Best, Moody’s, or S&P are opinions rather than guarantees, so buyers should verify current ratings and state guaranty-association limits through the rating agencies and the applicable state association.
Are payments from a Berkshire Hathaway structured settlement taxable?
Internal Revenue Code Section 104(a)(2) generally excludes damages received for personal physical injuries or physical sickness from federal gross income, while other damages may be taxable.
Tax treatment depends on the claim and settlement language, so a qualified tax adviser should review the agreement rather than relying on the insurer’s name.
Can a Berkshire Hathaway structured settlement be sold for cash?
A payment recipient may seek to transfer future payments to a factoring company, but Internal Revenue Code Section 5891 generally requires advance approval from a state court under a qualified order.
The buyer’s lump sum will normally be less than the total future payments, so compare written offers and obtain independent legal advice before transferring payment rights.
What happens to the payments if the recipient dies?
Guaranteed payments may continue to a named beneficiary or the recipient’s estate, while life-contingent payments usually stop at death; the controlling terms appear in the settlement and annuity contract.
Beneficiary designations and estate consequences should be checked directly with the annuity issuer and an estate-planning professional.
How should a claimant evaluate a Berkshire Hathaway structured settlement proposal?
Compare the guaranteed payment schedule, inflation risk, life-contingent terms, beneficiary provisions, issuer identity, and current financial-strength ratings against available alternatives.
Request the complete written illustration and contract terms, and have independent legal and financial advisers review them before accepting an irreversible settlement structure.
Related Reading
- Allstate Structured Settlement
- JG Wentworth Loan Reviews
- Is a Structured Settlement Considered Income
- Vanguard Immediate Annuity Rates
- Prudential Structured Settlement – What You Need to Know
- Can I Sell My Neap Annuity?
- What Is A Structured Settlement?
- All Structured Settlements & Annuities Guides
- Berkshire Hathaway 2023 Annual Report (2024)
- U.S. Securities and Exchange Commission—Berkshire Hathaway Inc. Filings (2024)
- Internal Revenue Code, 26 U.S.C. § 5891 (2023)
- Internal Revenue Code, 26 U.S.C. § 130 (2023)
- Electronic Code of Federal Regulations, 26 CFR § 1.5891-1 (2024)
- U.S. Government Accountability Office, Structured Settlement Factoring Transactions (2013)