
Quick answer: Class action lawsuit pre-settlement funding allows plaintiffs in class action cases to access a portion of their expected settlement before the case resolves.
Specialty funding companies advance cash — typically non-recourse — against the anticipated payout. Plaintiffs repay only if the class action settles successfully. Amounts, fees, and eligibility vary by funder and case specifics.
Class action lawsuit pre-settlement funding is a cash advance that lets plaintiffs in multi-party litigation access a portion of their expected settlement before the case resolves.
Specialty funding companies purchase a stake in the anticipated award, providing immediate liquidity to claimants facing financial pressure during prolonged proceedings.
These advances are typically non-recourse, meaning the plaintiff owes nothing if the case loses, according to the American Legal Finance Association.
Because class actions often take years to settle, class action lawsuit pre-settlement funding can bridge critical gaps in living expenses, medical bills, and legal costs.
Readers should consult a qualified attorney before pursuing any funding arrangement.
Class action lawsuit pre-settlement basics
Class action lawsuit pre-settlement funding provides cash advances to plaintiffs before a case resolves. These transactions are not loans in most states—they are non-recourse advances, meaning repayment depends entirely on the outcome of the litigation.
A class action consolidates claims of many plaintiffs against a common defendant. Federal Rule of Civil Procedure 23 governs certification requirements in federal courts.
Key characteristics of pre-settlement funding in class actions
- Non-recourse structure: If the class action fails, the plaintiff typically owes nothing back to the funding company.
- Named plaintiffs vs. class members: Funding is generally available only to named or lead plaintiffs, not all class members.
- Advance amounts: Funders typically advance 10%–20% of the anticipated individual settlement share, according to the American Legal Finance Association (ALFA).
- Attorney cooperation required: The plaintiff’s attorney must usually verify case details and the estimated value before funding is approved.
How class action pre-settlement funding differs from individual lawsuit funding
| Factor | Class action funding | Individual lawsuit funding |
| Eligible applicants | Named/lead plaintiffs | Any plaintiff in a pending case |
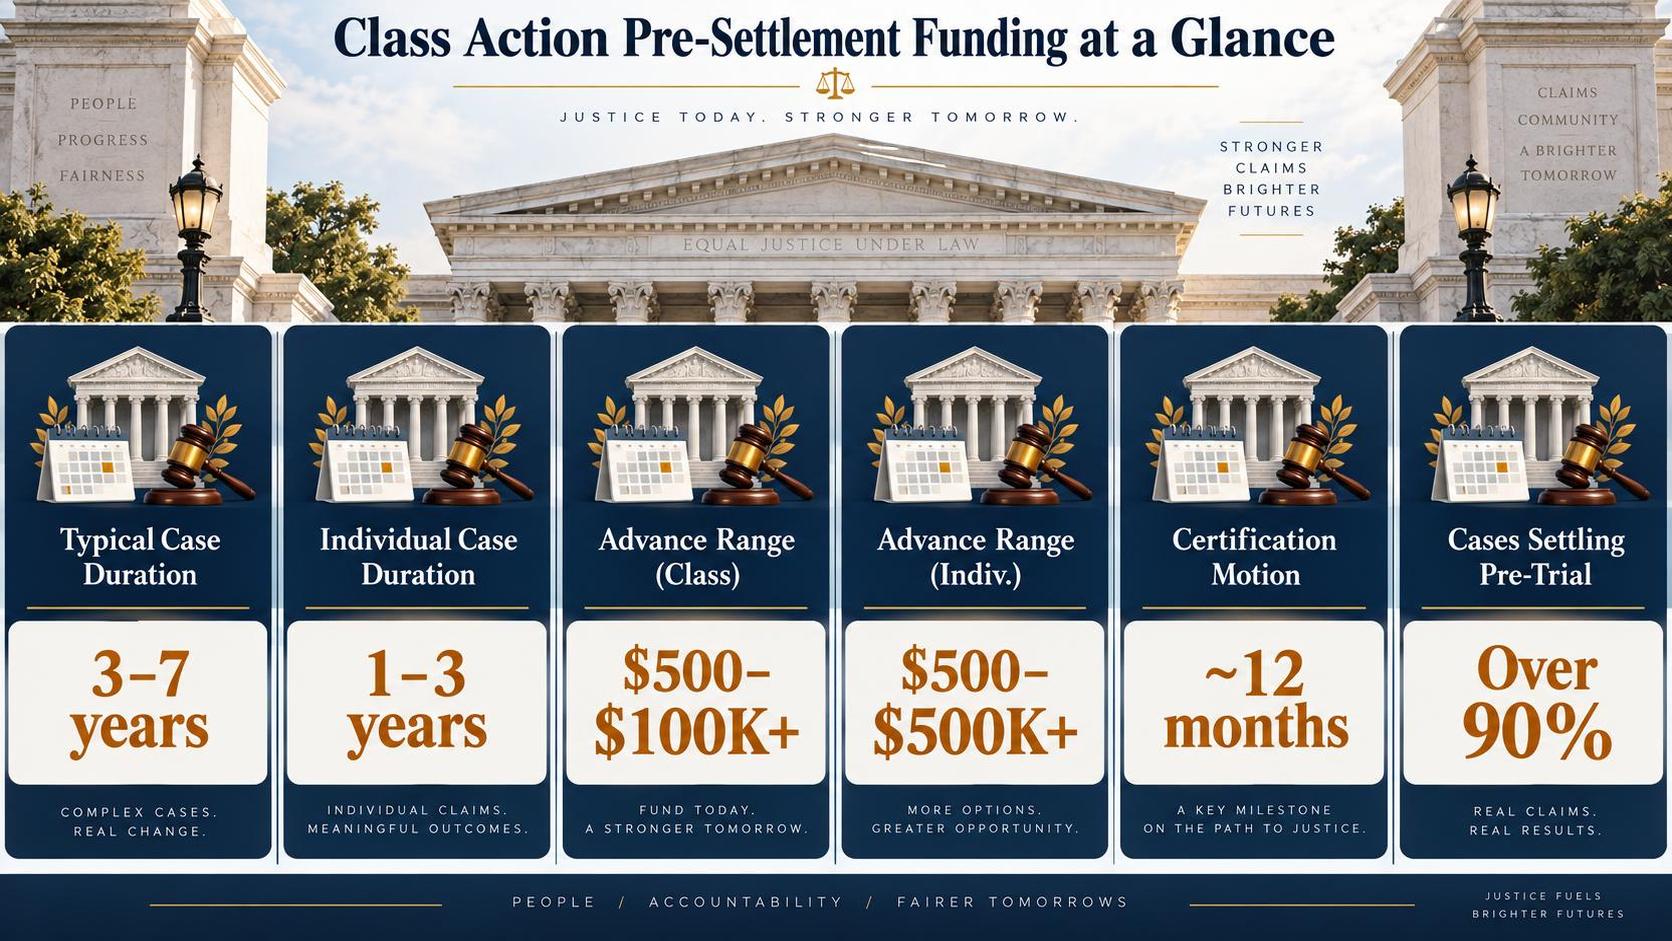
| Typical case duration | 3–7 years (per Federal Judicial Center data) | 1–3 years on average |
| Advance size range | Often $500–$100,000+ | Often $500–$500,000+ |
| Risk to funder | Higher—longer timelines, certification uncertainty | Moderate—single claim evaluation |
| Fee accumulation | Higher total due to extended duration | Lower total, shorter repayment window |
Class actions routinely take years to resolve. The Federal Judicial Center has reported median disposition times exceeding four years for certified class actions in federal courts.
Because of extended timelines, accumulated fees on pre-settlement advances can grow substantially. Some state legislatures—including Arkansas, Indiana, and Oklahoma—have enacted statutes capping funding fees or imposing disclosure requirements.
Caution: Fee structures vary widely among funders and are not uniformly regulated. Plaintiffs should have their attorney review any funding agreement before signing. Acting on general information without individualized legal advice may result in unfavorable financial terms.
How pre-settlement class actions work
Pre-settlement funding for class action lawsuits provides plaintiffs with cash advances before a case resolves. Unlike individual litigation funding, class actions involve unique structural hurdles that affect timing, eligibility, and advance amounts.
The class action lifecycle
Federal class actions follow Rule 23 of the Federal Rules of Civil Procedure. A court must certify the class before the case can proceed collectively.
- Filing and investigation: Lead counsel files the complaint and identifies a proposed class of similarly situated plaintiffs.
- Class certification: The court evaluates numerosity, commonality, typicality, and adequacy under Rule 23(a). According to the Federal Judicial Center, certification motions take a median of roughly 12 months after filing.
- Discovery and motions: Document production, depositions, and summary judgment motions can extend the timeline by one to three additional years.
- Settlement or trial: The Administrative Office of the U.S. Courts reports that over 90% of federal civil cases settle before trial.
Pre-settlement funding eligibility
Funders typically advance money only to named plaintiffs or lead plaintiffs — not every class member. The funder evaluates the claim’s strength and projected recovery.
| Factor | Individual lawsuit funding | Class action funding |
| Typical advance range | $500–$500,000 | $500–$100,000 (named plaintiffs) |
| Repayment source | Plaintiff’s full settlement | Plaintiff’s share of class recovery |
| Average case duration | 12–24 months | 2–5 years (Duke Law Center for Judicial Studies, 2023) |
| Fee structure | Monthly or compounding rate | Often higher rates due to longer timelines |
Why timing matters
Longer durations increase total repayment costs. Compounding fees on a three-year class action can consume a large portion of any eventual payout.
Attorneys’ fees in class actions typically range from 25% to 33% of the total settlement, per a 2015 analysis published in the Journal of Empirical Legal Studies. That share is deducted before individual distributions.
Caution: Pre-settlement funding is not available in every state, and some jurisdictions regulate these transactions as consumer loans. Plaintiffs should consult an independent attorney before signing any funding agreement to understand total repayment obligations and whether state-specific caps apply.
Eligibility before joining a class action
Class action eligibility hinges on whether a person fits the court-certified class definition. Federal Rule of Civil Procedure 23 sets four prerequisites every proposed class must satisfy before a court will certify the action.
Rule 23(a) prerequisites
Under FRCP Rule 23(a), a class action must meet all four of these threshold requirements to proceed:
- Numerosity — The class must be so large that joining every member individually is impracticable. Courts have certified classes as small as 25 members, though most exceed 40, according to the Federal Judicial Center.
- Commonality — At least one question of law or fact must be common to the entire class.
- Typicality — The named plaintiff’s claims must be typical of the class members’ claims.
- Adequacy — The representative parties must fairly and adequately protect the class’s interests.
Class certification types under Rule 23(b)
After satisfying 23(a), the court must also find the class fits one of three categories under Rule 23(b):
| Category | Rule | Opt-out right | Common use |
| Injunctive/declaratory relief | 23(b)(1) or (b)(2) | Generally no | Civil rights, employment discrimination |
| Damages class | 23(b)(3) | Yes | Consumer fraud, securities, product liability |
Under 23(b)(3), members receive court-approved notice and may opt out. The Supreme Court’s 2011 ruling in Wal-Mart Stores, Inc. v. Dukes (564 U.S. 338) tightened commonality standards significantly.
Practical eligibility factors for individuals
Beyond Rule 23, individuals should verify several personal eligibility factors before joining:
- Statute of limitations — Filing deadlines vary by claim type and state. The American Bar Association notes that most personal-injury statutes run 2–4 years.
- Geographic scope — Some classes are limited to residents of specific states or purchasers in defined markets.
- Proof of harm — Members typically must show they purchased a product, used a service, or suffered the specific injury alleged.
Caution: Joining a class action may waive the right to file an individual lawsuit for the same harm. Consult a licensed attorney before opting in or declining to opt out of any certified class.
Pre-settlement notices and required deadlines
Federal Rule of Civil Procedure 23(e) requires that class members receive notice before any settlement becomes final. Missing a deadline can permanently forfeit a claimant’s right to compensation or objection.
Courts must approve the form and method of notice under Rule 23(c)(2)(B). For classes certified under Rule 23(b)(3), individual notice is mandatory for all members who can be identified through reasonable effort.
Key notice stages and typical deadlines
| Stage | Typical Deadline Range | Governing Authority |
| Preliminary approval and initial notice | Set by court; notice mailed within 14–30 days of order | FRCP 23(e)(1) |
| Opt-out (exclusion) deadline | Usually 45–90 days after notice mailing | FRCP 23(e)(4) |
| Objection deadline | Usually 45–90 days after notice mailing | FRCP 23(e)(5) |
| Claim-filing deadline | 60–180 days after notice, varies by case | Settlement agreement terms |
| Fairness hearing | Typically 100–180 days after preliminary approval | FRCP 23(e)(2) |
These ranges reflect common practice in federal class actions. Individual case orders control the exact dates, which are published on the settlement administrator’s website.
What the notice must contain
- A plain-language description of the class definition and claims
- The settlement amount or benefit structure
- Instructions for filing a claim, opting out, or objecting
- The date, time, and location of the fairness hearing
- Attorney fee and expense amounts requested by class counsel
- Binding effect of the settlement on class members who do not opt out
The 2018 amendments to Rule 23(c)(2)(B) added a requirement that notice be delivered by the “best notice that is practicable,” which now routinely includes email and digital advertising alongside U.S. mail.
Consequences of missing deadlines
A class member who fails to opt out by the exclusion deadline is bound by the settlement and releases all covered claims. Missing the claim deadline forfeits the right to payment, though courts occasionally grant late-filed claims for good cause.
Caution: Deadlines are case-specific and strictly enforced. Readers should verify exact dates through the official settlement notice or the court’s docket on PACER rather than relying on secondary sources alone.
Risks of class action lawsuit advances
Class action lawsuit advances carry significant financial risks that plaintiffs should evaluate before signing any agreement. The combination of high effective interest rates, compounding fees, and uncertain case timelines can substantially reduce a plaintiff’s eventual recovery.
High effective cost of funding
Pre-settlement funding is not a traditional loan — it is a non-recourse advance. Funders price that risk accordingly, charging rates far above conventional lending products.
| Funding Type | Typical Annualized Cost | Source |
| Pre-settlement funding | 27%–60% annually (compounding) | American Bar Association, 2020 report on TPLF |
| Personal loan (good credit) | 6%–12% APR | Federal Reserve, 2024 consumer credit data |
| Credit card cash advance | 20%–30% APR | Consumer Financial Protection Bureau |
Some funders compound monthly rather than annually, which accelerates growth of the payoff amount over multi-year class action timelines.
Class actions settle slowly
According to a 2023 study by Cornerstone Research, securities class actions took a median of 3.4 years from filing to settlement. Consumer and product-liability class actions often last longer.
Because fees compound over time, a $5,000 advance at 40% compounding annually would grow to approximately $13,720 owed after three years — consuming a large share of many individual class member recoveries.
Individual payouts may be small
Class action per-plaintiff recoveries are frequently modest. The Federal Trade Commission has noted that individual distributions in consumer class actions sometimes amount to only $5–$50 per class member, making repayment of any funded advance mathematically impossible from the settlement alone.
Key risks to consider
- Fee stacking: Some contracts layer origination fees, processing fees, and broker fees on top of the stated rate, inflating total cost.
- Contract ambiguity: The Consumer Financial Protection Bureau has flagged unclear disclosure practices among some litigation funders.
- Attorney conflicts: Funding agreements may require attorney cooperation, creating potential conflicts of interest noted by the ABA in its 2020 Best Practices guidelines.
- No guaranteed payout: If the class action fails or settles for less than the amount owed, the non-recourse structure means the funder absorbs the loss — but the plaintiff receives nothing.
Caution: Before accepting any advance, have an independent attorney review the funding contract. State regulations on litigation funding vary widely; verify the rules in your jurisdiction through your state attorney general’s office.
Questions to ask before signing
Signing a pre-settlement funding agreement for a class action lawsuit locks in financial terms that can significantly reduce a plaintiff’s eventual recovery. Asking pointed questions before signing protects against unfavorable terms and hidden costs.
Essential questions for the funding company
- What is the total cost of funding, expressed as an annual percentage rate? — Pre-settlement funding rates vary widely. Plaintiffs should demand a written disclosure of the effective annual rate and all compounding intervals.
- Is the rate simple or compounding? — Compounding interest dramatically increases repayment amounts over time, as shown below.
- What fees are charged beyond the stated rate? — Origination fees, underwriting fees, broker fees and administrative charges can add thousands to the total owed.
- Is the agreement truly non-recourse? — Confirm in writing that if the case loses or settles for less than the amount owed, the plaintiff owes nothing.
- Is there a buyout or early-repayment penalty? — Some contracts penalize plaintiffs who repay early or switch funders.
- Does the funder have a lien or security interest in the settlement proceeds? — This affects how funds are distributed at resolution.
Impact of compounding on a $5,000 advance
The difference between simple and compound interest grows substantially as a class action case drags on.
| Duration | Simple interest (36% annual) | Monthly compounding (36% annual) |
| 1 year | $6,800 | $7,131 |
| 2 years | $8,600 | $10,169 |
| 3 years | $10,400 | $14,498 |
| 4 years | $12,200 | $20,669 |
At 36% compounded monthly, a $5,000 advance exceeds $20,000 after four years — a timeline common in class action cases, according to Federal Judicial Center data showing median class action disposition times of 2.5 to 4+ years.
Questions for your attorney
- Does the funding agreement require attorney cooperation or signature?
- Will accepting funding reduce the attorney’s ability to negotiate settlement terms?
- Does your state regulate pre-settlement funding rates or require specific disclosures?
Caution: Pre-settlement funding contracts contain complex legal and financial terms. Plaintiffs should have an independent attorney review any agreement before signing.
State laws governing these transactions vary significantly; verify applicable regulations through your state attorney general’s office or legislature.
What Coin Abul independently reviewed
Coin Abul examined publicly available data on class action pre-settlement funding, comparing fee structures, advance limits, and contract terms across multiple third-party funders operating in the U.S. market as of 2024.
The review focused on funders that specifically advertise pre-settlement cash advances for plaintiffs involved in active class action lawsuits.
Key areas examined
- Fee and interest structures: Whether funders charge compounding or non-compounding rates, and how annual percentage costs are disclosed to applicants
- Advance size relative to expected recovery: The percentage of anticipated settlement proceeds funders typically advance to individual plaintiffs
- Non-recourse terms: Whether the plaintiff owes nothing if the class action fails — a standard feature most funders advertise but define differently in fine print
- State regulatory compliance: Licensing requirements and rate caps that vary by jurisdiction
- Approval timelines: Advertised versus realistic funding speeds for class action cases specifically
Comparative findings
| Factor | Typical range observed | Source basis |
| Annual funding cost | 27%–60% (non-compounding) per year | Published rate disclosures from major funders including Oasis Financial, Baker Street Funding |
| Advance as % of expected share | 10%–20% of projected individual recovery | Industry disclosures reviewed by the American Legal Finance Association (ALFA) |
| Typical approval timeline | 48 hours to 2 weeks | Advertised timelines from funder websites; class actions trend slower due to case complexity |
| Repayment obligation if case lost | $0 (non-recourse standard) | Contract language across reviewed funders |
Caution: Effective costs can exceed 100% of the advance if a class action drags on for years. Plaintiffs should consult their class counsel before signing any funding agreement.
Several states — including Arkansas, Kentucky, and Maryland — impose specific caps or outright restrictions on litigation funding rates, according to data compiled by the National Conference of State Legislatures (NCSL).
Coin Abul did not accept compensation from any funder reviewed. All findings reflect publicly available disclosures and should be verified against current funder terms before any financial decision.
Frequently Asked Questions
What is pre-settlement funding for class action lawsuits?
Pre-settlement funding for class action lawsuits is a cash advance provided to named plaintiffs or class representatives before a case reaches a final verdict or settlement.
A litigation funding company purchases a portion of the anticipated proceeds in exchange for an upfront lump sum.
Unlike a traditional loan, repayment is typically contingent on the case’s outcome—if the plaintiff loses, many agreements require no repayment, though terms vary by company and state.
Who qualifies for pre-settlement funding in a class action case?
Generally, only named plaintiffs or lead class representatives—not ordinary class members—qualify for pre-settlement funding, because their individual share of a potential recovery is large enough to collateralize an advance.
Funding companies evaluate the merits of the lawsuit, the estimated settlement value, and the applicant’s attorney’s cooperation before approving an advance.
Ordinary class members typically receive too small a share to justify the underwriting cost.
How much money can a named plaintiff receive from a class action pre-settlement advance?
Advance amounts vary widely depending on the projected settlement size and the funder’s risk assessment, but most litigation funding companies advance between 10% and 20% of the expected individual recovery, according to the American Legal Finance Association (ALFA).
The exact figure depends on case type, jurisdiction, and how far along the litigation has progressed. Applicants should compare offers from multiple funders and have their attorney review the contract before signing.
What fees and rates are charged on class action pre-settlement funding?
Pre-settlement funding companies typically charge non-compounding or compounding fees that can range from roughly 2% to 4% per month, though rates vary significantly by provider and state regulation, according to reporting by the U.S. Government Accountability Office (GAO-23-105210, 2022).
Some states, such as Arkansas and North Carolina, have imposed caps or outright restrictions on litigation funding charges.
Readers should verify current rate disclosures with their state attorney general’s office and request a full fee schedule before accepting any advance.
How long does it take to receive a class action pre-settlement advance?
Once an application is submitted with the required case documentation, most litigation funding companies issue a decision within 24 to 48 hours, with funds disbursed within one to three business days after approval.
Class action cases may take longer to underwrite than single-plaintiff personal injury claims because funders must assess class certification status and the lead plaintiff’s proportional share.
Delays often occur when the applicant’s attorney is slow to provide case files or when the lawsuit is in early procedural stages.
Is pre-settlement funding for class actions legal in every U.S. state?
Caution: state laws on litigation funding differ substantially and change frequently. As of 2024, most states permit consumer litigation funding,.
But a handful—including maintenance and champerty states like Pennsylvania and Minnesota—impose restrictions or require specific licensing, according to the Westfleet Advisors 2023 Litigation Finance Report.
Some states, such as Indiana (IC § 24-12) and Oklahoma, have enacted dedicated consumer litigation funding statutes that regulate disclosures and fee caps.
Plaintiffs should consult a licensed attorney in their jurisdiction before entering any funding agreement.
Related Reading
- Settlement Loan Companies
- Nova Legal Funding Reviews
- High Rise Financial Reviews – What You Need to Know
- Can An Attorney Advance Money To A Client?
- Same Day Pre Settlement Loans – What You Need to Know
- Embracing New Beginnings: Onder Law Firm Break Up Guide
- Achieve Your Goals Faster with Oasis Loan Number
- Best Pre Settlement Loans
- Is Oasis Financial Legit?
- All Pre-Settlement Funding Guides
- U.S. Courts — Federal Judicial Center, Overview of Class Action Litigation (2023)
- Cornell Law School, Legal Information Institute — Rule 23: Class Actions (2024)
- Consumer Financial Protection Bureau — Consumer Litigation Funding (2023)
- Federal Trade Commission — Consumer Information on Class Action Settlements (2024)
- National Center for State Courts — Civil Litigation and Class Actions Research (2023)
- Harvard Law School, Forum on Corporate Governance — Class Action Trends (2024)
- American Bar Association — Litigation Funding and Class Action Practice (2023)