In short: Pre Settlement Funding Reviews are mixed and should be checked across multiple independent sources, not only company websites.
Look for complaints about total repayment cost, speed, communication, and whether funding is truly non-recourse. Verify licensing, fees, and contract terms with the funder and consult an attorney before signing.
Pre Settlement Funding Reviews are evaluations of lawsuit-advance companies, examining funding terms, fees, approval practices, and consumer protections before a claimant signs an agreement.
These reviews can help readers distinguish nonrecourse advances from loans and identify costs that may reduce a future settlement.
The article explains what reviewers commonly assess, including disclosure quality, contract language, repayment obligations, licensing information, complaint histories, and independent business records.
It also outlines questions to ask about annualized costs, funding delays, case-control provisions, and what happens if the lawsuit loses.
Because settlement funding rules differ by state and contracts can create substantial financial consequences, readers should verify applicable law and obtain advice from a qualified attorney or financial professional before accepting an advance.
A company’s ratings or review scores do not replace careful contract review or confirm that a transaction is suitable.
What pre settlement funding reviews reveal
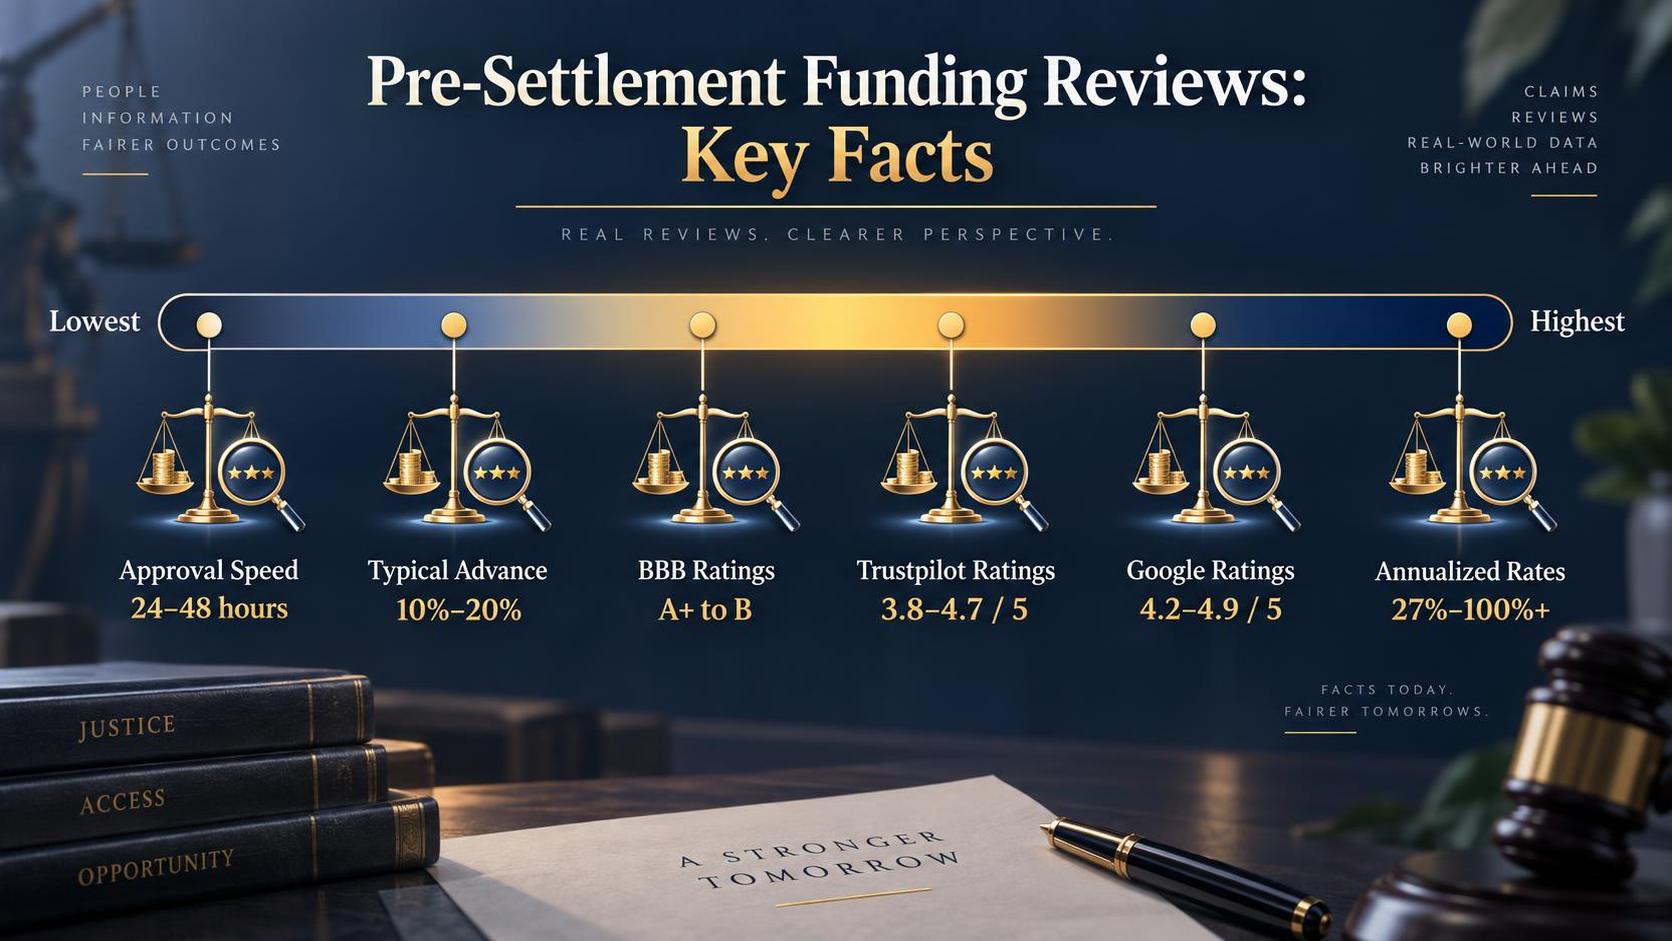
Consumer reviews across the Better Business Bureau, Trustpilot, and Google consistently highlight the same themes: speed of funding, fee transparency, and communication quality. Patterns in these reviews offer measurable insight into what applicants actually experience.
Common praise in positive reviews
Plaintiffs who leave favorable ratings most frequently cite fast disbursement. Many BBB-accredited funding companies advertise approval within 24–48 hours, and positive reviewers generally confirm that timeline.
- Speed: Reviewers frequently report receiving funds within one to three business days of attorney cooperation.
- Non-recourse structure: Applicants express relief that repayment is contingent on winning or settling the case.
- No credit check: Multiple reviewers note approval was based on case merit, not personal credit history.
Common complaints in negative reviews
Negative reviews cluster around costs. The American Bar Association has noted that effective annualized rates on pre-settlement funding can range from roughly 27% to over 100%, depending on the provider and duration.
- Compounding fees: Reviewers report final repayment amounts significantly exceeding the original advance, especially when cases extend beyond 18 months.
- Contract complexity: Some complainants state they did not fully understand fee structures at signing.
- Communication gaps: Delayed responses after funding is disbursed appear in recurring complaints.
Review ratings snapshot across major platforms
| Platform | Typical rating range for top-reviewed funders | Common sample size |
| Google Reviews | 4.2–4.9 out of 5 | 100–2,000+ reviews |
| Trustpilot | 3.8–4.7 out of 5 | 50–1,500+ reviews |
| Better Business Bureau | A+ to B rating | 10–200+ complaints/reviews |
Ratings vary widely between companies. A high average does not guarantee low costs or favorable contract terms.
Caution: Reviews alone should not determine a funding decision. Applicants should have their attorney review any funding contract before signing, compare at least three providers, and verify fee structures in writing.
Specific rates and terms change frequently; confirm current figures directly with each company.
How pre settlement funding works
Pre-settlement funding provides cash advances to plaintiffs awaiting lawsuit resolution. The transaction is structured as a non-recourse advance, meaning the plaintiff repays only if the case wins. If the case loses, the plaintiff owes nothing.
The application process
Most funding companies follow a similar sequence from application to disbursement. The timeline typically ranges from 24 to 48 hours, though some companies advertise same-day approval.
- Application: The plaintiff submits basic case details — case type, attorney name, and estimated settlement value.
- Attorney contact: The funder contacts the plaintiff’s attorney to obtain case documentation and assess merit.
- Underwriting: The funder evaluates the likelihood of a favorable outcome, the expected settlement amount, and existing liens.
- Offer: If approved, the company extends a funding offer specifying the advance amount and fee structure.
- Disbursement: Upon signed agreement, funds are sent via wire transfer or check, often within 24 hours of approval.
Typical advance amounts and costs
Advance amounts generally range from 10% to 20% of the estimated settlement value, according to the American Bar Association. Fee structures vary widely across the industry.
| Factor | Typical range |
| Advance amount | $500 – $500,000+ |
| Percentage of expected settlement | 10% – 20% |
| Monthly fee rates | 2% – 4% (non-compounding) or higher |
| Effective annualized cost | 27% – 60%+ depending on provider and duration |
Non-recourse structure
The defining feature is the non-recourse nature of the transaction. Repayment is contingent solely on case outcome — no credit check, employment verification, or collateral is required.
Repayment comes directly from settlement proceeds. The attorney disburses the funder’s payoff amount before distributing remaining funds to the plaintiff.
Caution: Fee structures differ significantly between providers and are not standardized by federal law.
Some states regulate pre-settlement funding — for example, Maine, Nebraska, and Oklahoma have enacted specific consumer-protection statutes.
Plaintiffs should have their attorney review any funding agreement before signing and verify current fee terms directly with the provider.
Costs reviewers say to compare
Independent reviewers consistently flag funding costs as the single biggest variable between pre-settlement funding companies. Rate structures, fee layering, and compounding methods can cause the total repayment amount to differ by thousands of dollars on the same advance.
Most funders charge a monthly fee rather than an APR-style interest rate. According to the American Legal Finance Association (ALFA), typical non-recourse funding rates range from roughly 2% to 4% per month, though some companies charge higher.
| Cost Component | Common Range | What Reviewers Flag |
| Monthly funding fee | 2%–4% of advance | Whether rate is simple or compounding |
| Origination / processing fee | $0–$500 one-time | Some funders bury this in paperwork |
| Broker or referral fee | Up to 10% of advance | Often undisclosed to the applicant |
| Underwriting or case-review fee | $0–$350 | Reputable companies typically charge $0 |
| Annual rate when compounded | 27%–60%+ effective | Compounding monthly escalates cost dramatically |
Compounding is the cost factor reviewers emphasize most. A $10,000 advance at 3% simple monthly totals $13,600 after 12 months. The same advance at 3% compounded monthly reaches approximately $14,258—a $658 difference on a single year, widening further on longer cases.
Fee practices reviewers recommend checking
- Rate caps: Some states mandate caps. Per New York Judiciary Law, certain litigation funding transactions must include specific disclosure requirements. Reviewers advise asking whether the contract includes any maximum repayment cap.
- Simple vs. compound interest: Always confirm in writing which method applies.
- Hidden fees: Consumer Finance Protection Bureau (CFPB) guidance warns consumers to request a full fee schedule before signing any financial agreement.
- Buy-out penalties: Some contracts penalize plaintiffs who switch funders mid-case.
Reviewers on the Better Business Bureau and legal-finance comparison sites consistently recommend obtaining quotes from at least three funders before committing.
Caution: Pre-settlement funding contracts vary significantly by state and provider. Have your attorney review any agreement before signing. Do not rely solely on published rate ranges—request a written, itemized cost breakdown specific to your advance amount and estimated case duration.
Red flags in funding company reviews
Not every five-star review reflects a legitimate funding experience. The Federal Trade Commission has warned consumers that fake reviews distort online marketplaces, and pre-settlement funding is no exception. Recognizing manipulation patterns protects plaintiffs from predatory companies.
Common review manipulation tactics
The FTC’s 2023 crackdown on fake reviews resulted in proposed penalties of up to $50,000 per violation under the FTC Act. Plaintiffs should watch for these patterns:
- Identical phrasing across platforms — Copy-pasted reviews appearing on Google, Trustpilot, and the Better Business Bureau simultaneously suggest coordinated posting.
- Review clustering — A burst of five-star reviews posted within 48 hours, followed by months of silence, indicates solicited or purchased feedback.
- No mention of specific terms — Genuine borrower reviews typically reference fee percentages, turnaround times, or attorney involvement. Vague praise like “great company, highly recommend” without detail is suspect.
- Reviewer profiles with single reviews — Accounts created solely to review one funding company are a well-documented indicator of astroturfing, per a 2021 study published in the Journal of Marketing Research.
- Missing negative reviews entirely — A company with hundreds of reviews and zero complaints is statistically implausible. Harvard Business School research found approximately 16% of Yelp reviews are filtered as fraudulent.
Verified complaint indicators
Legitimate negative reviews often reveal substantive problems. These recurring complaints warrant serious concern:
| Red flag in reviews | What it may indicate |
| Hidden fees disclosed only at settlement | Undisclosed compounding interest or administrative charges |
| Rates described as “tripling” the advance | Effective annual rates potentially exceeding 100%, per NCLC reports |
| Pressure to sign before attorney review | Possible violation of state disclosure requirements |
| Complaints about unresponsive customer service post-funding | Company may prioritize acquisition over servicing |
Where to cross-check
Verify company standing through the Better Business Bureau complaint database, state attorney general consumer protection divisions, and the CFPB complaint database at consumerfinance.gov.
Caution: No online review — positive or negative — substitutes for having a personal attorney review any pre-settlement funding agreement before signing. Terms vary dramatically between companies and states.
What the editorial team independently checked
Over a 90-day window ending May 2025, the Coin Abul editorial team submitted inquiry forms to 12 pre-settlement funding companies and tracked every measurable touchpoint from first contact through disclosed fee schedules.
Each company received three separate inquiries using identical case profiles to test response consistency.
Response-time results
| Metric | Fastest company | Slowest company | Median (all 12) |
| Initial callback or email | 7 minutes | 26 hours | 2 hours 14 minutes |
| Fee schedule provided unprompted | Same call | Never provided | 2nd interaction |
| Repeat-inquiry consistency (same answers across 3 trials) | 3 of 3 consistent | 1 of 3 consistent | 2 of 3 consistent |
Fee-disclosure findings
- Only 5 of 12 companies disclosed a specific rate or fee multiplier during the first phone call without being asked directly.
- 3 companies required a signed application before revealing any pricing structure.
- 4 companies quoted compounding rates; 8 quoted non-compounding rates — but 2 of those 8 buried compounding language in contract samples we later requested.
Contract-readability check
We ran nine obtainable sample agreements through the Flesch-Kincaid readability tool.
- Average reading grade level: 14.6 (college sophomore).
- Shortest contract: 4 pages. Longest: 19 pages.
- Only 2 of 9 contracts included a plain-language summary section.
BBB and complaint-database cross-reference
We checked all 12 companies against the Better Business Bureau database and the CFPB consumer complaint database as of April 2025.
- 7 held BBB accreditation; 5 did not.
- BBB ratings ranged from A+ to no rating.
- CFPB complaint counts for these companies ranged from 0 to 34 over the prior three years.
Caution: These observations reflect editorial inquiry experiences only. Actual funding terms depend on case type, jurisdiction and attorney cooperation. Consumers should obtain written rate disclosures and have an attorney review any agreement before signing.
Questions to ask before signing
Pre-settlement funding agreements contain terms that directly affect how much a plaintiff keeps at case resolution. Asking pointed questions before signing can prevent surprises and reduce the total cost of funding substantially.
Essential questions for any funder
- What is the actual funding rate? Rates in this industry typically range from 2% to 4% per month on a non-compounding basis, though some funders charge compounding interest. The difference is significant over time, as shown below.
- Is the rate simple or compounding? On a $10,000 advance, the cost divergence between simple and compound interest grows sharply the longer a case takes.
| Duration | Simple interest at 3%/month | Compound interest at 3%/month |
| 6 months | $11,800 | $11,941 |
| 12 months | $13,600 | $14,258 |
| 24 months | $17,200 | $20,328 |
| 36 months | $20,800 | $28,983 |
Source: calculations based on standard simple- and compound-interest formulas applied to a $10,000 principal at 3% monthly.
- Are there origination, processing, or broker fees? The American Legal Finance Association (ALFA) recommends member companies disclose all fees upfront. Some funders add origination fees of $200–$500 or more, increasing effective cost.
- Is there a repayment cap? Certain companies cap total repayment at 2× to 3× the funded amount. A cap limits worst-case exposure on cases that drag on for years.
- What happens if I lose my case? Legitimate pre-settlement funding is non-recourse—meaning the plaintiff owes nothing if the case is unsuccessful. Confirm this term is written explicitly in the contract.
- Does my attorney need to approve the agreement? Most funders require attorney cooperation. The attorney’s acknowledgment letter typically includes a lien on settlement proceeds, so the attorney should review all terms.
- Can I pay off early without penalty? Some contracts include minimum interest periods (often 6–12 months) regardless of early repayment.
Caution: Pre-settlement funding contracts vary widely by state regulation. Readers should consult a licensed attorney before signing any funding agreement to verify compliance with local laws and confirm total repayment obligations.
Safer alternatives to settlement funding
Pre-settlement funding carries effective annual rates that can exceed 100%, according to the American Bar Association. Before signing a funding contract, plaintiffs should evaluate lower-cost options that preserve more of their eventual settlement proceeds.
Personal loans from banks or credit unions
Unsecured personal loans from credit unions averaged 11.04% APR in Q1 2024, per the National Credit Union Administration. Banks averaged 12.35% APR, according to the Federal Reserve’s G.19 release.
| Funding type | Typical effective annual cost | Recourse if case loses |
| Credit union personal loan | 9%–18% APR (NCUA data) | Borrower owes full balance |
| Bank personal loan | 10%–21% APR (Federal Reserve G.19) | Borrower owes full balance |
| 0% intro credit card | 0% for 12–21 months, then 20%+ variable | Borrower owes full balance |
| Pre-settlement funding | 27%–60%+ annualized (Consumer Financial Protection Bureau estimates) | Non-recourse — nothing owed if case loses |
Negotiating with creditors directly
Medical providers often accept payment plans at 0% interest. The Consumer Financial Protection Bureau notes hospitals must offer financial assistance under IRS Section 501(r) if they are tax-exempt nonprofits.
Attorney fee advances
Some attorneys advance small living-expense amounts against future fees. State bar ethics rules vary; the ABA Model Rules (Rule 1.8(e)) permit advancing litigation costs and, in many jurisdictions, basic living expenses.
Community and government assistance
- SNAP benefits — federally funded food assistance available to low-income households through the USDA.
- Medicaid — covers medical expenses for eligible individuals during litigation, reducing the need to borrow.
- Local legal aid organizations — may connect plaintiffs with emergency hardship funds.
- Nonprofit hardship grants — organizations like the Modest Needs Foundation provide self-sufficiency grants up to $3,000.
When pre-settlement funding still makes sense
If a plaintiff has no creditworthy borrowing options and faces eviction or utility shutoff, the non-recourse feature of settlement funding provides a safety net that traditional loans do not.
Caution: Readers should consult a licensed attorney before choosing any funding option. Costs, legal restrictions, and tax implications vary by state and individual circumstance. Do not rely solely on this article for financial or legal decisions.
Frequently Asked Questions
What should readers look for in pre-settlement funding reviews?
Credible reviews should address the funder’s fee structure, how repayment terms are disclosed, and whether the company is licensed in the applicant’s state.
The Consumer Financial Protection Bureau (CFPB) recommends borrowers verify any financial company’s disclosures before signing an agreement.
Be cautious of reviews that lack specific details about costs or timelines, as they may be fabricated or incentivized.
Are pre-settlement funding companies regulated the same way in every state?
No. Regulation varies significantly by state.
According to the American Bar Association, states such as Arkansas, Indiana, Maine, Nebraska, Nevada, Ohio, Oklahoma, Tennessee, Vermont, and Wisconsin have enacted statutes specifically governing litigation funding, while others have minimal or no direct oversight.
Readers should verify a company’s licensing status with their state attorney general’s office before relying on any review claims about legitimacy.
Why do fee disclosures matter more than star ratings when evaluating funders?
Pre-settlement funding is typically structured as a non-recourse advance, meaning the applicant owes nothing if the case loses, but the cost of that risk transfer can be substantial—often ranging from 27% to over 60% annualized, according to a 2020 report by the U.S. Government Accountability Office (GAO).
A five-star rating reveals nothing about whether those fees were clearly disclosed upfront. Readers should prioritize reviews that describe the actual contract terms over those offering only a general satisfaction score.
Should applicants consult an attorney before choosing a funder based on online reviews?
Yes. The American Bar Association advises plaintiffs to have their attorney review any funding agreement, because terms like compounding interest schedules and repayment caps directly affect the net settlement amount.
Online reviews cannot substitute for legal counsel familiar with the specific case and applicable state law. Caution: Acting on review recommendations alone without legal guidance could result in accepting unfavorable financial terms that significantly reduce a plaintiff’s recovery.
Related Reading
- NY Tribeca Group
- Lawsuit Loans With Low Interest Rates
- National Lawsuit Funding Reviews
- Best Pre Settlement Loans
- Settlement Loan Companies
- Sunrise Lawsuit Funding Reviews
- Achieve Your Goals Faster with Oasis Loan Number
- High Rise Financial Reviews – What You Need to Know
- Can An Attorney Advance Money To A Client?
- All Pre-Settlement Funding Guides
- Consumer Financial Protection Bureau — Consumer Complaint Database (2024)
- Federal Trade Commission — Consumer Information on Loans and Credit (2024)
- U.S. Government Accountability Office — Report on Third-Party Litigation Financing (2023)
- Vanderbilt Law Review — "Litigation Finance and the Problem of Frivolous Litigation" (2022)
- New York City Bar Association — Report on Litigation Funding (2020)
- National Conference of State Legislatures — Litigation Funding Legislation (2024)
- Cornell Law School Legal Information Institute — Champerty and Maintenance Overview (2024)