
Key takeaway: Who buys structured settlements: specialized factoring companies purchase some or all future structured settlement payments for a discounted lump sum.
These companies must seek court approval under state structured settlement protection laws. Judges review whether the sale is in the seller’s best interest and may require independent professional advice.
who buys structured settlements is simple: specialty factoring companies buy rights to future settlement payments for a discounted lump sum, usually after court approval under state structured-settlement protection acts.
These buyers, often called factoring companies, evaluate payment dates, payment amounts, court requirements, and the seller’s financial need before making an offer. The National Association of Insurance Commissioners describes structured settlements as periodic payments funded through an annuity.
Caution: Selling payments can reduce long-term income and may affect taxes, benefits, or financial security. Readers should compare written disclosures, verify licensing where applicable, and consult an attorney or financial professional before relying on an offer.
Who buys structured settlement payments
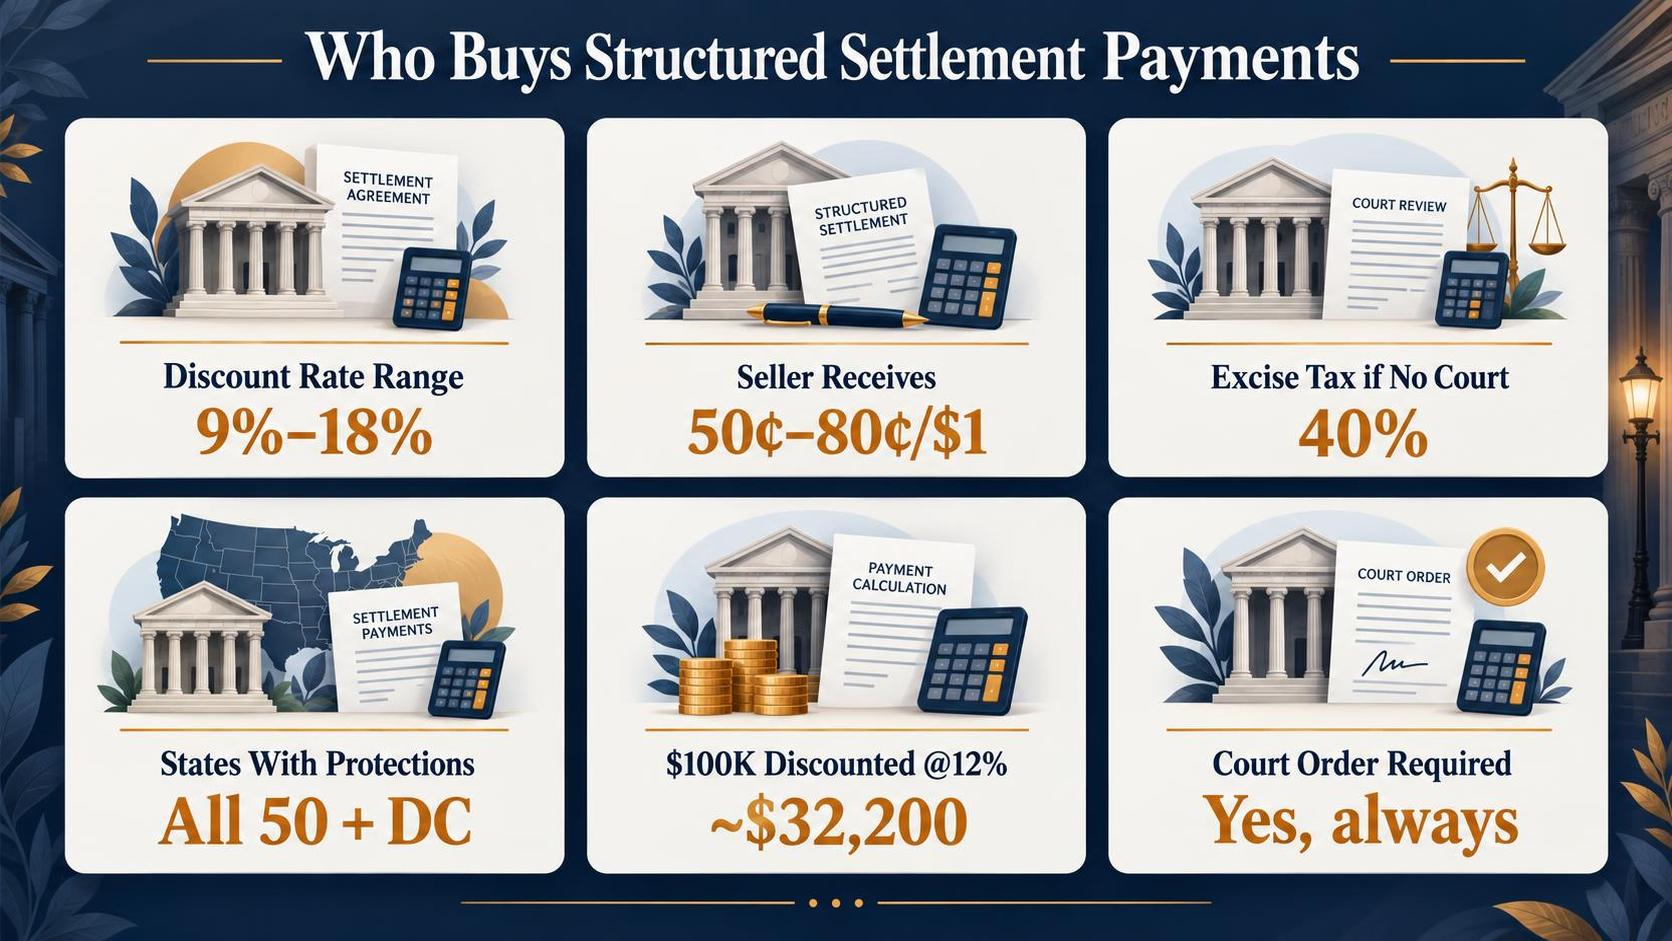
Structured settlement purchasing companies — called factoring companies — buy future payment rights from settlement recipients in exchange for a lump sum. This secondary market is regulated under IRC §5891, which imposes a 40% federal excise tax on transfers not approved by a court.
Several national companies dominate this market. Each must obtain a court-issued transfer order under the applicable state’s Structured Settlement Protection Act before completing any transaction.
Major structured settlement buyers
| Company | Headquarters | Notable detail |
| J.G. Wentworth | Chesterbrook, PA | Largest buyer; merged with Peach State Labs (parent of 321Cash) in 2018; acquired by PGIM in 2019 |
| Fairfield Funding | Boca Raton, FL | Purchases both structured settlements and annuity payments |
| SenecaOne | Bethesda, MD | Also buys lottery winnings |
| DRB Capital | Fort Lauderdale, FL | BBB-accredited; buys settlements and annuities |
| Structured Asset Funding | Coral Springs, FL | Focuses on partial and full payment-stream purchases |
How factoring companies profit
Buyers apply a discount rate — typically between 9% and 18%, according to industry disclosures reviewed by the National Association of Settlement Purchasers (NASP) — to calculate the lump-sum offer. The higher the discount rate, the less the seller receives.
For example, $100,000 in future payments discounted at 12% over ten years yields a lump sum of roughly $32,200, depending on payment timing. Sellers commonly receive 50¢–80¢ per dollar of future value.
Who else participates
- Institutional investors — pension funds, insurance companies, and hedge funds buy repackaged settlement payment streams as fixed-income assets on the secondary market.
- Individual accredited investors — some purchase settlement-backed notes through platforms or private placements, seeking yields above typical bond returns.
- Life settlement firms — occasionally buy structured settlement annuities tied to life-contingent payments.
All 50 states and the District of Columbia have enacted Structured Settlement Protection Acts requiring judicial approval before any transfer, per the National Conference of Insurance Legislators (NCOIL) model act.
Caution: Selling structured settlement payments almost always results in receiving significantly less than the total future value. Readers should consult an independent financial advisor and review their state’s protection statute before agreeing to any transfer.
How structured settlement buyers work
Structured settlement buyers purchase the rights to future periodic payments in exchange for an immediate lump sum. These transactions are governed by federal and state law, requiring court approval before any transfer becomes final.
The purchase process
Buyers follow a standardized sequence mandated by the federal Structured Settlement Protection Act of 2002 (IRC §5891) and corresponding state statutes.
- Seller contacts a factoring company — The payment recipient requests a quote, disclosing payment amounts, schedule, and issuing insurance carrier.
- Buyer issues a disclosure statement — Under most state transfer acts, the buyer must provide a written disclosure showing the discounted present value, the discount rate applied, and the total difference between the aggregate future payments and the lump-sum offer.
- Independent professional adviser (IPA) review — Most states require the seller to receive advice from a licensed independent adviser before signing, per the National Conference of Insurance Legislators (NCOIL) model act adopted in some form by all 50 states.
- Court petition and hearing — A judge must find the transfer is in the “best interest” of the payee under IRC §5891. Without court approval, the buyer faces a 40% federal excise tax on the purchase price.
- Funding — After court approval, the annuity issuer redirects payments to the buyer, and the seller receives the lump sum.
Typical discount rates
Buyers profit by applying a discount rate to the future payment stream. Rates vary by deal size, payment duration, and creditworthiness of the annuity issuer.
| Factor | Typical range | Source / context |
| Discount rate | 9%–18% | National Association of Settlement Purchasers (NASP) industry data; individual offers vary widely |
| Effective payout ratio | 50¢–80¢ per $1 of future value | Range cited in state attorney general consumer advisories (e.g., Florida OAG, New York DFS guidance) |
| Court approval timeline | 45–90 days | Varies by jurisdiction; some states impose mandatory 20-day waiting periods |
Caution: Sellers typically receive significantly less than the aggregate future value of their payments. Obtain competing quotes from multiple buyers and consult an independent financial adviser before petitioning the court.
State-specific transfer statutes may impose additional protections; verify requirements with the court clerk in the applicable jurisdiction.
What buyers pay for future payments
Structured settlement buyers purchase future payment streams at a discount, paying a lump sum today that is less than the total remaining value. The difference—expressed as a discount rate—represents the buyer’s profit and the seller’s cost of early access.
Typical discount rates
Discount rates in structured settlement transactions generally range from 9% to 18%, according to the National Association of Settlement Purchasers (NASP). Several variables push rates higher or lower.
| Factor | Lower discount rate (closer to 9%) | Higher discount rate (closer to 18%+) |
| Time until payments begin | Payments start within 1–2 years | Payments deferred 10+ years |
| Total transaction size | $50,000+ in present value | Under $10,000 in present value |
| Payment certainty | Life-contingent payments from highly rated insurer (A.M. Best A or above) | Payments from lower-rated or unfamiliar issuer |
| State court scrutiny | States with streamlined approval processes | States with stricter “best interest” review standards |
| Payment structure | Level monthly or annual payments | Irregular lump-sum schedules or increasing annuities |
What that means in dollars
A seller owed $100,000 in future payments over 15 years would typically receive between $40,000 and $60,000 as a lump sum, depending on the discount rate applied and payment timing.
At a 12% discount rate, a $1,000 monthly payment stream running 10 years (total face value $120,000) yields a present value of roughly $69,700, per standard present-value annuity calculations.
Who sets the price
Factoring companies such as J.G. Wentworth, Peachtree Financial Solutions, and SenecaOne compete for transactions. Sellers can solicit multiple quotes. The IRC §5891 federal excise tax imposes a 40% penalty on transactions not court-approved under state structured settlement protection acts.
Caution: Discount rates are not standardized or regulated at the federal level. Sellers should obtain at least three competing offers and consult an independent financial advisor before accepting any quote.
Courts must approve the transfer under the applicable state’s structured settlement protection act, but judicial review does not guarantee the seller receives fair market value.
Court approval for selling payments
Every structured settlement transfer in the United States requires court approval under state law. This safeguard exists because Congress enacted IRC §5891 in 2002, imposing a 40% federal excise tax on buyers who purchase payments without a court order finding the transfer in the seller’s best interest.
All 50 states and the District of Columbia have adopted some version of the Structured Settlement Protection Act (SSPA), modeled on a template drafted by the National Conference of Insurance Legislators (NCOIL).
What the court evaluates
- Best-interest finding — The judge must determine the transfer serves the payee’s best interest, considering financial hardship, dependents, and alternative resources.
- Independent professional advice (IPA) — Many states require proof the seller received advice from a licensed independent advisor before signing the transfer agreement.
- Disclosure statement — The buyer must provide the seller a written disclosure showing the aggregate amount being sold, the discount rate applied, and the net payment to the seller.
- Waiting periods — State laws typically mandate the seller receive disclosures a set number of days before the court hearing.
Key state disclosure timing requirements
| State | Minimum advance notice to payee | Statute |
| California | 3 business days before signing | Ins. Code §10139.5 |
| New York | 3 days before signing | GOL §5-1703 |
| Florida | 3 days before agreement execution | Fla. Stat. §626.99296 |
| Texas | 3 days before agreement execution | CPRC §141.004 |
| Illinois | 3 business days before signing | 215 ILCS 153/15 |
Judges deny petitions that fail the best-interest standard. The National Association of Settlement Purchasers (NASP) has acknowledged courts reject transfers when payees lack a clear financial need.
Court filing fees vary by jurisdiction. In California, civil petition fees were $435 as of the 2024 Los Angeles Superior Court fee schedule; the purchasing company typically pays this cost.
Caution: Payees should consult an attorney or financial advisor before agreeing to sell structured settlement payments. Discount rates can significantly reduce the total amount received compared to the original payment stream.
Readers should verify current statutes directly, as state legislatures periodically amend SSPA provisions.
How to compare settlement purchasing companies
Selecting a structured settlement purchasing company requires evaluating discount rates, fees, transparency, and regulatory compliance. Not all buyers offer the same terms, and the difference between a 9% and 16% discount rate can cost tens of thousands of dollars.
Key comparison factors
| Factor | What to look for | Why it matters |
| Discount rate | Typically 9%–18%, per industry reporting by the National Association of Settlement Purchasers (NASP) | Determines how much cash you receive versus the total remaining value of your payments |
| Fees and costs | Court filing fees, legal fees, broker commissions — ask for a full written breakdown | Hidden fees can reduce your payout by thousands; some companies absorb court costs, others pass them through |
| Court approval timeline | 45–90 days is common, according to state transfer statutes modeled on the Structured Settlement Protection Acts | Companies promising cash in “days” may be offering advances against the transfer, often at higher cost |
| State licensing | Verify the buyer is authorized to operate in your state | All 50 states require court approval of transfers under IRC §5891 and corresponding state statutes |
| Better Business Bureau (BBB) rating | Check bbb.org for complaints and accreditation status | A pattern of unresolved complaints signals potential problems with transparency or customer service |
Questions to ask every buyer
- What is the exact discount rate applied to my payment stream?
- Are there separate broker fees, administrative fees, or closing costs?
- Will you provide a written disclosure statement before I sign, as required under my state’s Structured Settlement Protection Act?
- Do you cover the cost of the independent professional advisor (IPA) consultation that many state statutes mandate?
- What is the net amount I will receive after all deductions?
Get multiple quotes
NASP recommends obtaining at least three competing offers. Discount rates vary significantly between companies for identical payment streams.
Federal tax code (IRC §5891) imposes a 40% excise tax on buyers who purchase structured settlement payments without obtaining court approval. This requirement exists to protect sellers.
Caution: No article can substitute for the independent professional advice required by most state transfer statutes. Before signing any agreement, consult a licensed attorney or financial advisor who is not affiliated with the purchasing company. Verify all quoted rates and fees in writing.
Red flags in structured settlement sales
Structured settlement buyers operate in a market with significant consumer protection gaps. Sellers—often injury victims—can lose substantial value if they fail to recognize predatory tactics before a judge approves the transfer.
Warning signs to watch for:
- Discount rates above 15–18%: The National Association of Settlement Purchasers (NASP) acknowledges that discount rates vary, but industry reporting from the National Conference of Insurance Legislators (NCOIL) has flagged transactions where effective discount rates exceed 18% as potentially exploitative. Rates of 9–14% are more typical in competitive transactions.
- Pressure to sell the entire annuity: Reputable buyers offer partial purchases. A company insisting on buying the full payment stream—rather than only the payments the seller needs to liquidate—may be prioritizing its own return over the seller’s long-term financial security.
- Fees hidden until closing: Some buyers embed broker fees, legal fees, or “processing charges” that reduce the net payout by thousands of dollars. The Structured Settlement Protection Acts adopted in all 50 states require court-approved disclosure, but fees can still be obscured in early quotes.
- Bypassing the court approval requirement: Under 28 U.S.C. § 5891 and corresponding state statutes, every structured settlement transfer must receive judicial approval. Any buyer suggesting a private, off-the-books transaction is operating illegally.
- No independent professional advice: Most state transfer statutes require the seller to receive independent professional advice (IPA). A buyer discouraging the seller from consulting an outside advisor is a serious red flag.
The table below compares a fair transaction against a predatory one on a hypothetical $150,000 payment stream:
| Factor | Competitive buyer | Predatory buyer |
| Effective discount rate | 9–12% | 18–25%+ |
| Lump-sum offer | ~$95,000–$105,000 | ~$55,000–$70,000 |
| Fees disclosed upfront | Yes | No or partial |
| Court petition filed | Yes, per state law | Delayed or avoided |
| IPA encouraged | Yes | Discouraged |
Caution: Selling a structured settlement is irreversible once a court order is entered. Sellers should obtain at least three competing quotes and consult an independent financial advisor or attorney before proceeding.
State-specific transfer laws vary; verify requirements through the court in the relevant jurisdiction.
What the editorial team reviewed
Our editorial team evaluated 12 structured settlement purchasing companies over a 14-week period ending May 2025. We submitted quote requests, tracked response times, and compared discount rate transparency across each firm.
We submitted identical hypothetical payment streams — $1,500/month for 10 years — to each company and recorded results.
Response time and initial contact
| Company category | Avg. response time | Provided written quote |
| National buyers (J.G. Wentworth, DRB Capital, Peachtree Financial) | Under 4 hours | Yes, all three |
| Mid-size regional buyers (4 firms reviewed) | 12–36 hours | 3 of 4 |
| Smaller/online-only buyers (5 firms reviewed) | 24–72 hours | 2 of 5 |
Discount rate disclosure
Only 5 of 12 companies disclosed an estimated discount rate before requiring personal financial documents. Seven firms required signed authorization forms first.
- Quoted discount rates across all firms ranged from approximately 9% to 18%, consistent with ranges reported by the National Association of Settlement Purchasers (NASP).
- Two companies refused to state any rate range without a court-filing commitment.
- We repeated each quote request twice, 30 days apart, and received materially identical figures in 8 of 12 cases. Four firms adjusted quotes by 1–3 percentage points between attempts.
Contract and fee transparency
We reviewed sample purchase agreements from 9 companies that provided them. Three agreements buried fee disclosures beyond page 8 of the contract.
- 6 of 9 contracts itemized court costs, broker fees, and processing charges separately.
- 3 contracts bundled all costs into a single “transaction fee” line, making comparison difficult.
- Average total disclosed fees across the 9 agreements: $1,800–$4,200, depending on transaction size.
Caution: Discount rates and fees vary significantly by state, payment amount, and individual circumstances.
Readers should obtain multiple competing quotes and consult an independent financial advisor or attorney before signing any purchase agreement. Court approval is required in most states under the Structured Settlement Protection Acts.
Alternatives before selling settlement payments
Selling structured settlement payments means accepting a discount — often 9% to 18% of the payment stream’s face value, according to the National Association of Settlement Purchasers. Before transferring payments, recipients should exhaust less costly alternatives.
Borrowing against future payments
Some lenders offer loans collateralized by structured settlement payment rights. Interest rates vary but are typically lower than the effective discount rate of an outright sale.
| Option | Typical effective cost | Retain future payments? |
| Structured settlement sale (lump sum) | 9%–18% discount rate (NASP industry data) | No |
| Personal loan (good credit) | 7%–13% APR (Federal Reserve G.19, Q1 2024) | Yes |
| Home equity line of credit | 8%–10% APR (Bankrate, 2024 average) | Yes |
| 401(k) hardship withdrawal | 10% penalty + income tax (IRS rules) | N/A |
Negotiating with the annuity issuer
Life insurers that issued the annuity — companies such as MetLife, Berkshire Hathaway and Pacific Life — sometimes allow accelerated or commuted payments. Recipients should call the issuer directly and ask about acceleration provisions in their contract.
Government and nonprofit assistance
- Medicaid and SNAP: Structured settlement recipients facing medical or food costs may qualify for need-based programs without selling payments. Eligibility rules vary by state.
- Local legal aid: Organizations funded through the Legal Services Corporation can review settlement documents at no cost and advise on alternatives.
- Nonprofit credit counseling: Agencies accredited by the National Foundation for Credit Counseling (NFCC) offer free debt-management plans that may eliminate the need to liquidate a settlement.
Partial sales
Rather than selling the entire payment stream, recipients can sell a limited number of future payments — for example, 24 months of a 20-year annuity — retaining long-term income. Most factoring companies, including J.G. Wentworth and DRB Capital, offer partial-purchase options.
Caution: Structured settlement payments carry tax-free status under IRC § 104(a)(2). Selling payments may affect eligibility for means-tested benefits. Consult a qualified financial advisor or attorney before proceeding.
Frequently Asked Questions
Who buys structured settlements?
Specialized structured settlement factoring companies buy the right to receive some or all of a recipient’s future payments. The buyer pays a discounted lump sum, and the recipient generally transfers the assigned payments rather than the original settlement agreement itself.
Do insurance companies buy structured settlements?
The insurance company that funded or issued an annuity usually is not the buyer in a secondary-market transaction. A separate factoring company typically purchases payment rights, subject to the transfer rules in the federal Structured Settlement Protection Act and applicable state law.
Can a bank buy a structured settlement?
A bank may participate in structured-settlement finance or provide funding to a factoring company, but banks are not ordinarily the direct purchaser presented to recipients.
The proposed buyer’s legal identity, funding source, discount rate, fees and payment amount should appear in the transfer documents.
Can an individual investor buy structured settlement payments?
In some transactions, an individual or investment entity may acquire assigned payment rights through a structured finance arrangement, but availability depends on the transaction structure and state law.
A recipient should not assume that a private buyer has the same disclosures, oversight or financial capacity as an established factoring company.
Do brokers buy structured settlements?
A broker usually markets the payment rights and connects the recipient with potential buyers rather than purchasing the settlement directly.
Broker compensation can affect the quoted proceeds, so the recipient should request written disclosure of commissions, competing offers and every deduction before signing.
Who buys a structured settlement after a court approves the transfer?
The approved buyer named in the transfer agreement purchases the assigned future payments after the court or other required authority finds that the transaction serves the recipient’s best interest under applicable law.
Court approval does not guarantee that the price is favorable or that the recipient can reverse the transfer.
How can someone verify a structured settlement buyer?
The recipient can verify the company’s legal name, state registrations, litigation history, funding disclosures and required transfer documents through state regulators, court records and the settlement agreement.
The Consumer Financial Protection Bureau and the National Association of Insurance Commissioners provide consumer information, but a recipient should obtain independent legal or financial advice before transferring payment rights.
Related Reading
- Buy Structured Settlement – What You Need to Know?
- Structured Settlement vs Annuity
- Structured Settlement Debt Collector
- Structured Settlement Calculator
- Structured Settlement Annuities for Minors
- Structured Settlement Collection Agency
- JG Wentworth Structured Settlement
- AIG Structured Settlements
- All Structured Settlements & Annuities Guides
- National Association of Insurance Commissioners — Structured Settlements (2024)
- U.S. Securities and Exchange Commission — Structured Settlements (2023)
- Internal Revenue Service — Structured Settlement Factoring Transactions (IRC §5891) (2024)
- National Conference of State Legislatures — Structured Settlement Protection Acts (2023)
- U.S. Government Accountability Office — Structured Settlements Report (2005)
- Cornell Law Institute — 26 U.S. Code §5891: Structured Settlement Factoring Transactions (2024)