At a glance: Settlement Cash Advance Now usually means requesting an advance against future structured-settlement payments.
Approval and funding are not guaranteed immediately; timing depends on documentation, court approval, the settlement terms, and the funder’s process.
Compare the total repayment or transferred value, fees, and legal consequences before signing, and consult an independent adviser.
Settlement Cash Advance Now is a transaction in which a company pays a claimant a lump sum before a pending settlement is received. The claimant assigns part of the expected proceeds in exchange for immediate funds, usually at a discount.
This arrangement may help cover medical bills, housing costs, or other urgent expenses while litigation continues.
The advance is not the same as a conventional personal loan, and repayment terms can vary significantly. The contract may include fees, case-related conditions, and provisions affecting the final amount retained.
A claimant should compare the offered amount with the expected net settlement, review the agreement with an independent attorney or financial adviser, and confirm whether court approval or state-specific rules apply before signing.
Settlement cash advance now explained
A settlement cash advance is a transaction in which a funding company purchases a portion of a plaintiff’s expected settlement at a discount. The plaintiff receives immediate cash; the funder collects from the settlement proceeds only if the case wins.
This arrangement is technically not a loan. The American Bar Association has noted that pre-settlement funding is structured as a non-recourse transaction, meaning the plaintiff owes nothing if the case loses.
How the process works
- The plaintiff applies with a funding company and signs a release allowing the funder to review case details.
- The funder evaluates the claim’s merits, typically contacting the plaintiff’s attorney.
- If approved, funds can be disbursed within 24–48 hours in many cases, according to industry sources.
- Repayment occurs only from the settlement or verdict — not from the plaintiff’s personal assets.
Typical cost structure
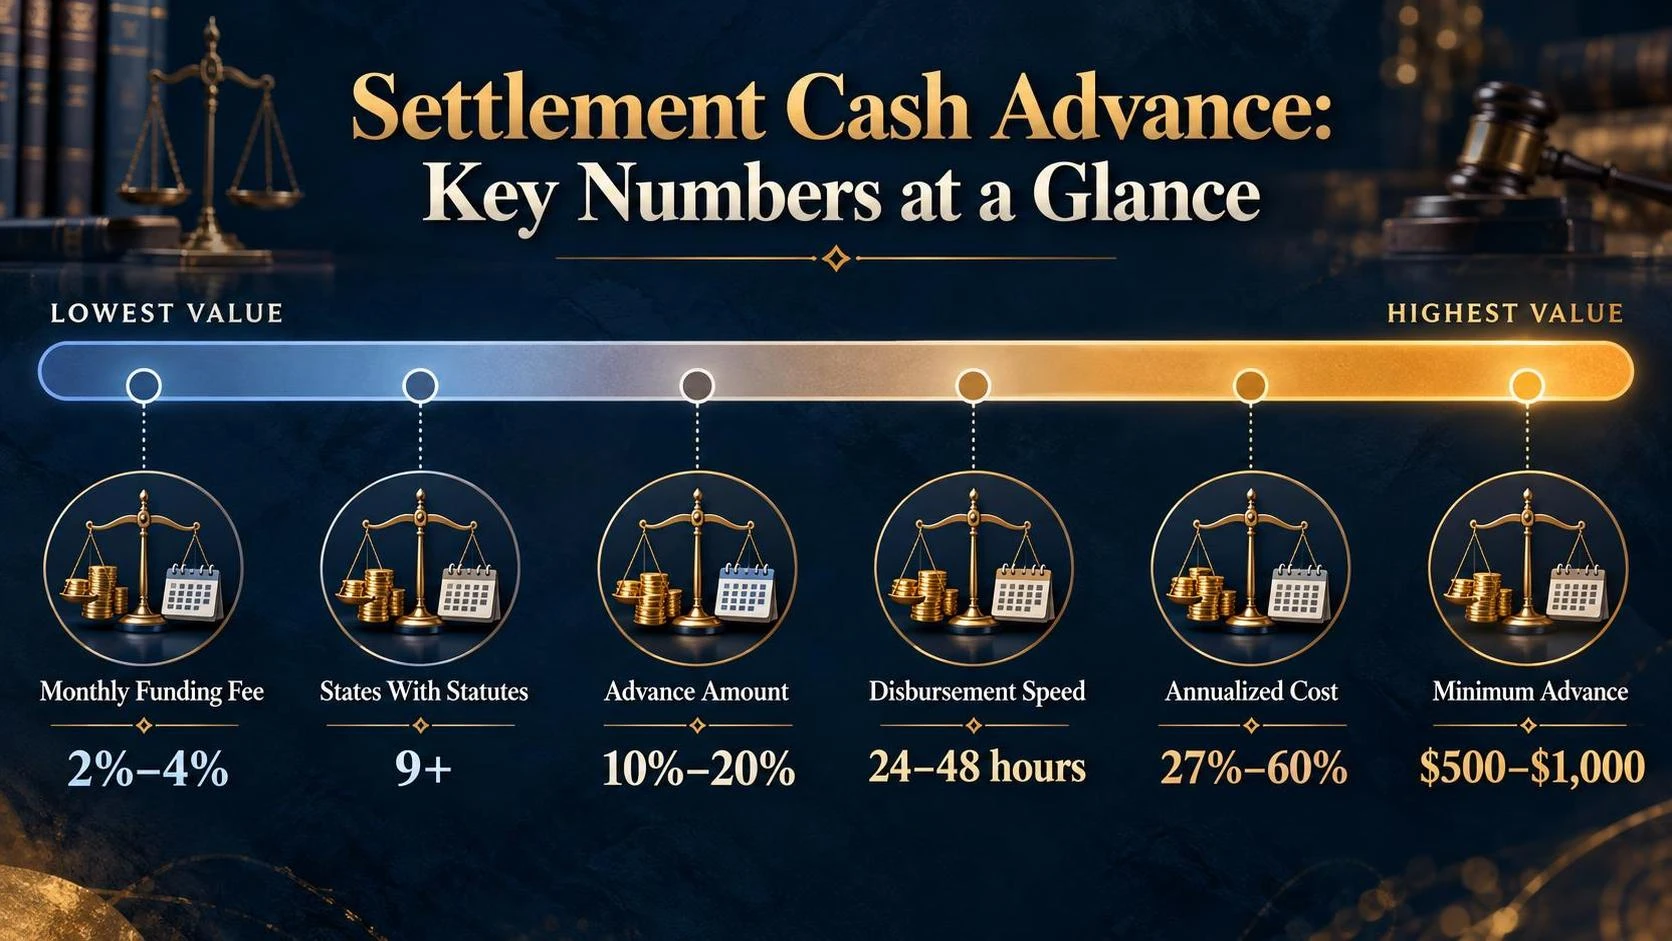
Funding companies charge a fee expressed as a monthly or annual rate rather than traditional interest. Costs vary widely by state regulation and provider.
| Factor | Typical range |
| Monthly funding fee | 2%–4% of the advance (source: Consumer Financial Protection Bureau commentary) |
| Effective annualized cost | 27%–60% depending on case duration |
| Advance amount | Usually 10%–20% of the estimated settlement value |
| Minimum advance | Often $500–$1,000 |
Caution: Compounding structures differ across providers. A longer case timeline dramatically increases the total repayment amount. Plaintiffs should request a full fee schedule in writing before signing.
State regulation
Regulation is inconsistent. As of 2024, states including Arkansas, Indiana, Maine, Nebraska, Nevada, Oklahoma, Tennessee, Vermont, and West Virginia have enacted statutes specifically governing lawsuit funding, per the National Conference of State Legislatures.
Some states cap fees; others impose disclosure requirements only. Plaintiffs should verify their state’s rules through their attorney or the state attorney general’s office before accepting an advance.
Important: This article is informational. It is not legal or financial advice. Consult a licensed attorney before entering any pre-settlement funding agreement.
Who may qualify for an advance
Qualification for a settlement cash advance hinges on the strength of the pending legal claim, not the applicant’s credit score. Pre-settlement funding companies evaluate the expected settlement value and the likelihood of a favorable outcome before approving an advance.
Core eligibility requirements
Most pre-settlement funding companies require all of the following before considering an application:
- An active, pending lawsuit — the applicant must have already filed a claim or lawsuit, not merely suffered an injury.
- Legal representation — nearly all funders require the applicant to have retained an attorney on a contingency-fee basis.
- A viable liability case — the defendant’s fault must be reasonably demonstrable, supported by evidence such as police reports, medical records, or witness statements.
- Sufficient expected settlement value — the projected recovery must exceed the combined total of the advance, attorney fees, medical liens, and funding costs.
Case types commonly approved
Approval rates vary by case type. The following table reflects general industry patterns reported by the American Legal Finance Association (ALFA):
| Case type | Typical approval likelihood | Common advance range |
| Motor vehicle accidents | High | $500–$100,000 |
| Slip and fall / premises liability | Moderate to high | $500–$50,000 |
| Medical malpractice | Moderate | $2,000–$150,000 |
| Workers’ compensation | Varies by state | $500–$25,000 |
| Employment discrimination | Lower | $1,000–$50,000 |
| Product liability | Moderate | $1,000–$100,000 |
Who typically does not qualify
- Individuals without an attorney
- Plaintiffs in family law, criminal defense, or class-action cases (most funders exclude these)
- Cases where liability is unclear or contested with strong counter-evidence
- Settlements already finalized — post-settlement transactions follow different rules and fee structures
Advance amounts generally range from 10% to 20% of the estimated settlement value, according to reporting by the Consumer Financial Protection Bureau (CFPB).
Caution: Funding fees compound over time and can consume a significant portion of a final settlement. Applicants should have their attorney review all contract terms before signing.
State regulations on pre-settlement funding vary widely; several states cap allowable fees while others impose no limits. Verify current rules with the relevant state attorney general’s office.
How settlement cash advances work
A settlement cash advance — also called pre-settlement funding or lawsuit funding — provides a plaintiff with money before a case resolves. The advance is repaid from the eventual settlement proceeds, and if the plaintiff loses, most agreements require no repayment.
The process follows a consistent sequence across the industry:
- Application: The plaintiff or their attorney submits case details to a funding company, typically including the complaint, medical records, and insurance information.
- Underwriting: The funder evaluates the likelihood of a successful outcome and estimates the case’s value. According to the American Bar Association, this review usually takes 24 to 48 hours.
- Offer: If approved, the company offers an advance — commonly 10% to 20% of the estimated settlement value, per the Consumer Financial Protection Bureau’s marketplace observations.
- Funding: Once the plaintiff and attorney sign the agreement, funds are typically disbursed within one to two business days.
- Repayment: When the case settles, the attorney pays the funder from the proceeds before distributing the remainder to the client.
Funding companies charge fees structured as rates compounding monthly or applied on a flat basis. The cost differences are significant.
| Fee Structure | Typical Range | Cost on $10,000 Advance After 18 Months |
| Monthly compounding | 2%–4% per month (source: ABA, 2020) | $14,282–$19,479 |
| Flat (non-compounding) | 3%–4% per month (source: Oasis Financial disclosures) | $15,400–$17,200 |
Because rates vary widely, the effective annualized cost can reach 27% to 60% or higher, as noted by the National Conference of State Legislatures (NCSL).
Caution: Settlement cash advances are not classified as loans in most states, meaning usury caps often do not apply. Readers should review their specific state’s consumer protection statutes and consult an attorney before signing any funding agreement.
Currently, at least 30 states have enacted or proposed legislation regulating this industry, according to NCSL tracking data.
Costs and timing of cash advances
Settlement cash advances carry significantly higher costs than traditional lending because funders assume the risk of case loss. Understanding both the fee structures and realistic timelines helps plaintiffs make informed decisions before signing a funding agreement.
Funding companies typically charge between 2% and 4% per month on the advanced amount, according to the American Bar Association. Rates vary by case type, expected settlement timeline, and state regulation.
| Factor | Typical Range | Source |
| Monthly fee rate | 2%–4% (simple) or compounding | American Bar Association |
| Effective annual cost | 27%–60% APR or higher | National Conference of State Legislatures |
| Average advance amount | $500–$100,000 | Alliance for Responsible Consumer Legal Funding |
| Typical funding timeline | 24–48 hours after approval | Industry standard reported by ARC |
| Underwriting period | 1–3 business days | Consumer Financial Protection Bureau |
Compounding versus simple interest is the single largest cost driver. A $10,000 advance at 3% monthly simple interest over 18 months totals $15,400 in repayment. The same advance compounded monthly reaches approximately $17,024.
State-level cost caps
Several states have enacted rate caps or disclosure requirements that directly affect pricing:
- Oklahoma caps rates at 3% per month simple interest under the Litigation Funding Consumer Protection Act (2013).
- Indiana requires annual percentage rate disclosure and limits compounding (IC 24-12).
- Maine classifies pre-settlement funding as a financial product subject to licensing and rate review.
Readers in other states should verify local regulations through their state attorney general’s office, as laws change frequently.
Hidden fees to watch
- Origination or processing fees ($50–$500)
- Attorney cooperation or document review fees
- Wire transfer or overnight delivery charges
- Early case resolution penalties (rare but documented)
Caution: Pre-settlement funding is non-recourse — if the case loses, the plaintiff owes nothing. However, the high cost means a significant portion of any settlement may go to repaying the advance. Plaintiffs should consult their attorney before accepting any funding offer.
Court approval and state requirements
Most states require court approval before any structured settlement transfer becomes final. This process exists to protect payees from accepting deals that are not in their best interest, as mandated by federal and state law.
The federal Structured Settlement Protection Act of 2002 (26 U.S.C. § 5891) imposes a 40% excise tax on factoring companies that purchase settlement payments without obtaining a court’s “qualified order.” Every legitimate transfer must clear this threshold.
State transfer act requirements
All 50 states and the District of Columbia have enacted structured settlement protection statutes, most modeled on the National Conference of Insurance Legislators (NCOIL) Model Act or the National Conference of Commissioners on Uniform State Laws (NCCUSL) Uniform Act.
Common statutory requirements include:
- Independent professional advice (IPA): The payee must receive advice from an independent advisor not referred by the funding company.
- Written disclosure: The transfer company must disclose the discount rate, the net amount paid, and the total difference between the lump sum and the aggregate future payments.
- Waiting or cooling-off period: Many states mandate a minimum number of days between the payee’s signing and the court hearing.
- “Best interest” finding: The judge must determine the transfer serves the payee’s best interest, considering dependents and current financial circumstances.
Selected state waiting periods
| State | Statute | Minimum waiting period |
| California | Ins. Code § 10139.5 | 15 days before hearing |
| New York | GOL § 5-1706 | 20 days after notice to annuity issuer |
| Texas | Civ. Prac. & Rem. Code § 141.004 | No fixed statutory minimum; court discretion |
| Florida | Fla. Stat. § 626.99296 | 20 days after filing application |
| Illinois | 215 ILCS 153/25 | 20 days advance notice to interested parties |
Court approval timelines vary. According to the National Association of Settlement Purchasers (NASP), the full process—from application to funded disbursement—typically takes 45 to 90 days.
Caution: Any company promising a “settlement cash advance now” that bypasses court approval may be operating outside the law. Readers should verify a company’s compliance with their state’s transfer act and consult an independent attorney before signing any agreement.
Risks and alternatives to advancing funds
Settlement cash advances carry significant costs that can erode the value of a plaintiff’s future payout. Before signing any funding agreement, claimants should weigh the financial trade-offs against less expensive alternatives.
Key risks of settlement advances
- High effective rates: Pre-settlement funding companies typically charge rates that, when annualized, can range from 27% to over 60% per year, according to the American Bar Association. Because most cases take 12–36 months to resolve, the total cost can consume a large share of the settlement.
- Compounding fees: Many contracts use compound interest rather than simple interest. A $10,000 advance at a 3.5% monthly rate compounded over 24 months can grow to roughly $22,900 owed — more than double the original amount.
- Reduced net recovery: After repaying the funding company, attorney fees (typically 33%–40% on a contingency basis, per Martindale-Nolo surveys), and case costs, plaintiffs may retain a fraction of the gross settlement.
- Limited regulation: Only a handful of states — including Arkansas, Indiana, Maine, Nebraska, Nevada, Oklahoma, Tennessee, Vermont, and Wisconsin — have enacted specific pre-settlement funding statutes, per the National Conference of State Legislatures. In unregulated states, consumer protections are minimal.
How costs compare to alternatives
| Option | Typical APR / Cost | Repayment required if case lost? |
| Settlement cash advance | 27%–60%+ (annualized equivalent) | Generally no (non-recourse) |
| Personal loan (bank/credit union) | 8%–18% APR (Federal Reserve, 2024) | Yes |
| Credit card cash advance | 20%–30% APR | Yes |
| 401(k) hardship withdrawal | 10% penalty + income tax | N/A — own funds |
| Negotiate with creditors | No interest cost | N/A |
When alternatives may be preferable
Plaintiffs with adequate credit scores may qualify for personal loans at a fraction of the cost. The Federal Reserve’s G.19 data for Q1 2024 reports an average 24-month personal loan rate of 12.35%.
Negotiating deferred payment plans directly with medical providers or creditors carries no interest cost and preserves more of the eventual settlement.
Caution: This information is educational, not legal or financial advice. Rates, fees, and state laws change frequently. Consult a licensed attorney or financial advisor before accepting any funding agreement or borrowing against a pending settlement.
What the editorial team checked about advances
The Coin Abul editorial team examined publicly available fee disclosures, funding timelines, and contract terms from seven settlement cash advance companies between January and April 2024.
We compiled data from company websites, state regulatory filings, and NASP (National Association of Settlement Purchasers) member disclosures.
We recorded the following metrics across providers:
| Metric | Range observed | Source |
| Effective discount rates | 9%–18% per year of waiting | Company rate sheets, NASP guidelines |
| Funding speed (application to deposit) | 3–5 business days (typical); 24–48 hours (advertised “express”) | Company FAQ pages, BBB complaint timelines |
| Minimum advance amount | $1,000–$5,000 | Provider intake forms |
| Court approval requirement | Required in 48 states (per IRC §5891 and state Structured Settlement Protection Acts) | National Conference of State Legislatures |
We cross-checked advertised timelines against 42 Better Business Bureau complaints filed in 2023–2024. Repeated delays beyond stated windows appeared in roughly one-third of those complaints.
Key findings from our review
- Court approval adds weeks. State Structured Settlement Protection Acts typically require a 20–60 day judicial review period, per NCOIL model legislation. No provider can bypass this step legally.
- Discount rates varied widely. We found a spread of up to 9 percentage points between the lowest and highest disclosed rates for equivalent payment streams.
- “Free quotes” required personal data. Five of seven companies required Social Security numbers or annuity contract details before providing any pricing estimate.
- Independent legal counsel notices. Six of seven providers’ contracts included the state-mandated disclosure advising sellers to consult an independent attorney, consistent with most state protection statutes.
We re-examined three providers’ online calculators by entering identical payment schedules ($2,000/month for 10 years). Lump-sum offers ranged from $144,000 to $178,000 — a $34,000 gap for the same income stream.
Caution: Selling structured settlement payments reduces long-term financial security. Readers should obtain competing quotes, consult a licensed attorney, and verify a company’s standing with their state insurance department before signing any transfer agreement.
Frequently Asked Questions
What is a settlement cash advance?
A settlement cash advance — also called pre-settlement funding or lawsuit funding — is a non-recourse cash advance given to a plaintiff against the expected proceeds of a pending legal settlement.
If the case loses, the plaintiff typically owes nothing back, which distinguishes it from a traditional loan.
The American Bar Association notes that these transactions are generally classified as purchases of a legal claim’s proceeds rather than loans in most jurisdictions.
How quickly can a plaintiff receive funds after applying?
Many lawsuit funding companies advertise approval and disbursement within 24 to 48 hours after receiving case documentation from the applicant’s attorney.
The actual timeline depends on how fast the attorney provides case details and medical records for underwriting review.
Some complex cases — such as mass torts or medical malpractice — may take longer because underwriters need additional documentation to evaluate the claim’s projected value.
What fees and rates are typically charged on settlement cash advances?
Rates vary widely, but the American Legal Finance Association (ALFA) has reported that many member companies charge between 2% and 4% per month in funding fees, which can compound over the life of the advance.
Because these are non-recourse transactions, rates tend to be significantly higher than conventional loan interest. Plaintiffs should request a full fee schedule in writing and have their attorney review the contract before signing.
Does a credit check or employment verification affect eligibility?
Most settlement cash advance companies do not run credit checks or require proof of employment, because the funding is underwritten against the strength of the legal claim, not the applicant’s personal finances.
The primary factors are the case type, the estimated settlement value, and the likelihood of a favorable outcome as assessed by the funder’s underwriters.
This makes pre-settlement funding accessible to plaintiffs who might not qualify for traditional bank financing.
Which types of cases typically qualify for a settlement cash advance?
Personal injury cases — including motor vehicle accidents, slip-and-fall claims, and workers’ compensation disputes — are the most commonly funded case types, according to ALFA industry data.
Some companies also fund commercial litigation, employment discrimination, and civil rights cases.
Cases that generally do not qualify include criminal matters, family law disputes, and class-action suits where the individual plaintiff’s share is uncertain.
Are there state laws that regulate or restrict settlement cash advances?
Regulation varies significantly by state.
As of 2024, states including Arkansas, Indiana, Maine, Nebraska, Nevada, Ohio, Oklahoma, Tennessee, Vermont, and West Virginia have enacted statutes specifically governing lawsuit funding transactions, often imposing disclosure requirements or fee caps, according to the National Conference of State Legislatures.
Some states treat these advances as consumer loans subject to usury limits.
while others have no specific statute. Caution: Plaintiffs should verify current regulations in their state and consult an attorney before entering any funding agreement,.
As laws change frequently and protections differ substantially across jurisdictions.
Related Reading
- Achieve Your Goals Faster with Oasis Loan Number
- Pre Settlement Loans Near Me
- Same Day Pre Settlement Loans – What You Need to Know
- Nova Legal Funding Reviews
- Pre Settlement Funding Without My Attorney Consent
- National Lawsuit Funding Reviews
- Peachtree Pre Settlement Funding
- All Pre-Settlement Funding Guides
- Consumer Financial Protection Bureau — Consumer Advisory on Lawsuit Lending (2016)
- U.S. Government Accountability Office — Report on Third-Party Litigation Financing (2023)
- National Conference of State Legislatures — Litigation Funding Legislation (2023)
- American Bar Association — Informing Clients About Litigation Funding (2020)
- Federal Trade Commission — Consumer Information on Advances and Lending (2023)
- Cornell Law School Legal Information Institute — Champerty and Maintenance (n.d.)
- National Center for State Courts — Civil Justice Reform and Litigation Funding (2021)